The Intelligent Driving Market is Heating Up, Yet Some Suppliers Struggle to Keep Pace!
 10/29 2026
 327
At present, urban Navigation on Autopilot (NOA) is becoming increasingly accessible across a wide range of vehicle models, prompting intelligent driving suppliers to compete fiercely for new mass production projects.
However, the burgeoning industry fervor hasn't translated into improved conditions for all companies, as the benefits of scale growth have not been uniformly distributed among suppliers.
In July 2026, media outlets reported that a supplier, formed by merging two intelligent driving teams, had initiated multiple rounds of personnel restructuring within a year, impacting departments such as algorithm development, software development, and testing, with an anticipated reduction of over 200 staff members.
Over the past year, layoffs, work stoppages, and even bankruptcy liquidations among intelligent driving suppliers have become increasingly prevalent.
Despite the expanding intelligent driving market, why are some companies with technological prowess, R&D teams, and mass production projects beginning to encounter operational pressures?
01 With Orders and Technology, Why Is Profitability Still Elusive?
In recent years, securing designations from automakers and entering mass-produced vehicle models has been a key competitive focus for intelligent driving companies, aiming to dilute R&D costs through more projects.
However, in practice, securing a designation is merely the starting point of the commercial chain.
Transitioning an intelligent driving solution from designation to mass production necessitates chip platform adaptation, software development, vehicle calibration, and rigorous testing and validation.
Variations in sensor layouts, computing platforms, and vehicle motion characteristics across different models mean that even if underlying algorithms can be reused, not all development work can be directly replicated.
If suppliers continuously reduce their quotes to win projects while development and adaptation costs remain high, an increase in project volume may instead impose greater resource pressures.
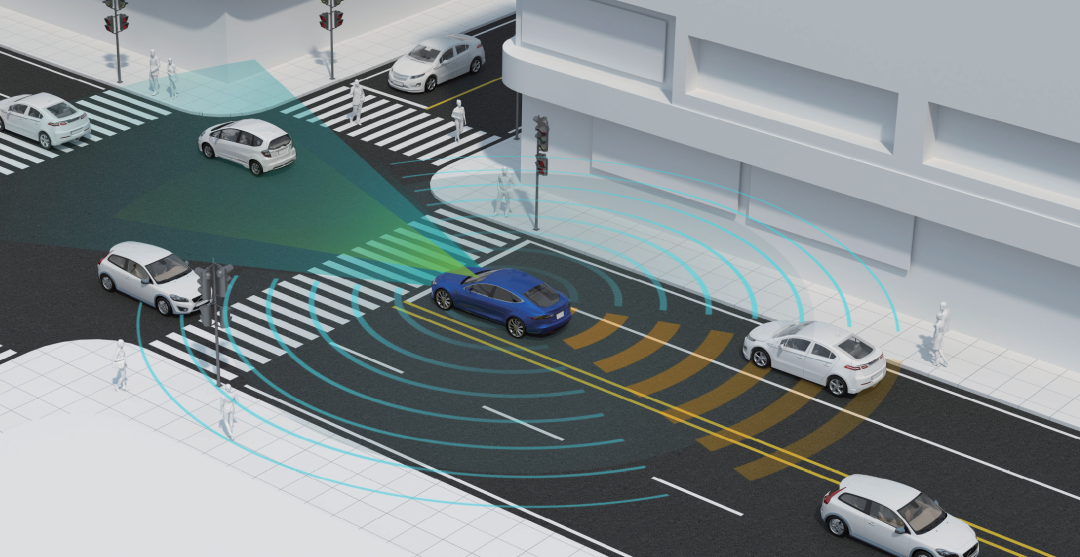 Image Source: Internet
Moreover, intelligent driving projects do not conclude with a single delivery.
Post-mass production, suppliers are still responsible for software updates, troubleshooting, new scenario validation, and subsequent vehicle model adaptations.
Customers are not purchasing a one-time delivered algorithm but a system that requires ongoing maintenance.
This discrepancy makes it challenging for automakers and suppliers to align their perspectives. Automakers focus on per-vehicle procurement costs, while suppliers may shoulder the entire long-term R&D and delivery costs.
Momenta, a prominent player in the intelligent driving supplier arena, has garnered recognition for its mass production projects with multiple automakers.
In the first half of 2026, it reported revenue of 1.602 billion yuan, a 75.9% year-on-year increase; R&D investment during the same period was 1.16 billion yuan, equivalent to 72.6% of revenue.
The company's adjusted net loss narrowed to 14.097 million yuan, indicating significant operational improvement.
Nevertheless, these figures also highlight that even when intelligent driving companies achieve a certain scale of mass production, they must continually invest resources to maintain technological competitiveness.
For suppliers with fewer clients and lower project reuse rates, this pressure is even more pronounced.
What intelligent driving companies truly require is not just more designations but projects that can consistently translate into shipments, revenue, and cash flow.
02 As Automakers Pursue In-House Development, What Can Suppliers Rely On to Build Advantages?
Nowadays, automakers' desire for control over core intelligent driving capabilities is on the rise.
For automakers, intelligent driving is no longer just a functional module that can be independently procured; it also relates to the overall vehicle product experience, software iteration efficiency, R&D costs, and brand differentiation.
Having autonomous control over key technologies provides the opportunity to more directly manage product development timelines. However, in-house development does not imply that all automakers will abandon external suppliers.
Chips, algorithms, toolchains, and complete solutions involve different R&D barriers, and automakers must make choices based on their scale, technological accumulation, and product planning.
Against this backdrop, suppliers must re-prove their value.
If a supplier primarily relies on customizing software for different vehicle models to generate revenue, does having more projects necessarily equate to having an advantage?
If entering each new vehicle model demands significant engineering personnel and existing solutions are difficult to reuse in other projects, scale growth may not yield the expected cost advantages.
Image Source: Internet
Conversely, if suppliers possess reusable platforms, mature development tools, and stable delivery systems, the same technology can serve more vehicle models, amortizing upfront R&D costs across a larger business scale.
This is why different business models among intelligent driving suppliers lead to divergent operational outcomes.
Take Horizon Robotics as an example; its business encompasses not only intelligent driving computing platforms but also expansion into licensing and services and assisted driving solutions.
In the first half of 2026, its licensing and services revenue grew by 52.7% year-on-year to reach 1.129 billion yuan, surpassing revenue from products and solutions during the same period.
Horizon's licensing revenue can exceed product revenue because it provides underlying capabilities like chip architectures and toolchains, which clients can utilize to complete upper-layer development themselves.
For suppliers delivering complete solutions, the key consideration is how to minimize customizable parts, so that when the same platform enters new vehicle models, incremental engineering investment does not rise linearly with project volume.
When automakers have more technological options, a supplier's competitiveness must not only be demonstrated in its ability to deliver functionality for a specific project but also in its capacity to apply proven technologies to more clients at lower marginal costs and with more stable delivery quality.
03 Why Does Competitiveness Remain Elusive After Team Integration?
Personnel adjustments are the most visible indicator of operational pressure within a company, but they are not necessarily the root cause of the problem.
The aforementioned intelligent driving supplier, after integrating two teams, initially hoped to form a product portfolio covering different levels of assisted driving through resource integration.
However, subsequent media reports indicated that some of the company's newly acquired projects were more focused on entry-level solutions, with reduced resource investment in mid-to-high-level projects, and some projects were terminated or faced cancellation.
Often, team integration rarely achieves a 1+1>2 effect. Merging two teams does not automatically mean their technologies will seamlessly fuse, nor will it automatically convert existing clients and projects into stable revenue.
Different teams may adopt disparate technical architectures, development processes, and project management approaches.
Post-integration, companies must still clarify product boundaries, unify technical platforms, allocate R&D resources, and determine which directions warrant sustained investment.
If the product line is too broad, with each direction requiring R&D personnel, testing resources, and client adaptations, the company may simultaneously bear the costs of multiple technological paths.
Image Source: Internet
If market demand shifts or some projects fail to materialize as planned, the original resource allocation will need to be readjusted.
However, personnel reductions alone do not indicate that a company has lost its technological competitiveness.
Reasonable resource adjustments can also help companies concentrate their efforts, abandon low-return projects, and redirect R&D investment toward products with greater mass production prospects.
The key is whether, after adjustments, the company retains its core R&D capabilities, can still deliver on client projects, and has a sustainable product roadmap. While reducing headcount can lower some costs, it does not automatically resolve issues like uncompetitive products, unprofitable projects, or changing client needs.
If a company merely shrinks its team without improving project profitability and technological reuse efficiency, operational pressures may still resurface.
04 Competition in the Intelligent Driving Industry Is Shifting from Project Acquisition to Operational Capability
Amid the ongoing surge in the intelligent driving industry, the situations of intelligent driving suppliers vary widely.
Some companies have multi-layered businesses encompassing chips, software, and toolchains, enabling them to generate revenue from various products; some focus on mass-produced assisted driving as their core, expanding clients through technology development services and software licensing; while others rely mainly on custom projects, requiring continuous investment in engineering personnel for vehicle model development.
Each route has its market, but they have different requirements for R&D investment, client structure, and scalable delivery.
For companies focused on custom projects, the number of clients, profit margins per project, and payment cycles may directly impact how large a team they can maintain.
Image Source: Internet
For companies with reusable platforms, the competitive focus lies in whether they can replicate their technological capabilities across more vehicle models while controlling the development costs of new projects.
Therefore, competition in the intelligent driving industry is shifting from whether technology can be developed to whether it can be transformed into a sustainable business at a viable cost.
Technology remains a prerequisite for entry, determining whether a supplier can enter the market; but after entry, commercial capabilities determine whether the technology can continue to iterate and form a long-term business.
As urban NOA gradually penetrates vehicle models across more price ranges, the popularization of basic functions will also raise the competitive barriers for suppliers.
Companies must not only prove they can develop an intelligent driving system but also demonstrate that the system is sufficiently differentiated, can be delivered stably, and is worth clients' continued procurement.
For intelligent driving companies, the most perilous situation may not be temporarily failing to secure new orders but having invested significant resources without being able to form reusable products or sustainable revenue.
05 Final Thoughts
The hotter the intelligent driving market gets, the more crucial it is not just to focus on how many designations a company has secured, how many R&D personnel it has, or how advanced its technology is.
What matters more is whether it can translate that technology into sustained mass production delivery and operational returns.
The market is still expanding, but not all companies will benefit equally.
Going forward, what will truly differentiate intelligent driving suppliers may not just be the level of their technological capabilities but also who can turn technology into a long-term, sustainable business at a viable cost. #AutonomousDriving #IntelligentDrivingSuppliers
-
![]()
Twitter Founder Returns to the Spotlight with a Blockbuster Offline Chat 'Tool'
-
Li, Xiao, and Wei: Struggling in the Valuation Trough - Same Decline, Different Destinies, Three Companies at Distinct Stages
-
Steadily Ranking First Globally: 4 Key Insights from Fuyao Glass for Chinese Enterprises", "Fuyao Glass, automotive glass, global leadership, market share, vertical integration", "Fuyao Glass maintain
-
New Pure Electric GLC Fails to Halt Mercedes-Benz Sales Slide; 30% Drop Persists Post-Leadership Change; Zhang Mingxia Struggles to Reverse Decline
-
![]()
JavaScript and Node.js: Why Front-End Games Can Be Tampered With
-
![]()
Leqi II's Answer Sheet: How Many of the Four Optical Hurdles Has It Cleared?
-
![]()
The Intelligent Driving Market is Heating Up, Yet Some Suppliers Struggle to Keep Pace!
-
![]()
Medium-Heavy Trucks and Large Buses: Draft for Approval of Mandatory AEB National Standards Released