The Next Frontier: AI Smartphones?
 09/20 2026
 519

AI Smartphones: The Industry's New Focal Point
Image source | Network (Please contact us for removal if infringement occurs). Partially generated by AI.
In late 2025, an engineering prototype priced at 3,499 yuan quietly went on sale with minimal pre-launch promotion. Approximately 30,000 units were stocked for the initial release and sold out the same day, with second-hand market prices soaring to 13,000 yuan at one point.
This device lacked top-tier imaging modules, foldable screen hinges, or even particularly stunning design. Its sole selling point was an AI agent embedded within the phone's system that could truly "work on your behalf."
Nine months later, an updated version officially entered mass production with stock levels raised to 200,000 units and starting prices reaching 5,999 yuan. However, this time, the market did not replicate its initial frenzy.
Except for certain color variants selling out, most versions remained readily available, and resale activity on platforms like Xianyu remained subdued.
The shift from "impossible to find" to "easily purchasable" is intriguing in itself.
It does not indicate waning enthusiasm for AI smartphones. On the contrary, when a product transitions from a "scarce topic" to a "normal commodity," it often signals its progression from the early adopter phase into genuine competition.
And the direction of this competition is undergoing fundamental change.
The Focus of Computing Power Shifts from Cloud to Palm
Rewinding two or three years, the fiercest battles in tech revolved around the cloud. Major companies raced to release large models with hundreds of billions of parameters, competing on training data volume, parameter scale, and benchmark scores.
This represented a classic "arms race" centered on whose model was smarter.
But model intelligence soon ceased to be the issue. As multiple foundational models converged in capability, competition shifted downward—primarily from "whose model is better" to "where the model originates and where it lands."
The object of contention transformed from the models themselves to access points.
The first round of access point competition occurred in office scenarios. By mid-2026, internet giants intensified their investments in AI-powered office solutions, pivoting from "parameter competition" to "access point capture," with rapid escalation in positioning battles around workplace desktops.
The logic was clear: office work represents a high-frequency daily scenario for users and a rigidity (essential) market where enterprises are willing to pay. Whoever dominates the first touchpoint for workplace tasks gains the most direct pathway to AI commercialization.
However, office scenarios have an inherent ceiling since they only cover part of users' waking hours.
The device truly accompanying users 24/7, handling the most interactions, and possessing the richest sensor data is the smartphone.
Thus, the second migration of computing power focus became almost inevitable: from office desktops to palms.
2026 has been dubbed the "first year of AI-native smartphones" by multiple industry insiders. That year, regulators publicly released Record Filing Information (filing information) for seven on-device generative AI services for the first time, transitioning on-device AI from a gray zone to regulatory compliance.
The maturation of on-device computing power, breakthroughs in lightweight large model technologies, and gradually clarified regulatory frameworks converged to propel AI smartphones from concept to competitive arena.
Two Paths, One Core Question
With smartphones becoming the primary battleground for AI access points, a fundamental question emerges: How should AI and smartphone operating systems integrate?
This question proves thorny because it challenges the power structure that has defined the smartphone industry for nearly two decades. Historically, phone manufacturers controlled hardware and systems, application developers built services atop them, and users accessed different apps by tapping icons.
This order proved stable and efficient but rested on one premise: humans as the operational subject.
AI agents aim precisely to replace humans as the operational subject. When a user says, "Book me a high-speed rail ticket to Shanghai tomorrow," the AI must understand intent, open a ticketing app, fill in information, and complete payment—
This entire process requires the AI to span multiple apps and invoke system permissions previously triggered manually by users. This undermines the foundation of the existing order.
Different camps provided starkly contrasting answers.
Apple chose a "borrow brains but retain control" approach. In its latest system version, Apple introduced next-generation Apple Intelligence and a revamped Siri AI, with foundational models partially sourced from external partners. However, Apple solely defined how AI enters the system, what permissions it obtains, and how it invokes app capabilities.
Apple even constructed a dedicated private cloud computing architecture to ensure user data during processing "is never stored by Apple or shared with anyone, including Apple itself."
The core logic of this strategy: models can be externally supplied, but distribution and control rights at the operating system level must remain firmly in-house.
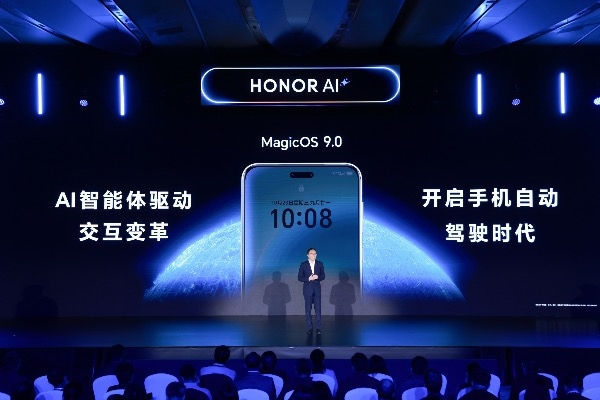
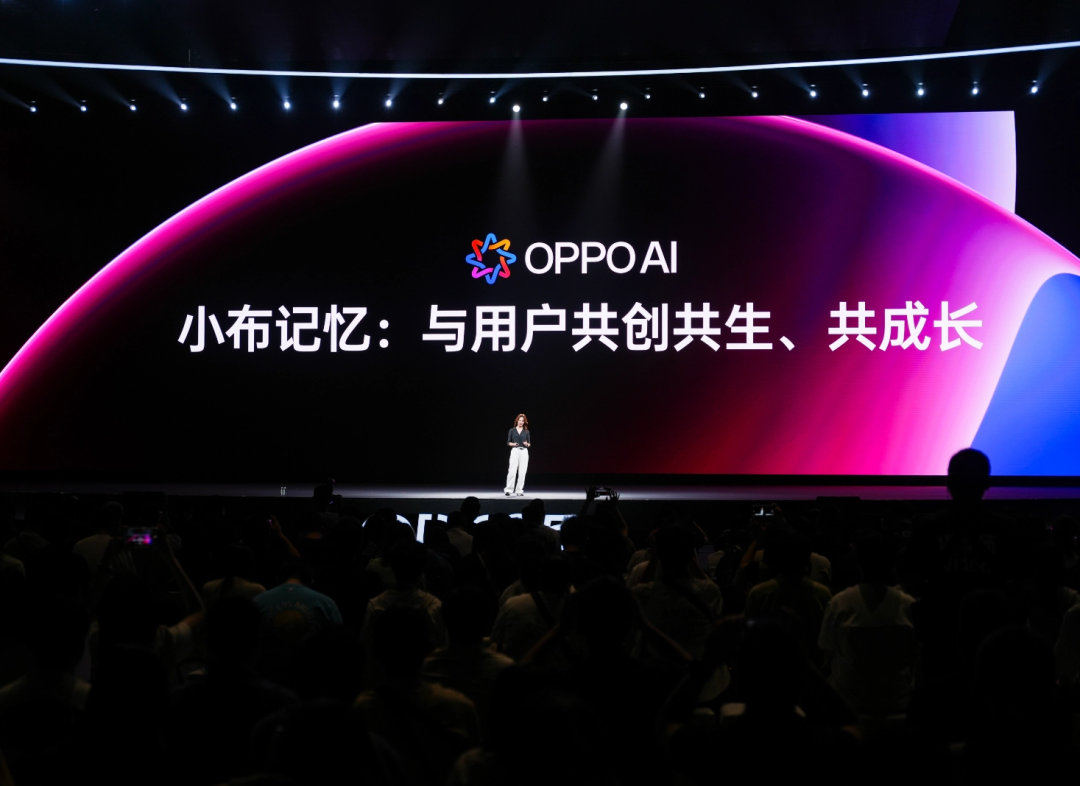
Explorations within the Android camp proved more diverse. A leading manufacturer unveiled three AI technology pillars at its latest developer conference: on-device large models natively supporting 128K context windows, memory usage reduced by 48% compared to the previous generation, and energy consumption optimized by 55%.
Another vendor launched what it claimed as the industry's first commercially deployed system-level intelligent agent execution framework, with its AI assistant capable of executing multi-step tasks spanning hundreds of actions.
Still another manufacturer set its pre-research target for on-device models at the 30 billion parameter level to provide stronger local reasoning capabilities for agents.
These paths appear different but all respond to the same question: When model capabilities become public infrastructure, where does differentiated competitiveness lie?
The answer is becoming clear: not in the models themselves, but beyond them. Whoever controls the operating system, masters the app and service ecosystem, and deeper understands user habits and scenario demands will gain an advantageous position in the AI smartphone race.
Models can be purchased or developed through partnerships, but operating system-level integration capabilities cannot be bought.
Conversely, large model companies entering the smartphone arena face the opposite situation. They control model development but lack operating systems, hardware, and extensive system permissions.
This precisely reflects the core challenge faced by that AI smartphone that triggered purchasing frenzies. While its model capabilities proved sufficiently strong and system-level permissions were obtained through deep collaboration with hardware manufacturers, whether third-party apps would open interfaces and cede data and operational permissions remained entirely at the discretion of individual app developers.
Behind this lie genuine concerns over data security and privacy compliance, as well as negotiations over reallocating traffic access points and commercial interests.
The Real Barrier Lies Beyond Technology
When discussing AI smartphones, many habitually focus on technical specifications: parameter counts of on-device models, response latency in milliseconds, or task success rates as percentages.
While important, these metrics do not constitute the decisive variables for whether AI smartphones will truly explode in popularity.
The real challenges reside at the ecosystem level.
The first generation of AI smartphones captured tremendous attention precisely because they demonstrated a radical new possibility: AI could "understand" smartphone screens like humans, simulate taps and swipes, and complete complex tasks across apps.
This technical approach, known as GUI Agent, offers intuitive advantages. It eliminates the need for each app to develop dedicated AI interfaces—as long as the AI can "read" the screen, it can operate all existing apps.
However, this approach quickly exposed vulnerabilities. Multiple mainstream apps and banking applications rapidly imposed technical and risk control restrictions on automated operations.
The reasons are clear: if AI can simulate operations, capture screen content, and modify data without user awareness, where do data security and privacy protection boundaries lie?
More pragmatically, if AI assistants can directly complete operations that previously required opening apps, what happens to app daily active users, ad impressions, and user engagement time? This strikes at the core interests of business models.
Second-generation products clearly adjusted their technical approaches, shifting from reliance solely on GUI simulation to incorporating protocol-based invocation methods.
Simultaneously, relevant teams introduced a screen automation operation declaration protocol, returning control over whether to permit AI-executed automation to app developers.
This represents a pragmatic choice but also means the capability boundaries of AI smartphones have effectively contracted.
Currently, agents embedded in the latest AI smartphones can smoothly invoke all products within their parent company's ecosystem and utilize a small number of partnered third-party services. However, leading apps like WeChat, Taobao, and JD.com do not yet support related operations.
This situation essentially reflects a multi-sided negotiation. Phone manufacturers hope AI becomes a super access point controlling user attention allocation. Large model companies aspire for model capabilities to become operating system-level infrastructure. App developers worry about their traffic and business models being sidelined. Users desire both convenience and privacy protection.
Whether on-device AI can truly become the super access point of the AI era depends on whether these four parties can reach an interest equilibrium.
Analysts point out that after technical conditions such as scaled deployment of on-device models and system-level commercialization of agent execution frameworks gradually mature, the most critical factor remains the reallocation of interests within AI application ecosystem development. As long as this issue is resolved, other problems cease to be primary contradictions.
This judgment proves sober. Technical problems can ultimately be solved through engineering means, but interest distribution represents structural challenges. It demands new protocol standards, new revenue-sharing mechanisms, and new trust frameworks—none of which any single company can accomplish independently.

The Underlying Logic of Market Transitions
Expanding our perspective reveals that the rise of AI smartphones does not represent an isolated event but rather an inevitable node in the ongoing migration of competitive focus within the AI industry.
Initial competition centered on models. More parameters, larger training datasets, and higher benchmark scores translated into discourse power (discourse power).
Though intense, this phase followed simple logic—essentially a contest of resource investment.
Competition then shifted to the application layer. As model capabilities became commoditized, people realized smart models alone were insufficient—actual usage scenarios were needed to put models to work.
AI-powered office solutions emerged as the first large-scale implementation battleground, with competition transitioning from technical parameters to scenario experience and ecosystem positioning.
Now, competition is sinking further to end-user devices. As the most frequently used intelligent devices with the richest data dimensions, smartphones naturally constitute the optimal carriers for AI agents.
They possess comprehensive sensor systems including microphones, cameras, GPS, accelerometers, and biosensors, continuously collecting multidimensional data on user location, behavior, health, and social interactions.
Feeding this data to on-device models enables construction of far more precise user profiles and scenario understandings than cloud-based models.
From large models to AI office applications and now to AI smartphones, this evolutionary trajectory follows a clear logic: AI value is shifting from "content generation" to "task execution," which requires a physical carrier sufficiently close to users. Smartphones perfectly fit this role.
Industry observers characterize this transformation as moving from "cloud-based dialogue" to "on-device execution," predicting 2026 as a pivotal year for AI agents, with innovative products reshaping the development logic of the internet over the past decades.
However, we must recognize that the current stage of AI smartphones does not perfectly mirror the early smartphone era when feature phones gave way to smartphones.
The driving force behind that transition was an interaction revolution—from physical keyboards to touchscreens—that fundamentally altered user habits.
AI smartphones introduce a more profound shift: operational subject transfer from humans to AI. While potentially more transformative, this change may prove less immediately perceptible to users.
This raises a practical question: Why should consumers pay a premium for a smartphone that "operates on their behalf"? For routine tasks like messaging, ordering food, or checking weather, existing smartphones already suffice.
To truly resonate with consumers, AI smartphones must deliver experiences unattainable without deep AI integration—such as automated cross-app complex tasks, personalized proactive services based on long-term memory, and seamless intelligent collaboration across multiple devices.
In other words, AI smartphones cannot merely represent "smartphones with an added AI assistant." They must become "smartphones that exist because of AI."
Writing up to this point, we might as well return to the question in the title: Is the AI smartphone the next track?
From an industry trend perspective, the answer leans towards 'yes.' The continuous improvement of on-device computing power, the maturation of lightweight large model technologies, the gradual clarification of regulatory frameworks, and the concentrated investment of strategic resources by major manufacturers all point in the same direction.
The penetration rate of generative AI smartphones has reached 36% by 2025 and is expected to exceed half by 2027. On-device AI is transforming from a differentiated selling point for high-end models into an industry standard.
When a technology shifts from being a 'selling point' to a 'standard feature,' it means it no longer needs to be proven but needs to be surpassed.
However, the term 'track' might not be entirely accurate. A track implies a racecourse with a starting and finishing line, where competitors race along the same path.
The changes brought about by AI smartphones are more akin to the opening of a new gateway. They redefine the relationship between users and devices, redistribute power along the mobile phone industry value chain, and redefine the boundaries of the 'smartphone' product form.
In the face of this new gateway, every company needs to rethink its position.
Mobile phone manufacturers need to answer: When AI can operate everything for users, do operating systems still need desktops and icons? App developers need to answer: When users no longer open your App but complete tasks through AI assistants, how is the value of your product measured?
Large model companies need to answer: When model capabilities become a public good, where is your competitive moat?
Currently, there are no standard answers to these questions.
But what is certain is that whoever can do better, deeper, and more securely in 'enabling AI to truly complete tasks for users' will occupy a favorable position in the next decade.
AI smartphones may not be the final destination, but they are likely the door to it.
What lies behind the door depends on the sincerity and patience of those standing at the threshold today in terms of allocating ecological benefits, building trust mechanisms, and innovating user experiences.
-
Three-Way Struggle for Market Share: BYD, Chery, and Geely Challenge Great Wall, Posing Immediate Risks to Wei Jianjun
-
![]()
The Reason Behind Valve's Headset Price Surge of 2400 Yuan: The End of an Era of Selling at a Loss
-
![]()
Decoding the '4S' Architecture | Report on Enterprise-Level AI Services in China
-
![]()
Li Auto Aims to Sell Three Technologies, First Buyers Unlikely to Be Major Automakers
-
![]()
Liu Zongcheng Declares Haste Makes Waste in Car Manufacturing, Yet Seres Seems to Be Rushing Headlong!
-
![]()
Did Trump Make Concessions? Chinese Automakers Are Invited to Establish Factories in the U.S., but Importing Fully Assembled Vehicles Is Off the Table
-
![]()
More Terrifying Than Runaway AI: The Tsunami of AI-Generated Vulnerabilities Has Arrived
-
AI Giants Hit the Brakes Collectively? They're Scared of Their Own Speed