Memory Prices Are Soaring, and Better Days Are Coming for Longcheer Technology and Its Peers
 11/04 2026
 567
Source | Yuanmeihui
Rising memory prices have driven up smartphone prices, and consumers are no longer willing to play the "sucker" footing the bill.
IDC data shows that in Q3 2026, domestic smartphone market shipments fell 15.2% year on year to about 58.06 million units. According to Counterpoint data, this shipment level marked the lowest for the same period since 2012.
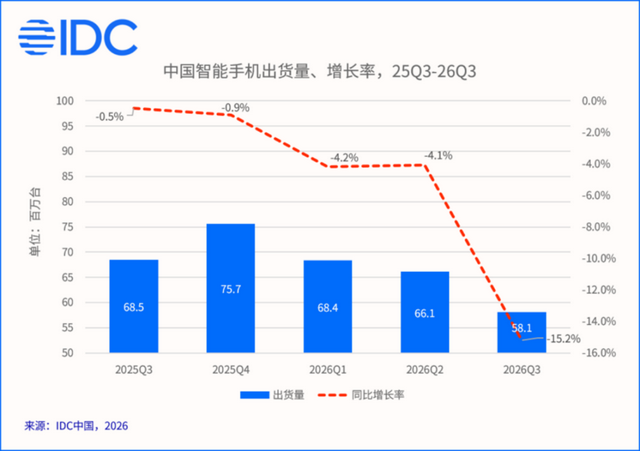
Image source: IDC
The reason for the shipment decline is simple: memory chips and other component costs have risen sharply. Data shows that memory's share of the BOM for low-end phones has risen from 10%–15% in normal years to 40%–50%.
Terminal brands are under shipment pressure, and the survival status of ODM giants caught in the middle of the supply chain has also become a market focus.
01.
Joy and Sorrow Are Not Shared
In this wave of memory price increases, mid- and upstream memory manufacturers have reaped rich dividends.
GigaDevice is a typical example. In the first three quarters of this year, its revenue rose 197.11% year on year to 20.297 billion yuan; net profit attributable to shareholders surged 921.55% year on year to 11.066 billion yuan.
This is not even the most dramatic increase. In the same period, ChangXin Technology's revenue and net profit attributable to shareholders surged 738.5% and 2,600.8% year on year, respectively, reaching 269.02 billion yuan and 132.04 billion yuan, with a gross margin as high as 89.53%.
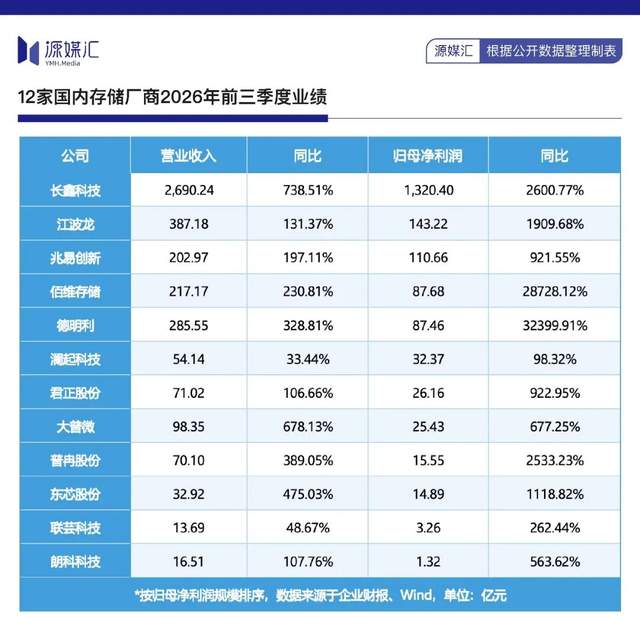
Even with prices already rising this much, Nomura's judgment is that this wave of memory chip price increases is likely to continue into 2028.
The core logic behind the continued boom is not complicated: strong siphon demand for HBM brought by the AI industry explosion has kept production capacity resources tilted toward high-end memory, squeezing the supply space for consumer-grade DRAM and NAND. This has also allowed companies like GigaDevice, which are not rule-makers, to become beneficiaries along the way.
The other side of dividends concentrating upstream is that downstream terminal manufacturers are forced to bear the pressure of price increases. The continued slump in the smartphone market is the most intuitive microcosm, and the traditional PC segment is under pressure as well.
IDC data shows that in Q3 2026, global traditional PC shipments were 62.7 million units, down 20.1% year on year and 9.1% quarter on quarter, the second consecutive quarter of year-on-year decline, with the drop notably wider than in Q2.
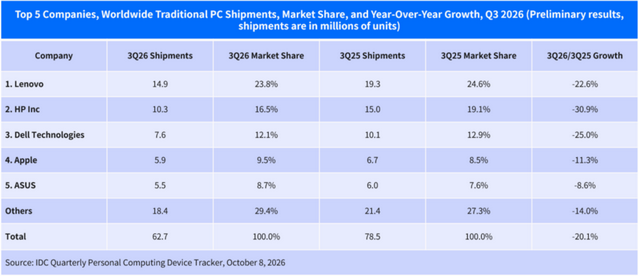
Image source: IDC
Leading brands generally suffered double-digit declines. In the third quarter, Lenovo shipped 14.9 million units, down 22.6% year on year, with a 23.8% market share, ranking first globally. HP shipped 10.3 million units, down 30.9% year on year, the largest decline among the top five vendors. Dell shipped 7.6 million units, down 25% year on year.
Terminal brands are already struggling, and the ODM industry has also bid farewell to its previous boom cycle. The segment once had a highlight: in the first half of 2025, ODM smartphone shipments accounted for 43% of the global total, a new high for the same period from 2019 to that time.
As demand for smartphone and PC terminals weakens simultaneously, the ODM market, which had risen for two consecutive years, has reached a turning point.
In the second half of 2025, ODM smartphone shipments fell 10% year on year. Institutions further predict that global ODM smartphone shipments will continue to decline in 2026, with a drop of about 10%–15%.
02.
ODM Giants Are Living Well
However, amid the overall market downturn, leading ODMs represented by Huaqin Technology and Longcheer Technology are not in as bad a situation as imagined. Their early diversified business layouts have become cushions for them to ride out the cycle.
Financial reports and Tianyancha information show that in the first three quarters of 2026, Huaqin Technology achieved revenue of 166.014 billion yuan and net profit attributable to shareholders of 4.323 billion yuan, up 28.81% and 39.53% year on year, respectively. In the third quarter alone, revenue and net profit attributable to shareholders rose 60.86% and 9.43% year on year, respectively.
However, Huaqin Technology's gross margin in the third quarter declined quarter on quarter, mainly due to the sharp growth in its data business. In this business, the storage and GPU Buy&Sell model accounts for a relatively high proportion. As the weight of the data business in overall revenue rises, it drags down the consolidated gross margin.
This also exposes a rule in the smartphone ODM industry that is easily overlooked: most procurement rights for smartphone memory chips are in the hands of brand customers, and ODMs operate under a customer-supplied materials model. Price increases themselves do not directly hit gross margin, but they squeeze profit space through another path.
Brand customers spend more on memory, and in turn they will be tighter on ODM processing fees and solution fees.
For Huaqin Technology, its smartphone business still managed to maintain positive revenue growth in the first three quarters, reflecting the head-concentration effect amid industry contraction; what truly supported the income statement was still the rapidly expanding data business. In Q3, revenue from this business reached 22.5 billion yuan, up 228% year on year, of which super nodes had achieved large-scale delivery, with revenue reaching 6.19 billion yuan.
The ROI (return on investment) of the super node business is higher than that of AI servers, making it a cushion for Huaqin Technology amid headwinds in the smartphone business.
In its latest institutional research, Huaqin mentioned that the company's ROE (return on equity) has long remained at an excellent level of 15%-20%. The seemingly low gross margin on the books is precisely part of the company's moat.
In other words, the core measure of whether a business is good is not gross margin, but ROE.
In the context of memory price increases, this statement carries more weight than usual. ODM profits have never come from buying memory chips low and selling high, but from scale, efficiency, customer stickiness, and category expansion.
Memory price increases have made the book gross margin of smartphone ODMs even thinner, but the ROE of leading manufacturers has not deteriorated in tandem. Wearables, AIoT, and data businesses have stepped in to fill the growth gap.
The overall smartphone market is shrinking, yet ODM penetration is actually rising, with share continuing to concentrate in Huaqin Technology and Longcheer Technology. This is one of the few structural hedges during the industry contraction period. Longcheer Technology's third-quarter report presents this hedging effect more intuitively.
In Q3 2026, the company achieved revenue of 13.930 billion yuan, up 21.94% year on year. In a quarter when industry shipments fell 15%, its revenue rose instead of falling.
Basically all businesses grew. Among them, the smartphone business reached 8.635 billion yuan, up 12% year on year; tablets reached 1.873 billion yuan, up 71.82% year on year; the AIoT business reached 3.221 billion yuan, with both year-on-year and quarter-on-quarter growth rates above 40%, accounting for 23% of single-quarter revenue.
Judging from the gross margins disclosed in 2025, the company's AIoT gross margin is significantly higher than that of smartphones and computers.
In other words, smartphones are a scale business, while AIoT is a capability business. The more diversified the categories and the deeper the customization, the higher the cost for customers to switch suppliers, and only then can pricing power fall into the hands of ODMs.
Longcheer's non-recurring net profit doubled quarter on quarter in Q3 and has grown at a high rate quarter on quarter for two consecutive quarters, indicating that an operating inflection point has already emerged.
03.
Can "Sub-1,000-Yuan Phones" Make a Comeback?
Of course, simply dividing the supply chain into beneficiaries and those under pressure remains superficial.
The deeper long-term impact of memory price increases on the smartphone supply chain lies not in single-quarter profit fluctuations, but in the irreversible contraction of product structure. In the first nine months of 2026, 286 new smartphone models were launched in the Chinese market, down 28.1% year on year.
According to Jiemian News, Xiaomi and OPPO cut full-year device orders by more than 20%, vivo by nearly 15%, and Transsion pressed its annual target below 70 million units, with order cuts concentrated in mid-to-low-end and overseas products.
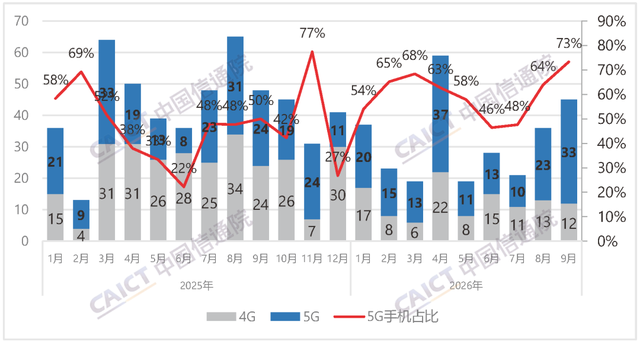
Image source: China Academy of Information and Communications Technology
Samsung was also forced to recalculate the memory configuration and pricing of its mid-range phones, and the domestic strategy of flooding the market with sub-1,000-yuan phones rapidly receded.
Some institutions judge that the increase in memory costs for sub-1,000-yuan phones has already swallowed all profits on the entire device, and in 2027, smartphones priced within 1,500 yuan may gradually fade out of the market. This means that memory price increases are not only squeezing profits, but directly "deleting" a sub-category. The exit of low-end phones releases not potential replacement demand, but persistently weakening willingness to replace devices.
IDC's global device senior executive once mentioned that against the backdrop of continuous price increases, consumers choose to extend the service life of existing devices, and consumers tend to extend the usage cycle of old phones. The advantage of domestic brands in the low-end market is precisely what makes them bear greater pressure in this round of adjustment.
Brands cut orders, the ceiling for ODM smartphone shipments moves down accordingly, and consumer storage demand from upstream design companies will also feel the same contraction after several quarters.
No one in a chain can forever make a living from price increases. Samsung issued a clear warning: 2027 may be the year with the tightest memory supply in this round, and it will be difficult for the supply-demand pattern to loosen thoroughly in 2028 either. For at least the next two years, the cost structure of the smartphone industry will be hard to return to the past.
How long GigaDevice's high profitability can last depends on when the siphon effect of AI on high-end memory capacity slows. Whether Huaqin's and Longcheer's smartphone businesses can stabilize depends on whether second growth curves such as wearables, AIoT, data, and automotive electronics can grow to sufficient scale before smartphone profits are compressed to the limit.
As for whether the sub-1,000-yuan phone category can return, perhaps it no longer depends solely on memory prices, but on whether the entire industry can accept the new normal of "higher phone prices and longer replacement cycles."
This third-quarter report is only the first card revealed in the new normal. The game is still going on, and the chips in the supply chain have already been redistributed.
Note: The article materials come from official reports and public information, and the views are for reference only | Some images come from the internet. If there is any infringement, please inform us for deletion.
-
![]()
Baidu AI Redraws Its Battle Lines
-
![]()
Memory Prices Are Soaring, and Better Days Are Coming for Longcheer Technology and Its Peers
-
![]()
Audi's North-South Split: Volkswagen Can't Afford to Wait
-
![]()
Doubao Phone Hits the Market: ByteDance's Bigger Game on the Phone Ecosystem
-
![]()
OpenAI's Mysterious Ghost Model Briefly Appears, API Pulled Within Minutes
-
![]()
Shenzhen Computing Power Chip Company Secures Nearly 2 Billion Yuan in Back-to-Back Financing
-
![]()
Najing Technology Secures Series A+ Funding in the Tens of Millions of Yuan!
-
![]()
Q3 Net Profit Plunges 30,154.65%: Lianchuang Electronics' Cracks Can No Longer Be Hidden