In an Overlooked Corner of China's Auto Market, Japanese Cars Are Almost Rotting Away | Juchao
 11/11 2026
 566
Editor | Yang Xuran
In October, Nissan launched a plug-in hybrid pickup truck in Mexico called the Frontier Pro. Its design, R&D, and production were all handled by Zhengzhou Nissan. This marks Nissan's first model developed and manufactured in China for global export, with Mexico as its first stop outside China.
That same autumn, Nissan announced another set of figures. In September, it sold 23,658 vehicles in China—a year-on-year plunge of 61.6%.
Honda's trajectory is even more telling. In 2020, it sold roughly 1.627 million vehicles in China; by 2025, only 645,000 remained. This September, media reported Honda's terminal sales in China at 25,564 vehicles, down 53.1% year on year.
These figures are neither the endpoint nor the bottom. In October, the share of Japanese brands in China's passenger car retail sales fell to 10.2%. In October 2020, that figure still stood at 23.9%.
In six years, the Chinese market went from roughly one in every four new cars being Japanese to one in every ten.
Many people's impression of Japanese cars remains stuck in the era when Accords and Sylphys were everywhere—even today, these cars are still a common sight on the road. But cars on the road are only one measure; how many new cars can be sold is obviously far more important for automakers.
The Chinese market, which kept growing in the past, could once accommodate the respective growth of automakers from both countries. Today, Japanese cars can basically be declared a complete defeat in competition in the Chinese market, and the remaining 10% market share will probably continue to erode.
This article is an in-depth value piece from the content team of "Juchao WAVE." We welcome you to follow us on multiple platforms.
Pullback
In the first 10 months of this year, China's passenger car retail sales totaled 14.978 million units, a year-on-year decrease of 22.3%. This figure is close to the 14.92 million units in the same period of 2020. Six years ago, the auto market was depressed because of the pandemic; this time, the industry has once again hit the ceiling of demand after several years of expansion.
Buying a car can easily be mistaken for some kind of high-frequency consumption—consumers go from no car to having a car, from having a car to replacing it, and from replacing it to upgrading to a luxury car. For many years in the past, once consumers already had a car, whether to spend another sum of money on a new one often did not depend on whether the old car could still be driven, but on people's firm consumer confidence.
Statistics from the Ministry of Public Security show that by the end of 2025, the national car parc had reached 366 million vehicles. Large cities have gone through a long period of car popularization, and counties and townships still have room for first-time purchases, but the speed at which these demands are released is completely different from when a large number of families bought cars for the first time back then.
Auto retail sales are so dismal, and there are also some specific reasons this year. In 2026, the purchase tax on new energy vehicles will shift from exemption within the limit to half-rate collection, so some orders from the end of last year were fulfilled in advance. This year is facing a previously elevated comparison base. The corresponding data is that in October, national passenger car retail sales rose 1.5% month on month, but fell 27.1% year on year.
Data from the National Bureau of Statistics show that in the first three quarters, total retail sales of consumer goods grew 1.1%, and grew 2.8% after excluding automobiles. Retail sales of automobiles by units above the designated size fell 14.9%.
When residents' expectations for future income are not stable enough, a car purchase expense of more than 100,000 yuan can easily be pushed back. If the old car can still be driven, cash flow can stay in hand first, and one can be a "wait-and-see person."
Car purchase decisions are also affected by public opinion. Store quotations keep moving lower round after round, and news of promotions and model updates is visible at any time on social platforms, so consumers will naturally wait for the next quotation. The China Passenger Car Association also mentioned in its weekly report at the end of October that negative industry public opinion may increase wait-and-see behavior among new energy vehicle buyers.
For families, replacing a car increasingly requires fuller reasons, but automakers need revenue and profit growth every year. Car buyers can wait again and again, but 4S stores have to pay rent and interest monthly.
The overall pullback in consumption is unavoidable, and it is cruel to all institutions across the entire chain.
Loss of ground
Japanese cars were once the safest choice among family cars priced around 100,000 yuan: fuel-efficient, few failures, and easy to resell. For a family car that would be driven for a long time, these were all very important considerations when buying. At the time, with the cost-effectiveness of the Corolla and Sylphy, there was basically no need to do much "multiple-choice."
In January this year, the new BYD Qin PLUS DM-i was launched with a guide price starting at 79,800 yuan. It belongs to the same compact family sedan category as the Corolla and Sylphy, can be used for electric commuting on weekdays, and can also refuel on long trips.
More importantly, in the past cars were compared by fuel consumption per 100 kilometers, but in the new energy era, that way of comparison has clearly lost meaning. Now people compare comprehensive factors such as range, battery, software upgrades, and assisted driving.
In October, retail sales of conventional fuel passenger cars were about 530,000 units, down 45% year on year. New energy retail sales were 1.109 million units, also down 13.7% year on year, but their share of domestic retail sales rose to 67.5%. While there are fewer car buyers, fuel vehicle consumers are disappearing even more thoroughly.
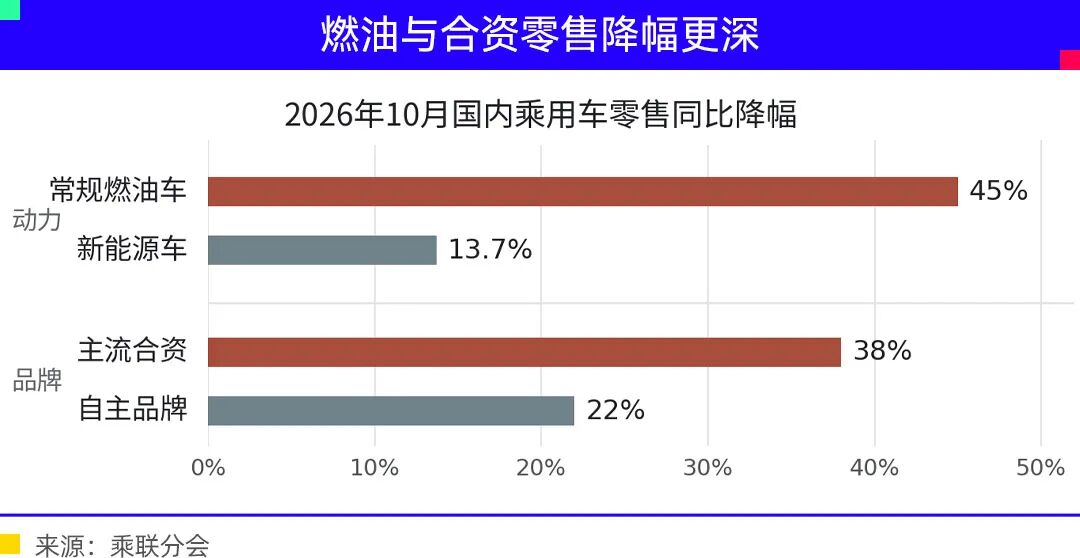
Japanese gasoline hybrids still have some buyers; people for whom charging is inconvenient will value low fuel consumption and refueling convenience. In October, retail sales of ordinary hybrid vehicles still grew 28% year on year. But this can no longer support the large share that once covered mainstream price segments.
Fuel consumption advantages can retain a small portion of orders, but what configurations domestic new energy vehicles can offer at the same price and how much they cost to drive daily are already accounts that the vast majority of families will calculate.
Japanese cars also used to have the advantage of value retention. But once manufacturers repeatedly cut prices, the transaction prices of new cars will also be transmitted to the used car market. Buyers will use today's new car prices as a reference, and the prices old car owners can sell for will come under pressure accordingly. The price cuts made for immediate sales may ultimately also weaken the extra money consumers were once willing to pay for Japanese cars.
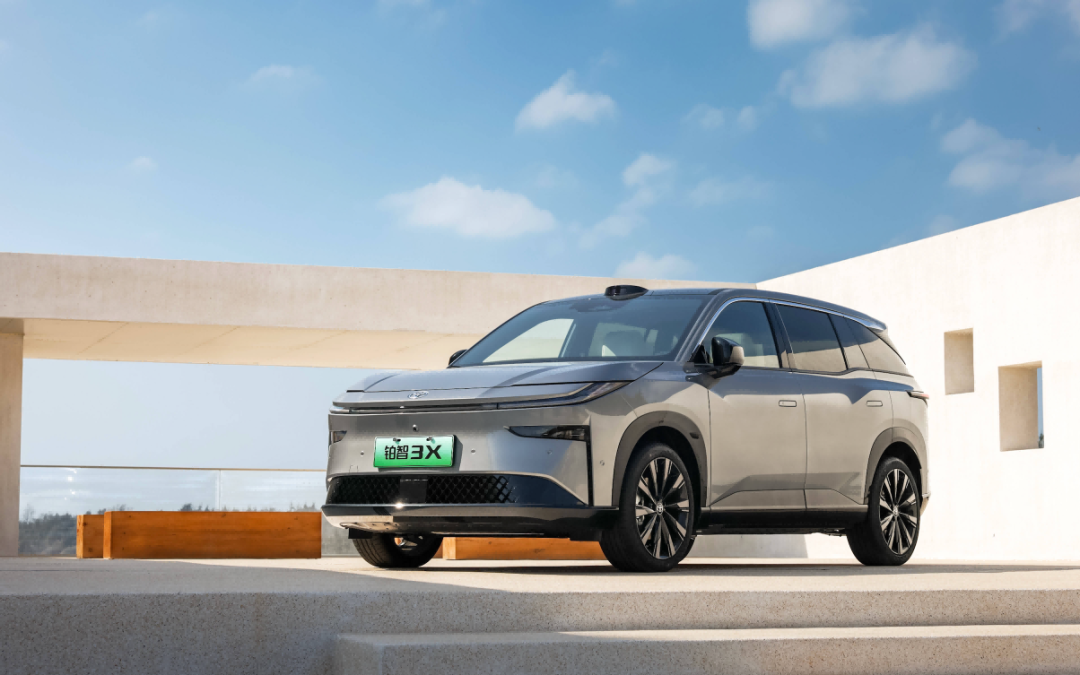
The GAC Toyota bZ3X launched in 2025 adopted a development approach led by a Chinese regional chief engineer and developed in cooperation with GAC. Materials disclosed by Toyota show that this model sold more than 70,000 units in total in 2025.
In the past, international automakers brought developed models to China, then reduced specifications and stretched dimensions, and their joint ventures in China could manufacture and sell them in bulk, but now the situation has completely changed.
Battery, electric drive, and cockpit suppliers, together with Chinese and foreign automakers, iterate synchronously in the Chinese market. Once a new configuration becomes mainstream, both Chinese and foreign automakers must quickly keep up, otherwise they will easily be ruthlessly abandoned by consumers.
There is one exception in this process: taking models coordinated in China to sell outside China. In the vast overseas market, there is still a stage for Chinese and Japanese automakers to compete.
Going global
In October, FAW, Toyota, and GAC signed a new cooperation framework. GAC plans to acquire the 50% equity interest in FAW Toyota held by FAW through the issuance of shares. FAW Toyota will continue to exist as an independent operating entity, and the two sides' joint venture plans further collaboration in R&D, procurement, production, and sales.
Toyota's move is under considerable practical pressure: China's auto market has already bound electrification, low-cost supply chains, and local development together. It is almost impossible to cover the Chinese market by relying on headquarters launching a global car every few years.
Today's joint ventures need to select suppliers in China, build R&D teams, and give these teams sufficient decision-making power. Moreover, the product strength and supply chain system formed in China cannot only serve the Chinese market.
As for Chinese automakers, they need to find an outlet for this major adjustment, and overseas is the core key. According to statistics from the China Passenger Car Association, in October passenger vehicles exported from China reached 928,000 units, up 68.5% year on year, including complete vehicles and knockdown assembly exports. This figure is already equivalent to 35% of wholesale sales by manufacturers that month.
Now that selling cars domestically is becoming more and more difficult, overseas business is beginning to directly affect capacity utilization and how much profit automakers can retain.
In Thailand, where Chinese automakers have the largest presence, the shape of the next round of competition between Chinese and Japanese automakers can already be clearly seen.
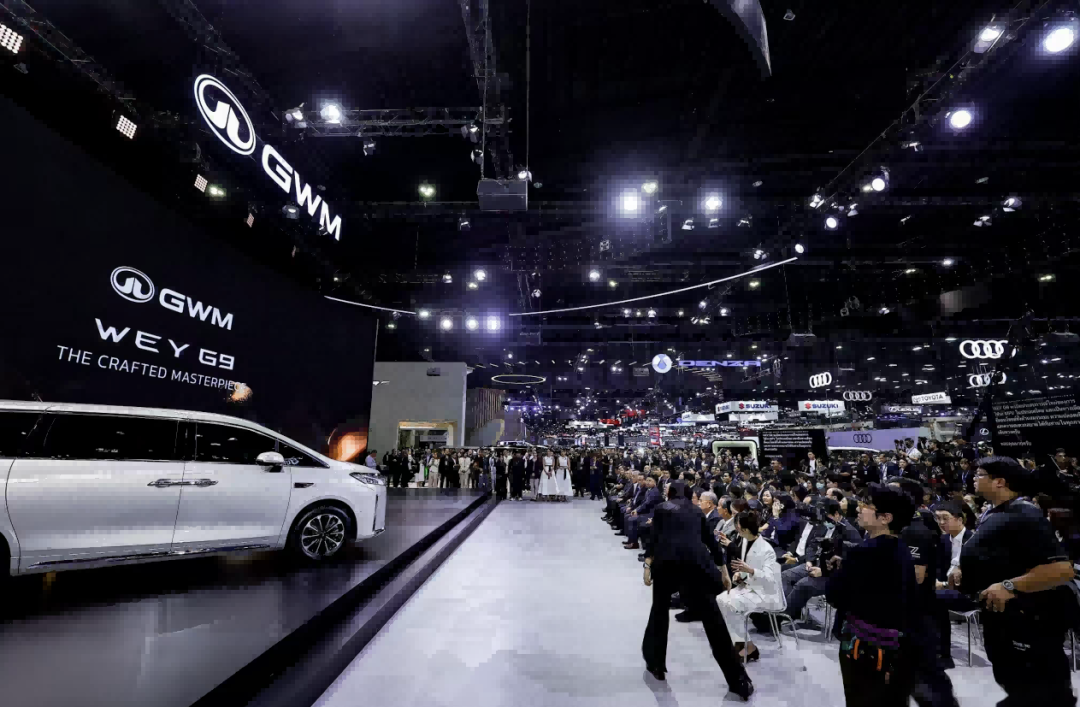
In 2024, BYD put into operation a plant with an annual capacity of 150,000 vehicles in Rayong, building production lines in a market where Japanese manufacturers had operated for many years. Toyota's pickups and gasoline hybrids have long-accumulated users, dealers, and repair networks. After Chinese automakers open factories locally, the contest has extended from prices in showrooms to who can build cars well, sell them for a long time, and make them affordable to repair.
In Latin American markets represented by Brazil, the approach is different again. Toyota sells Corolla Cross hybrids that support ethanol fuel locally, while BYD produces small pure electric vehicles in Camaçari and has showcased the Song Pro plug-in hybrid adapted to local ethanol fuel. Chinese brands bring plug-in hybrids abroad while also having to learn to use fuels familiar to local people.
Building factories deep in various overseas countries will directly change the time scale of competition between Chinese and Japanese automakers. A production line put into operation overseas must amortize costs through continuous orders for many years thereafter, and automakers and repair technicians will form a long-term symbiotic relationship, with the parts system similarly affected.
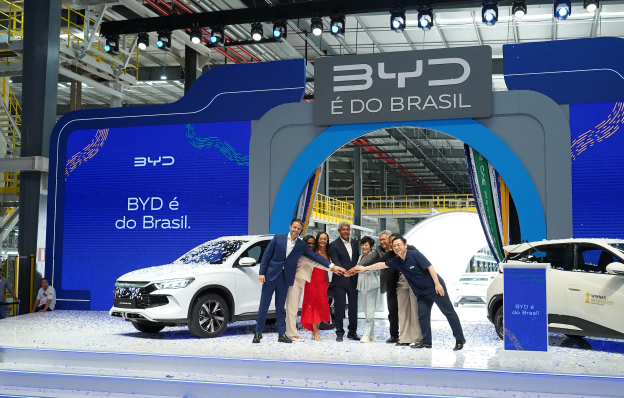
When Chinese companies make these arrangements, they are facing places where Japanese brands have operated the longest and where symbiotic relationships are the densest. The goal is to weaken or even break these symbiotic relationships.
Japanese automakers, guarding their existing channels, have also begun to use China's R&D and manufacturing capabilities to develop their next batch of global models, especially in the global new energy vehicle sector. This new change is already quite clear.
After Chinese and Japanese automakers decide the winner in the Chinese market, Chinese automakers will soon face this more difficult opponent in the global market, and the outcome may not be as clear as it was in the Chinese market.
Written at the end
In the past, Japanese brands came to China and shared in a market that started almost from zero and expanded rapidly, making huge profits in the world's largest auto incremental market.
Now, sales here have begun to shrink, but there are more and more Chinese companies that can build cars. For Japanese manufacturers, learning various new technologies and business methods in China and then taking them elsewhere is a rational choice.
But even after going to other markets, they will still face global competition from Chinese auto companies.
The contest between Chinese and Japanese automakers in the Chinese market has already been decided. In the next few years, competition in Bangkok, São Paulo, and Mexico City will become the second stage. In those places, Japanese automakers are far from being in the state they are in now in a corner of the Chinese market, almost rotting away.
-
Tesla Refutes 'Vehicle Recall and 2,800 Yuan Compensation' Rumor: It's a Scam, Do Not Click the Link
-
The Death of Digital Humans
-
![]()
In an Overlooked Corner of China's Auto Market, Japanese Cars Are Almost Rotting Away | Juchao
-
![]()
Smart Lighting Upgrade in Industrial Parks: Moving from Broad-Brush Control to Refined O&M
-
![]()
2026 iResearch · China AI Office Ranking
-
SAIC Audi's "Buy One, Get One Free" Promotion Under Investigation: After the Split, AUDI's Brand Awareness Challenge Remains Unresolved
-
NIO's Q4 Average Monthly Target of 40,000 Falls Short Out of the Gate, Ending 31-Month Growth Streak: Li Bin's Shortfall and the Test Ahead
-
![]()
Fujian's New Energy Heavy Truck Policy Takes Effect: Behind the 50.28% Penetration Rate, Hebei Chases Subsidies, Sichuan Chases Tolls, and Every Province Takes a Different Road