October Auto Sales Inventory: Four Carmakers Exceed 70% of Annual Targets
 11/19 2026
 362
Recently, data released by the China Passenger Car Association (CPCA) showed that in October 2026, wholesale volumes of passenger vehicle manufacturers nationwide reached 2.633 million units, down 10.2% year-on-year but up 3.3% month-on-month. With the market under broad pressure, the usual peak-season boost from the traditional "Golden September and Silver October" was muted, and performance across automakers diverged sharply, with competition among leading brands as intense as ever.
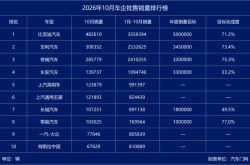
According to the CPCA's wholesale sales rankings, BYD Auto topped the list with 482,610 units in October; Geely Auto came second with 308,352 units; and Chery Auto followed close behind with 285,779 units for the month.
Changan Auto, SAIC Passenger Vehicle and SAIC-GM-Wuling all exceeded 120,000 units in October wholesale volume, ranking fourth through sixth respectively. Great Wall Motor and Leapmotor both held firm in the 100,000-unit tier in October. FAW-Volkswagen sold 77,046 units for the month, while Tesla China delivered 67,829 units, rounding out the top ten.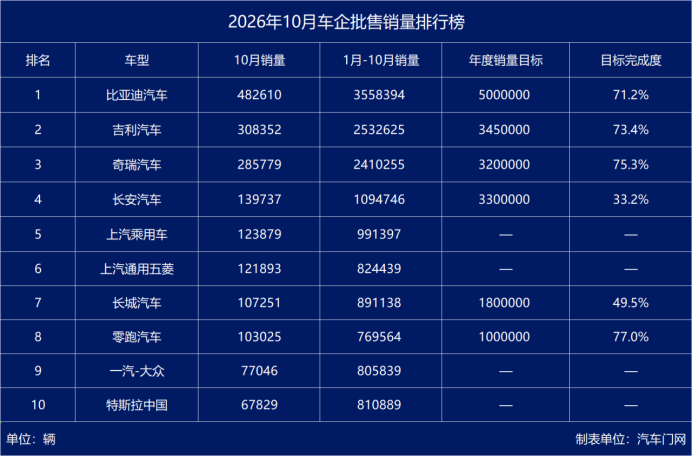
No. 1: BYD Auto — 482,610 units
BYD held firmly onto the top spot, with October sales reaching 482,610 units. By brand, the Dynasty and Ocean networks remained the company's main sales drivers, together accounting for more than 80% of October volume; Fangchengbao delivered steadily, staying above 40,000 units; Denza and Yangwang posted combined sales of 15,410 units for the period, down 17.1% from September.
In addition, the brand's exports doubled year-on-year to nearly 170,000 units, with overseas markets gradually becoming an important source of incremental growth for BYD. In the first ten months of 2026, BYD's cumulative sales reached 3,558,394 units, for an annual target completion rate of 71.2%. With the remaining two months marking the year-end sprint, its rich product lineup should keep it moving closer to the full-year target.
No. 2: Geely Auto — 308,352 units
Geely Auto ranked second with October sales of 308,352 units. By sub-brand, Geely Galaxy, Zeekr and Lynk & Co all performed well. Geely Galaxy's October sales rose 20% year-on-year to 153,385 units, making it the core sales pillar of Geely Auto. Zeekr's cumulative deliveries in the first ten months exceeded 320,000 units, completing its full-year target of 300,000 units ahead of schedule, while Lynk & Co also delivered solid results. Notably, Geely's new energy sales in October reached 214,996 units, surpassing the 200,000-unit mark for the first time.
In addition, the brand's overseas sales have exceeded 100,000 units for five consecutive months, with October exports at 107,153 units. From January to October this year, Geely Auto's cumulative sales reached 2,532,625 units, with the annual target completion rate already above 70%. With sufficient product and market momentum in the remaining two months, it should steadily advance toward its annual target.
No. 3: Chery Auto — 285,779 units
Chery Auto sold 285,779 units in October, ranking third. By sub-brand, the main Chery brand remained the sales mainstay, selling 200,600 units in October, while Jetour, iCAR, Exeed and Luxeed held firm in their respective market segments.
Chery's new energy performance was also outstanding, with 140,893 units sold for the month, up 27.7% year-on-year — the seventh consecutive month that Chery's monthly new energy sales exceeded 100,000 units. Overseas sales were strong as well, with Chery exporting more than 200,000 units in the same month, maintaining robust momentum in its overseas business.
Against its annual target of 3.2 million units, Chery sold a cumulative 2,410,255 units in the first 10 months of this year, for a completion rate of 75.3%. Entering the year-end sprint, driven by the dual growth engines of new energy and overseas markets, it is expected to continue steadily advancing toward its full-year target.
No. 4: Changan Auto — 139,737 units
Changan Auto ranked fourth with October sales of 139,737 units. Its various brands each played their part and shared the sales burden. Qiyuan shouldered the largest share, contributing about 60,000 units in October; Deepal performed steadily, selling 32,602 units for the month; and Avatr, though not yet at large-scale volume, continued to build its user base in the high-end segment.
In addition, Changan's new energy sales in October exceeded 140,000 units, and monthly overseas sales also crossed the 100,000-unit threshold. With both main lines moving upward simultaneously, this offset part of the brand's domestic sales fluctuations. From January to October this year, Changan Auto sold a cumulative 1,094,746 units, still short of its annual target of 3.3 million units. However, with new models to be launched and continued volume growth in overseas markets, overall growth space should open up further.
No. 5: SAIC Passenger Vehicle — 123,879 units
SAIC Passenger Vehicle sold 123,879 units in October, ranking fifth. By sub-brand, Roewe continued to gain volume in the family new energy market; MG kept pace with new energy products in the domestic market while relying on mature global channels for steady output; and IM Motors steadily deepened its presence in the high-end new energy segment, with each product line occupying a complementary position.
The brand's new energy growth momentum was also strong, with October new energy sales surging 157.6% year-on-year to become the core engine of brand sales growth. Leveraging MG's mature overseas footprint, overseas markets also contributed steady incremental volume, continuously lifting the brand's overall sales. In the first ten months of this year, SAIC Passenger Vehicle sold a cumulative 991,397 units, just shy of the one-million-unit mark. At the current pace, sales could rise to another level in the months ahead.
No. 6: SAIC-GM-Wuling — 121,893 units
SAIC-GM-Wuling ranked sixth, selling 121,893 units in October. By sub-brand, Wuling Red Label and Wuling Silver Label together supported the bulk of brand sales, delivering 35,001 units and 60,835 units respectively in October; Baojun performed steadily, selling 7,507 units for the month.
The brand's new energy performance was also impressive, with October sales of 99,958 units, accounting for more than 70% of the total. Affordable pure electric models such as the Hongguang MINIEV and Bingo continued to gain volume. At the same time, overseas markets maintained steady growth, with the brand achieving monthly exports of more than 30,000 units for seven consecutive months. From January to October this year, SAIC-GM-Wuling sold a cumulative 824,439 units. Leveraging the advantages of entry-level new energy products and continuously expanding overseas channels, and with the boost of the year-end car-buying peak season, overall sales still have ample room to move upward.
No. 7: Great Wall Motor — 107,251 units
Great Wall Motor sold 107,251 units in October, ranking seventh. By product line, Haval remained the sales mainstay, selling 71,027 units in a single month and supporting about 60% of the brand's total volume. Ora also performed impressively, with sales of 12,187 units for the month, more than doubling year-on-year; Wey and Great Wall Pickup also delivered steadily in their respective segments.
More noteworthy is that overseas markets and new energy are gradually becoming strong pillars of Great Wall Group's development at the current stage. In October, Great Wall's new energy deliveries were 49,499 units, up 7.25% year-on-year; during the same period, brand exports were 62,862 units, up 9.98% year-on-year. In the first ten months of this year, Great Wall Motor sold a cumulative 891,138 units, with an annual target completion rate approaching 50%. In the last two months of the year, with new product volume growth and overseas order deliveries, Great Wall still has room to catch up.
No. 8: Leapmotor — 103,025 units
Leapmotor sold 103,025 units in October, ranking eighth. By model, the C series remained the brand's main volume driver in the domestic market, the newly launched B series absorbed new demand, and there was no obvious sales gap in the A0 segment and mid-size SUVs.
Overseas markets also performed impressively. Leapmotor's cumulative exports in the first three quarters exceeded 150,000 units, already completing its established overseas export target ahead of schedule. From January to October this year, Leapmotor sold a cumulative 769,564 units, with an annual target completion rate approaching 77%. At present, the delivery rhythm of Leapmotor's main models is still rising. According to Zhu Jiangming, the team is confident about achieving the one-million-unit target, and there is still ample room for momentum in the months ahead.
No. 9: FAW-Volkswagen — 77,046 units
FAW-Volkswagen delivered 77,046 units in October, ranking ninth. By sub-brand, the Volkswagen brand remained the sales base, Audi continued to deepen the high-end market, and Jetta held the entry-level family market. At the same time, growth in the new energy segment was particularly prominent, with brand new energy sales of 14,900 units in October, surging 2,030.2% month-on-month.
Among them, the ID. AURA T6 launched in September delivered 12,032 units in October, taking the sales crown in the new energy mid-size SUV segment and becoming the core increment driving the brand's electrification transformation.
Relying on FAW Group's global channel layout, overseas markets also continued to contribute steady export increment, providing additional support for overall sales. In the first ten months of this year, FAW-Volkswagen sold a cumulative 805,839 units. With multiple new models continuing to launch and coordinated efforts across fuel and electric lines, there is still an opportunity to further unlock market potential at year-end.
No. 10: Tesla China — 67,829 units
Tesla China's wholesale sales were 67,829 units in October, holding tenth place on the list. Because Tesla prioritized supplying overseas markets with production capacity in the first month of the quarter, domestic deliveries fell accordingly. By model, Model Y domestic sales were only 7,807 units, a drop of 42,552 units from 50,359 units in September, with its ranking plunging from first to 66th.
Model 3 sales for the same period were even lower, at just 1,010 units. By contrast, the brand's overseas market growth was considerable, with October exports of 59,012 units, accounting for 87% of the brand's total for the month and setting a new high for the monthly export share since the Shanghai factory began production.
From January to October this year, Tesla China sold a cumulative 810,889 units. According to the brand's current production scheduling rhythm, production capacity in November and December will shift toward the domestic market. Coupled with the policy benefits of the year-end car-buying peak season, subsequent overall brand deliveries still have potential for release.
Final thoughts:
Overall, trends among top automakers have diverged significantly. Chinese self-owned brands have stronger overall momentum. BYD has held the leading position, and Geely, Chery, Changan and Leapmotor have all gained new increment in their respective advantageous tracks. In the joint venture camp, FAW-Volkswagen has secured its top ten position on the strength of its fuel-electric coordination.
The only wholly owned automaker, Tesla China, sent nearly 90% of its output overseas and likewise remained at the bottom of the list. As the year-end approaches, each company has entered the sprint stage for annual targets, and market competition in the next two months will become even more intense. (Images are from the internet; infringements will be deleted)
-
![]()
October Auto Sales Inventory: Four Carmakers Exceed 70% of Annual Targets
-
Li Shufu's "Relentless" Bet on the Methanol Market
-
Why Has AI Office Work Become the Competitive Focus for Industry Players?
-
![]()
Voyah Secures MIIT Batch 412 Production Access Qualification, Formally Bids Farewell to Operating Under Dongfeng's Umbrella
-
Tencent also cannot achieve the "impossible trinity": traditional business growth, AI business breakthroughs, and positive net cash flow
-
Anthropic Goes Public: A $1.4 Trillion Public Stress Test
-
![]()
Shenzhen: Letting the World Understand China
-
![]()
Survival Is Already Hard Enough—So Why Talk About "Brand Upward Mobility"?