Auto Braking Leader's Performance Keeps Rising, Spends Over 1.1 Billion Yuan on M&A
 11/19 2026
 552
Click "Short & Quick Interpretation" to follow us, and @ the editor for tips
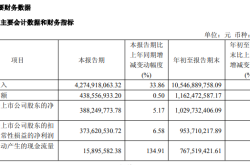
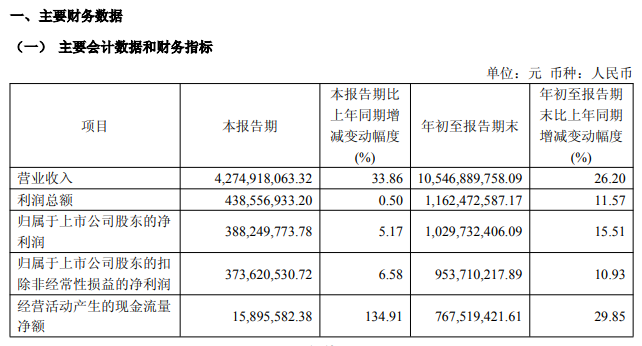
As a leader in the domestic automotive braking field, Bethel has shown relatively obvious performance growth in recent years and continued its growth trend in the first three quarters, achieving revenue and net profit attributable to parent company of 10.547 billion yuan and 1.03 billion yuan, up 26.2% and 15.51% year-on-year respectively.
Bethel places considerable emphasis on R&D investment, with cumulative investment exceeding 2.2 billion yuan over the past five years and an R&D team of nearly 1,900 people. This has given the company ample technical reserves and built a strong intellectual property moat, enabling it to meet many downstream customer needs and gain recognition, with customers covering leading domestic independent brands, new car-making forces, and international multinational automakers, among others.
Although performance growth is relatively obvious, the company needs to further improve its operating quality. In addition, the company's asset-liability ratio has risen somewhat in recent years, and interest expenses brought by the expanded scale of interest-bearing debt have also adversely affected profits, so reducing leverage needs to be put on the agenda.
Performance Keeps Rising, Over 1.1 Billion Yuan Spent on M&A
Performance continues to grow. From 2021 to 2025, Bethel's performance grew continuously, achieving revenue of 3.492 billion yuan, 5.539 billion yuan, 7.474 billion yuan, 9.937 billion yuan, and 12.014 billion yuan respectively, with a compound annual growth rate of about 36%; net profit attributable to parent company was 505 million yuan, 699 million yuan, 891 million yuan, 1.209 billion yuan, and 1.309 billion yuan respectively, with a compound annual growth rate of about 27%.
The growth momentum continued into 2026. In the first three quarters, revenue and net profit attributable to parent company were 10.547 billion yuan and 1.03 billion yuan respectively, up 26.2% and 15.51% year-on-year. The performance growth is closely related to the acquisition of Yubei Steering System (Xinxiang) Co., Ltd. (abbreviated as: Yubei Steering) and its consolidation into the financial statements.
Intelligent Electronic Control Revenue Overtakes. Bethel is committed to becoming a globally leading provider of intelligent chassis system solutions for automobiles. It has now built a business matrix covering automotive braking systems, automotive steering systems, automotive suspension systems, automotive intelligent driving systems, and lightweight components, with full-process capabilities from independent product R&D and matching verification to mass production and delivery.
Since its establishment in 2004, the company has continued to deepen its presence in the braking system field, which has the highest automotive safety requirements. After more than twenty years of sustained development, it has now built a full-series product and technology layout from mechanical braking and electronic parking brake systems (EPB) to brake-by-wire systems (WCBS) and electronic mechanical braking systems (EMB), among which mechanical braking and intelligent electronic control products are the core of revenue.
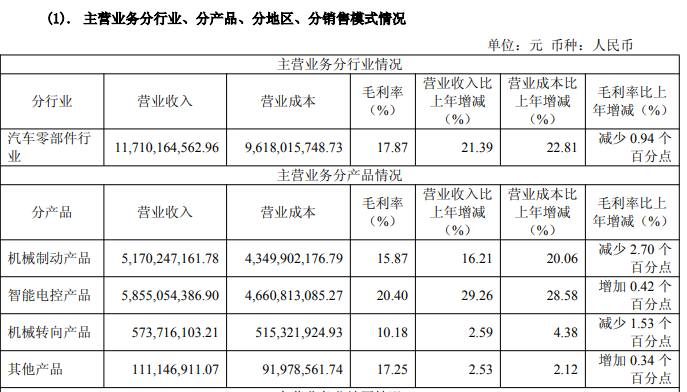
From 2023 to 2025, mechanical braking products achieved revenue of 3.368 billion yuan, 4.449 billion yuan, and 5.17 billion yuan respectively, up 26.55%, 32.11%, and 16.21% year-on-year; intelligent electronic control products achieved revenue of 3.296 billion yuan, 4.53 billion yuan, and 5.855 billion yuan respectively, up 38.81%, 37.44%, and 29.26% year-on-year.
It can be seen that revenue from intelligent electronic control products has surpassed that of mechanical braking products, with revenue shares of 48.73% and 43.03% respectively at the end of 2025. In addition, the gross margin of mechanical braking products declined relatively obviously, from 21.22% at the end of 2023 to 15.87% at the end of 2025, a cumulative decline of 5.35 percentage points, while the gross margin of intelligent electronic control products changed little overall, rising from 20.14% to 20.4%.
According to disclosures, the company has achieved multiple global and domestic firsts in the intelligent electronic control braking field, leading industry technological breakthroughs. It is the world's second and China's first independent brand enterprise to achieve mass production of electronic parking brake systems (EPB); it is the first Chinese independent brand enterprise to release and mass-produce One-Box brake-by-wire systems (WCBS).
In addition, the company is also actively laying out the next-generation technology of brake-by-wire—electronic mechanical braking systems (EMB). At present, the EMB production line has completed debugging and has obtained designated points for multiple mass production projects. In March 2026, it achieved the first small-batch delivery of EMB products.
Frost & Sullivan data shows that in 2025, Bethel's market shares (by revenue) in electronic parking brake systems (EPB) and brake-by-wire systems (WCBS) were 14.2% and 8.6% respectively, both ranking first among Chinese brand suppliers. If foreign giants are included in the statistics, Bethel ranked second in the overall brake-by-wire market in 2025, second only to Bosch, showing that its market position is quite solid.
Over 1.1 Billion Yuan Spent on M&A. In addition to intelligent electronic control and mechanical braking businesses, Bethel also focuses on the mechanical steering business and further increased its investment in this business during the year. In February this year, the company announced it would acquire 50.9727% of Yubei Steering's shares. At that time, the company was valued at no more than 2.2 billion yuan, and the corresponding transaction price for the acquisition was no more than 1.121 billion yuan. The final transaction consideration was 1.1214 billion yuan, and the equity delivery was completed in June.
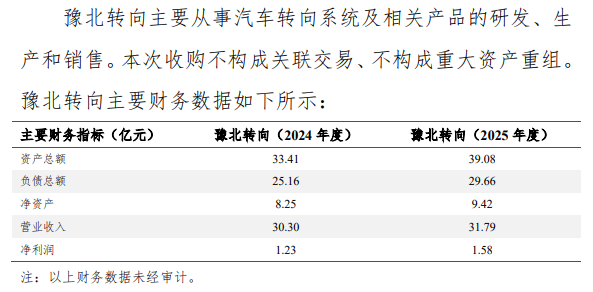
According to the valuation report, in 2024 and 2025, Yubei Steering achieved revenue of 3.03 billion yuan and 3.179 billion yuan respectively, and net profit of 123 million yuan and 158 million yuan respectively. Last year, revenue and net profit growth rates were 4.92% and 28.46% respectively.
According to disclosures, Yubei Steering is a tier-one automotive parts supplier specializing in the R&D and production of automotive steering system products, and has good operating efficiency, a high-quality customer base, and solid technical foundations. Its main products include electric power steering systems, hydraulic power steering systems, and steering system components, which can form significant synergies with the company's existing automotive steering products in terms of technology, market, and scale.
Bethel stated that this acquisition, on the one hand, will integrate the two parties' technical and resource advantages, enrich and improve the company's product line in the automotive safety systems field, and enhance the company's customer service capabilities and long-term market competitive advantages; on the other hand, this acquisition has good economic benefits and will further enhance the company's profitability.
Fruitful R&D Achievements, Rising Leverage Ratio
Five-Year R&D Investment Exceeds 2.2 Billion Yuan. From 2021 to 2025, Bethel's R&D expenses were 239 million yuan, 378 million yuan, 450 million yuan, 576 million yuan, and 605 million yuan respectively, with total investment exceeding 2.2 billion yuan over five years. The R&D expense ratio generally showed a downward trend, at 6.85%, 6.83%, 6.02%, 5.79%, and 5.04% respectively.
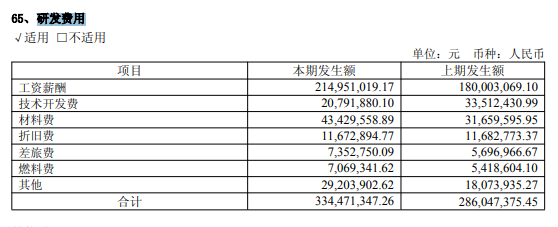
Entering 2026, the company continued to strengthen R&D investment. In the first three quarters, R&D expenses were 565 million yuan, a significant year-on-year increase of 27.2%, and the R&D expense ratio rose to 5.36%. Salaries and compensation are a major expenditure, with the interim report amount and proportion at 215 million yuan and 64.27% respectively. As of the end of the first half of 2026, the number of R&D personnel was nearly 1,900.
The interim report shows that the company has set up 9 R&D centers in core automotive industry cluster areas such as Wuhu, Shanghai, Hangzhou, Suzhou, Xi'an, Hefei, Xinxiang, Detroit in the United States, and Frankfurt in Germany. It possesses cutting-edge technologies and independent intellectual property rights for a full series of products, and has full life-cycle management capabilities from independent product R&D and matching verification to mass production.
Another side of the large R&D team is that the company's intellectual property layout has achieved remarkable results. It has cumulatively obtained 468 domestic authorized patents, including 125 invention patents, 335 utility model patents, and 8 design patents; and 11 international PCT authorized patents. In addition, the acquired Yubei Steering has cumulatively obtained 333 domestic authorized patents, including 49 invention patents, 278 utility model patents, and 6 design patents.
According to disclosures, the company's technical reserves have achieved full-generational coverage from mechanical to electronic control and then to brake-by-wire, and it has taken the lead in completing the leap from technical reserves to mass production in the next-generation electronic mechanical braking (EMB) field, while also proactively laying out steer-by-wire technology. In the suspension system field, relying on profound software algorithm accumulation, the company has successfully developed electronic damper control systems (EDC) and dual-chamber air suspension systems, and is actively tackling cutting-edge technologies such as fully active suspension, aiming to promote the process of chassis integration through deeply integrated control of braking, steering, and suspension.
It should be pointed out that Bethel's innovation capability has gained recognition at multiple levels. The company is a national intellectual property demonstration enterprise and a technological innovation demonstration enterprise in Anhui Province. It has relevant R&D field recognitions such as the Anhui Provincial Automotive Safety System Engineering Technology Research Center, the Anhui Provincial Advanced Driver Assistance System Engineering Research Center, the Wuhu Key R&D Platform, and the Zhejiang Provincial Key Research Institute.
Operating Quality and Leverage Ratio Deserve Attention. Although performance has maintained growth continuously, Bethel's operating quality still needs further improvement. From 2021 to 2025, operating cash flow fluctuated greatly, at 433 million yuan, 785 million yuan, 678 million yuan, 1.058 billion yuan, and 867 million yuan respectively, and the cash content of net profit was 85.85%, 112.27%, 76.09%, 87.5%, and 66.21% respectively.
In the first three quarters of 2026, operating cash flow was 768 million yuan, up 29.85% year-on-year, and the cash content of net profit was 74.54%, still a considerable gap from the standard value of 100%.
In addition, the company's leverage ratio also needs to be further reduced. From the end of 2021 to the end of 2025, the asset-liability ratios were 44.09%, 47.17%, 43.67%, 45.72%, and 51.29% respectively, and further rose to 55.71% in the first three quarters of 2026.
As of the end of the third quarter, monetary funds and trading financial assets were 2.408 billion yuan and 3.132 billion yuan respectively, while short-term borrowings and long-term borrowings were 510 million yuan and 942 million yuan respectively, up significantly by 473.24% and 1522.39% year-on-year, and there were also 2.636 billion yuan in bonds payable. The scale of interest-bearing debt is not low, which also led to a sharp rise in interest expenses, reaching 63.188 million yuan, a significant year-on-year increase of 236.16%, far exceeding the 35.7051 million yuan in 2025, adversely affecting profits.
Stock Price Fluctuates Greatly, Chairman Proposes Repurchase. In the secondary market, Bethel's stock price fluctuates greatly, rising tortuously from a low of 14.76 yuan/share on August 2024 (pre-adjusted, same below) to a high of 31.72 yuan/share in March 2025, after which the stock price generally showed a downward trend. The closing price on November 19 was 18.36 yuan/share, a decline of more than 40% from the high, with a total market value of 23.37 billion yuan and a TTM price-earnings ratio of 16.15 times.
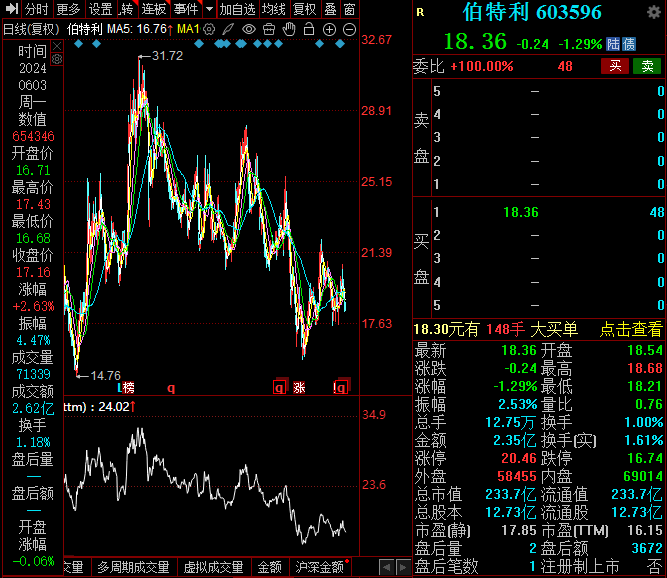
In order to stabilize the stock price and enhance investor confidence, Chairman and General Manager Yuan Yongbin proposed a repurchase on August 3, with a repurchase amount of 100 million yuan to 200 million yuan, and the repurchased shares to be used for employee stock ownership plans or equity incentives. As of October 31, the company had cumulatively repurchased 3.711668 million shares, with the highest and lowest transaction prices at 27.39 yuan/share and 26.33 yuan/share respectively, and the total repurchase amount was 100.1109 million yuan (excluding transaction fees), meaning it had already reached the lower limit of the repurchase.
(Short & Quick Interpretation - original work, please do not reprint without permission! PS: If the manuscript infringes rights or the data is incorrect, please contact us promptly for correction)

-
![]()
Consumers Have Fallen Out of Love with Tesla—So Why Are Automakers Still Copying Its Homework?
-
![]()
Auto Braking Leader's Performance Keeps Rising, Spends Over 1.1 Billion Yuan on M&A
-
Two-Wheel Drive Plus LiDAR: GAC Trumpchi Yue 7 Smart Driving Edition Lowers the Bar Again—How Many Extra Sales Can It Deliver?
-
Li Yanhong and Baidu May Finally Be About to Catch the "Last Train" of AI
-
![]()
Tencent First, ByteDance Second
-
![]()
Tencent and ByteDance's B2B Battle
-
ZTE's bond issuance to "supplement working capital" behind the scenes: total liabilities hit a record high of 168.5 billion yuan
-
WorkBuddy Tops 10 Million DAU: Office Agents Are No Longer Priced by the Seat