Zhipu and MiniMax: Cutting Sales Costs While Boosting Performance
 09/15 2026
 516
The role of sales is gradually evolving from pre-sales activities to mid-sales and after-sales support. OKRs (Objectives and Key Results) are shifting from a focus on user volume to customer retention. In this new paradigm, the model itself serves as the ultimate salesperson, with human efforts seemingly dedicated to serving the customers attracted by the model.
The financial reports for the first half of 2026 unveiled a remarkable trend: both Zhipu and MiniMax experienced more than a doubling in revenues, while their sales expenses simultaneously decreased.
Zhipu's revenue soared to RMB 954 million, marking a year-on-year increase of 399.7%. However, its sales and marketing expenses decreased by 14.8% year-on-year, amounting to RMB 178 million.
MiniMax also delivered a stellar performance. Its revenue reached RMB 786 million, a year-on-year surge of 283.1%. Meanwhile, its sales and distribution expenses dropped by 17.9% year-on-year to RMB 181 million.
The combination of exploding revenues and declining sales expenses—a scenario unattainable in traditional industries or the SaaS sector—signals a transformation in the growth engine of large model companies.
Part. 01 From "Human-Driven Model Promotion" to "Self-Sustaining Model Sales"
The reduction in sales expenses is not a result of mere cost-cutting but a fundamental shift in growth strategy.
Zhipu's confidence in trimming sales expenses stems from changes in its platform's customer acquisition methods.
In the first half of the previous year, Zhipu's primary revenue source was the localized deployment of enterprise-level general-purpose large models. This involved packaging and selling models into customer data centers, with deal sizes ranging from millions to tens of millions. Revenue recognition depended on delivery and acceptance, and repeat purchases hinged on relationship maintenance. Such business naturally necessitated a sizable sales team to pursue projects and cultivate relationships.
However, in the first half of this year, open platform and API revenue skyrocketed from RMB 29.1 million in the same period last year to RMB 825 million, accounting for 86.5% of total revenue. Customers no longer relied on salespeople for pitches; instead, they directly recharged on the platform based on Token usage.
With the transaction method transformed, the role of sales naturally diminished. Zhipu's statement in its financial report was candid: "Revenue has transitioned from one-time confirmation to ongoing generation, and the company now boasts predictable recurring revenue for the first time."
Zhipu's post-financial report actions further confirmed this trend: On September 2, Zhipu officially launched an official flagship store on Tmall, offering GLM Coding Plan subscription packages. Personal versions were priced at RMB 118/month for Lite, RMB 538/month for Pro, and RMB 1,078/month for Max.
Selling large model packages on an e-commerce platform was unthinkable in the traditional software era, but it is now a reality. The customer acquisition cost for models is approaching the standard customer acquisition cost in e-commerce.
MiniMax follows a similar logic but takes a distinct path. Early on, MiniMax gained recognition for its consumer-facing products like Conch AI and Xingye, often being labeled as a "consumer-focused company."
However, in the first half of this year, its open platform and enterprise service revenue surged by 703.1% year-on-year to RMB 497 million, accounting for 63.4% of total revenue. This surpassed AI-native products (RMB 287 million) for the first time, becoming the largest revenue source.
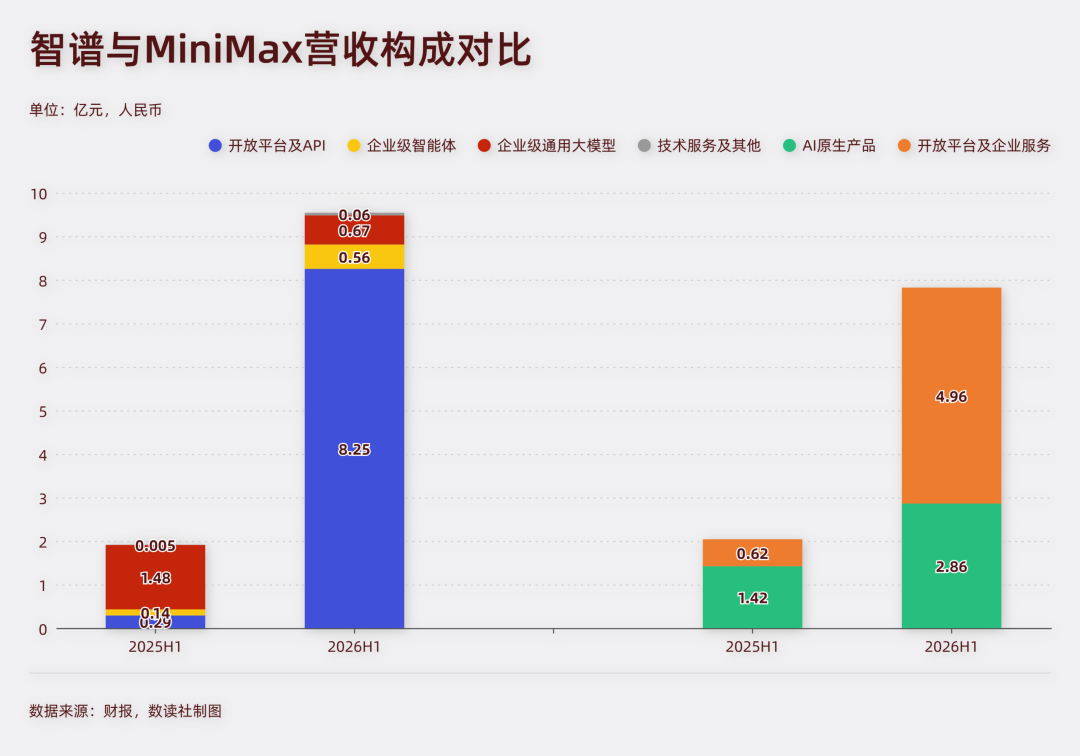
MiniMax's user growth is primarily driven by product strength and word-of-mouth, rather than paid traffic or ground promotion. Developers and enterprises are autonomously attracted by the model's capabilities. Its enterprise customers and developers have exceeded 2 million, a tenfold increase from the end of 2025. Token consumption in July reached 20 times that of January, and ARR (Annual Recurring Revenue) in August surpassed USD 800 million.
During the earnings call, MiniMax disclosed that its To B business currently accounts for about 80% of ARR, with To C accounting for about 20%. A year ago, the revenue structure was still primarily consumer-focused, but now B2B has become the absolute mainstay. The speed of this structural adjustment could not have been achieved solely through sales-driven efforts.
When a model's capabilities are sufficiently robust and inference costs are low enough, developers and enterprise customers will migrate on their own—not because a salesperson called, but because not using this model would mean falling behind in competitiveness. This "natural growth driven by product capabilities" is fundamentally rewriting the sales expense structure of AI companies.
However, the simultaneous optimization of sales expenses by both companies can also be interpreted as an active strategic choice: shifting resources from high-investment, low-marginal-utility ground promotion to model R&D and infrastructure upgrades.
This represents both an "improvement in technical capabilities" and a "strategic shift in focus and cost structure optimization," with neither being unidirectional. The decline in sales expenses is not merely a natural consequence of "sufficient capabilities eliminating the need for promotion" but also a deliberate decision by management to "allocate resources to more efficient areas" under limited resource constraints.
Part. 02 "Deep Conversion" and "Service Gaps"
While sales expenses can be cut simultaneously, the underlying business models differ.
86.5% of Zhipu's revenue comes from open platforms and APIs. The advantage of the API business lies in self-service top-ups, pay-as-you-go, and recurring revenue. However, its disadvantages are equally apparent: customer migration costs vary, necessitating efforts to drive users toward deep usage conversion.
Developers and small-to-medium enterprises using shallow API calls can indeed switch models by altering a few lines of code. These customers are the most price-sensitive and eager to try new models, with almost no loyalty. Once competitors launch products with comparable performance but lower prices, this portion of revenue could quickly erode.
However, the situation is entirely different for enterprise customers deeply embedding AI into their core production processes.
According to a Zapier survey in 2026, only 42% of enterprises attempting to switch AI vendors reported a smooth process, while the remaining 58% encountered failures or costs far exceeding expectations.
The reason lies in the fact that AI systems involve vendor-specific APIs, private training data, custom deployment tools, and deep workflow integration—elements that cannot be seamlessly migrated across vendors.
In other words, while the switching cost for API calls is indeed low, once enterprise customers deeply embed a model into their core business, a de facto "technical lock-in" occurs.
This lock-in effect partially offsets the risk of "zero switching costs," making customer stickiness stronger than imagined and adding some rationality to the move of "compressing sales."
Zhipu's API customers exhibit a "bifurcation": shallow customers have extremely low switching costs and may churn with any price or performance fluctuations. Deep customers, however, form strong technical lock-in due to private training data, custom deployments, and workflow integration.
Zhipu's MaaS open platform saw Token usage surge over 40-fold from the beginning of the year, with paid daily active users growing by 603%, and daily usage by the top ten customers increasing 98-fold. These figures confirm the trend of deep binding, with top customers embedding Zhipu's models into their core businesses.
The real test lies in whether Zhipu can drive deeper customer conversion at a lower cost after "optimizing high-cost promotion."
Deep usage customers require API stability guarantees, fine-tuning support, industry solution references, and community ecosystem feedback. These capabilities were partially reliant on sales teams for coordination in the past but will now need more efficient self-service tools, better technical documentation, and a more active developer community to deliver.
Zhipu's potential risk lies in whether its functional transformation can keep pace with customers' shift from "shallow trials" to "deep binding." If the transformation lags, the stickiness advantage of deep customers may not materialize before price-sensitive churn among shallow customers occurs.
MiniMax's revenue structure shifted from consumer-focused to enterprise-focused, with expenses declining due to natural user growth—a noteworthy structural change.
Where did the money saved from sales expenses go?
If low-efficiency ground promotion and brand advertising were cut while resources were redirected to customer success, solution architects, and post-sales technical support teams, this would represent a precise reallocation—matching lower customer acquisition costs with higher customer service density.
However, if the expense decline reflects an overall contraction, focusing solely on natural user growth while neglecting post-sales capabilities, problems will accumulate: B2B enterprise customers, especially large overseas clients, need more than just "a good model"—they require SLA (Service Level Agreement) commitments, security audits, customized fine-tuning, and dedicated response. These services are not inherently attached to API interfaces and require human delivery.
Among MiniMax's 2 million global enterprise customers and developers, the number of top clients requiring hands-on service may be limited, but as B2B revenue continues to rise, both the absolute number and service depth of top clients are increasing. Sales can be cut, but delivery and service capabilities cannot be; otherwise, the higher the revenue, the faster renewal risks accumulate.
The real risk is not "sales compression" but whether "unnecessary sales expenses or essential customer success capabilities" were cut. This depends on management details beyond financial reports, which public information cannot currently confirm.
Part. 03 The Model Is the Salesperson—But Sales Extend Beyond the Model
The competition among large models has shifted from "selling software" to "selling intelligence."
Traditional software companies typically have sales expense ratios of 20%-40%, requiring sales teams to convince customers "why you need this software."
However, the logic for large models differs: customers do not adopt them because they are persuaded but because not doing so would leave them lagging in competition. When a model's intelligence level is sufficiently high, the decision cost of adopting it approaches zero, and the value of sales naturally diminishes.
This explains why both companies could simultaneously reduce sales expenses while revenue surged. It also explains why their R&D expenses remain more than ten times higher than sales expenses. Zhipu's R&D spending was RMB 2.131 billion, 12 times its sales expenses (RMB 178 million), while MiniMax's R&D spending was RMB 2 billion, 11 times its sales expenses (RMB 181 million).
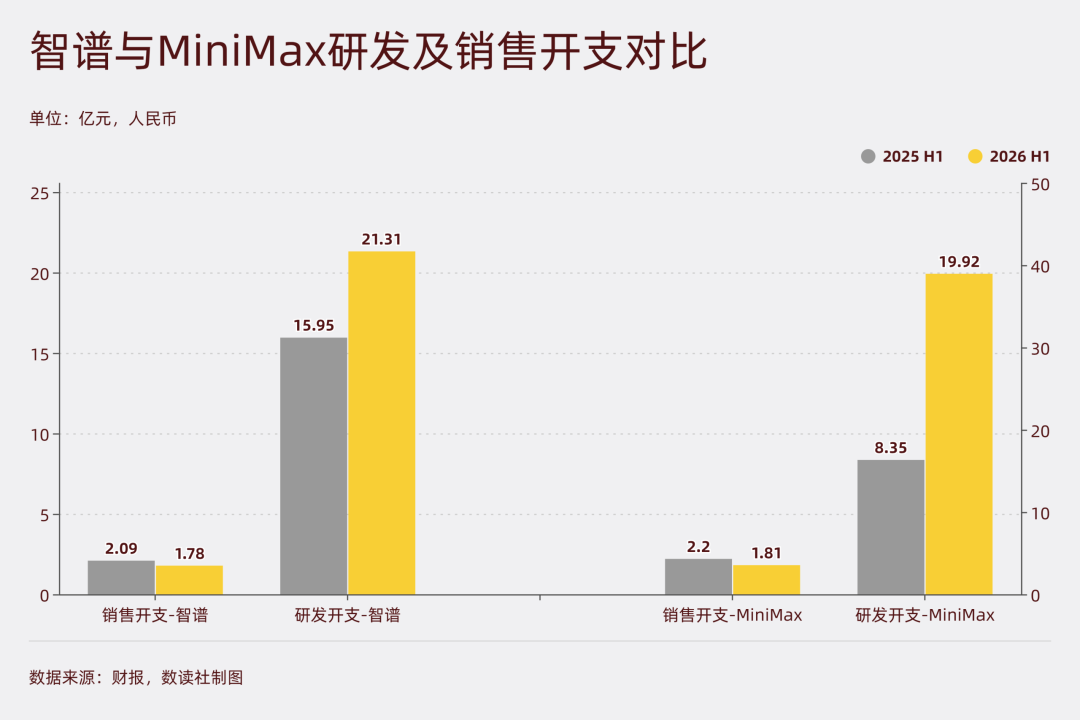
The core asset of large model companies is not the sales team but the model itself. Whoever can push the model to a better experience level in less time can acquire more customers at a lower acquisition cost. The decline in sales expenses is both a natural result of improved model capabilities and a strategic choice by management to tilt resources toward R&D.
Large models no longer require sales in the traditional sense. Or rather, they no longer require conventional salespeople. When customers shift from "whether to use AI" to "how to maximize AI value," the sales role transitions from "persuading customers to sign" to "helping customers succeed"—more akin to a hybrid of engineers, consultants, and salespeople.
This means the function of sales is gradually shifting from pre-sales activities to mid-sales and after-sales support. OKRs are shifting from a focus on user volume to user retention. The model itself serves as the ultimate salesperson, with human efforts seemingly dedicated to serving the customers attracted by the model.
-
After GAC Group Propels Toyota’s EVs to Success for 10 Months, FAW Finally Gives In
-
The ‘Six Little Dragons’ Halo Fades Quickly for Qunhe Post-IPO
-
![]()
Zhipu and MiniMax: Cutting Sales Costs While Boosting Performance
-
![]()
Consolidation in China’s Auto Industry Kicks Off with the Integration of North and South Toyota
-
Next-Gen Snapdragon Flagship Platform on the Horizon: Can AI Agent Smartphones Truly Deliver?
-
GAC and FAW 'Marriage': The Era of 'Major Integration' in the Auto Industry Has Just Begun
-
800 Million Yuan Acquisition of Wuluo Intelligence: Can Xiangshan Share Make a Breakthrough?
-
![]()
Is It Harder for Automakers to Profit as Car Sales Increase?