One Firefly Outshines a Flock of Smarts
 10/30 2026
 493
Introduction
Introduction
Under the electrification wave, premium pure electric small cars are a dying breed.
In this year's passenger vehicle market, decline is no longer news. Sales are down more than 5 million units year-on-year, and annual retail sales returning to levels from a decade ago is a foregone conclusion.
Even so, two segments are still growing.
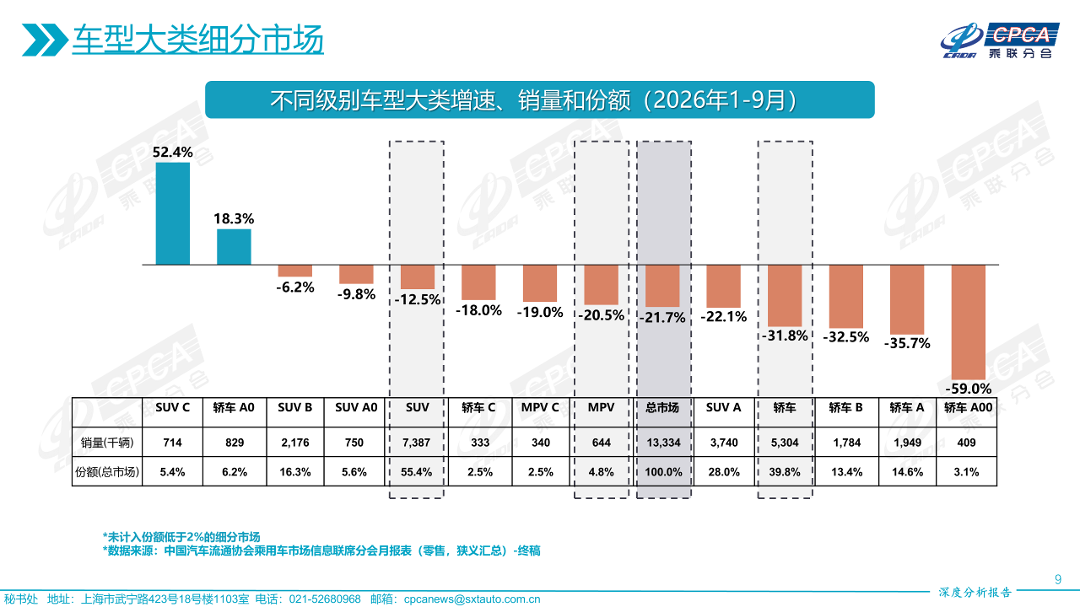
Retail data for January to September released by the China Passenger Car Association shows that C-class SUV retail sales reached 714,000 units, a 5.4% share, up 52.4% year-on-year. The other is A0-class sedans, with retail sales of 829,000 units, a 6.2% share, up 18% year-on-year.
Interestingly, although both are growth tracks, the two markets look completely different.
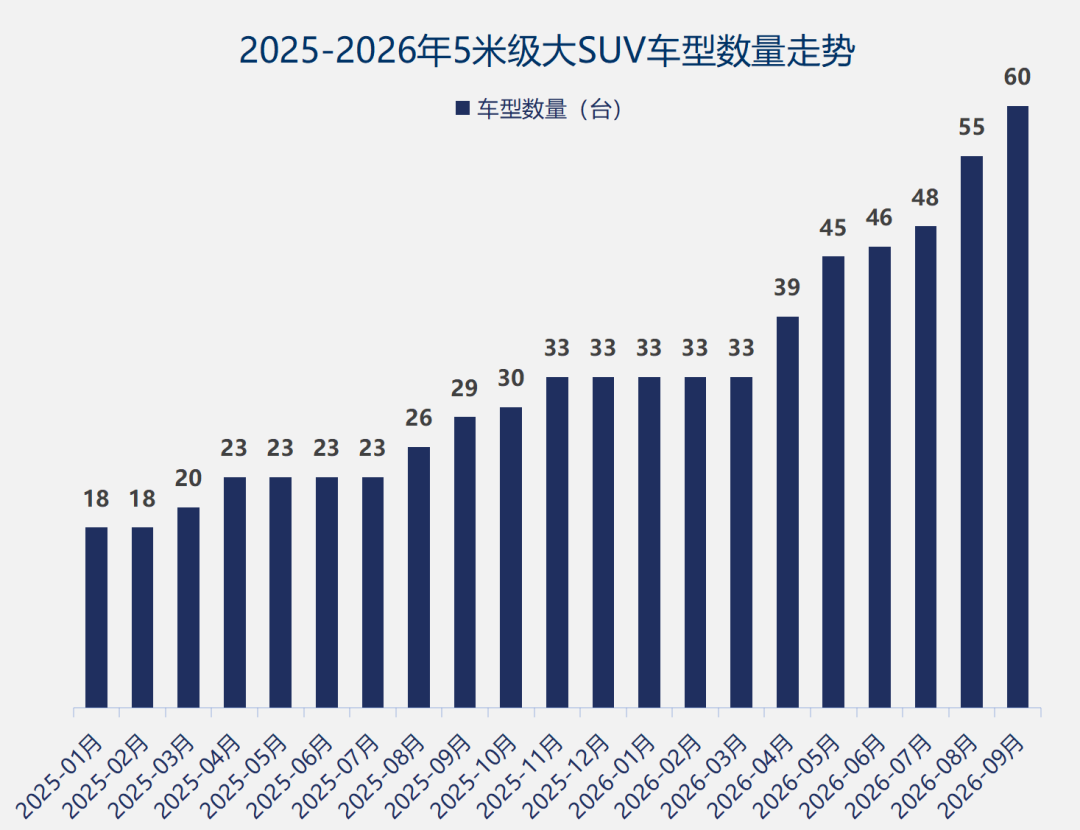
In the C-class large SUV segment, models are packed shoulder to shoulder, with roughly 60-plus products already duking it out on the same stage. Within limited capacity, each model gets a smaller and smaller slice of the pie, while more contenders are still lining up to launch.
By contrast, in A0-class sedans, many models routinely sell 30,000-40,000 units a month. Sales look huge, yet there are not many players in the segment. A high-volume market is instead ignored by many companies.
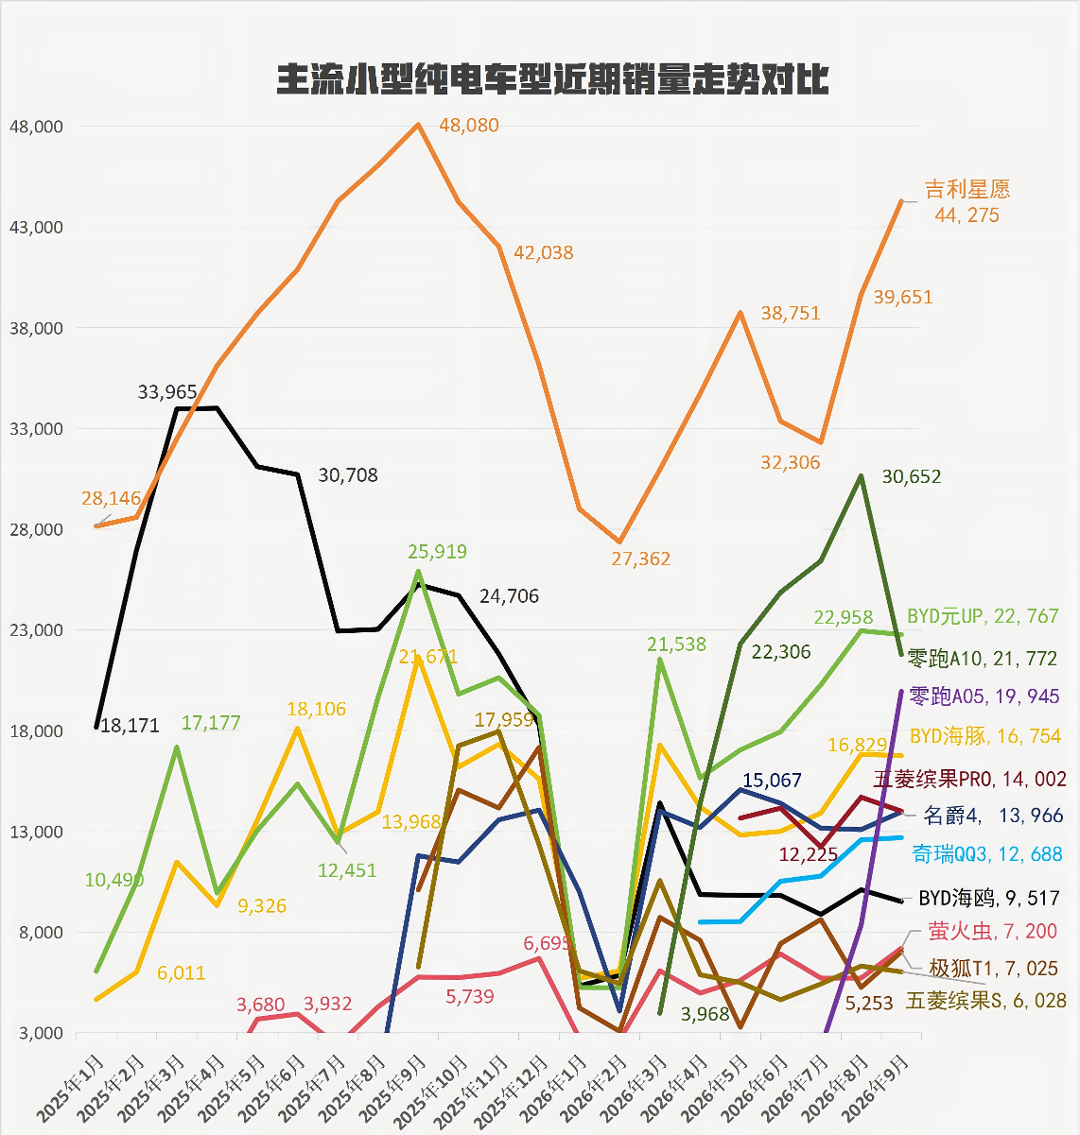
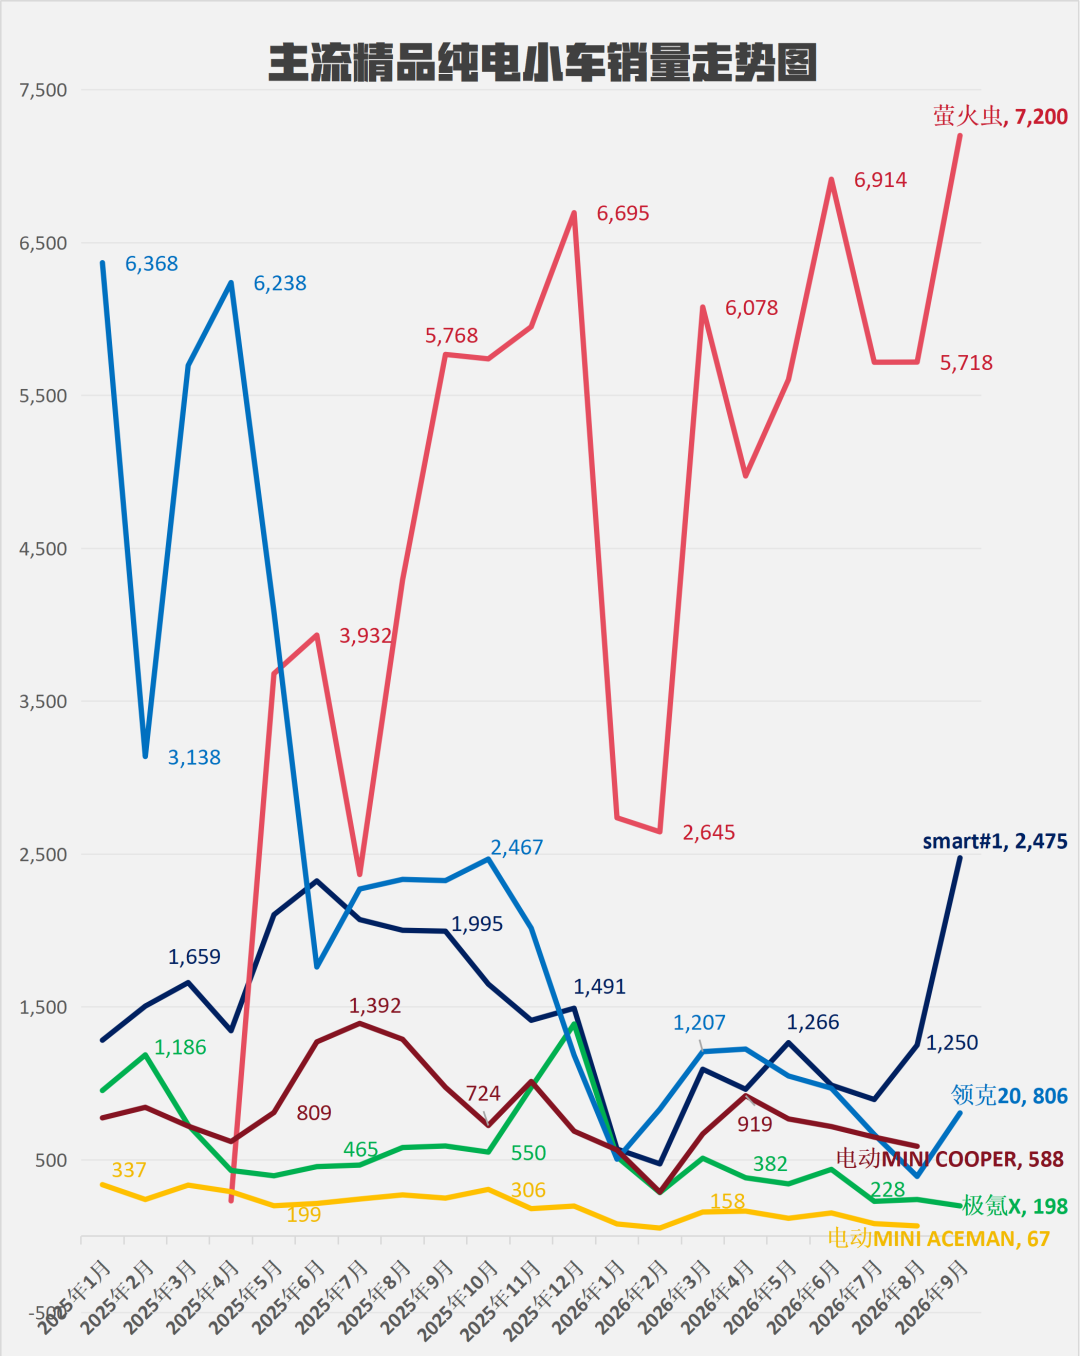
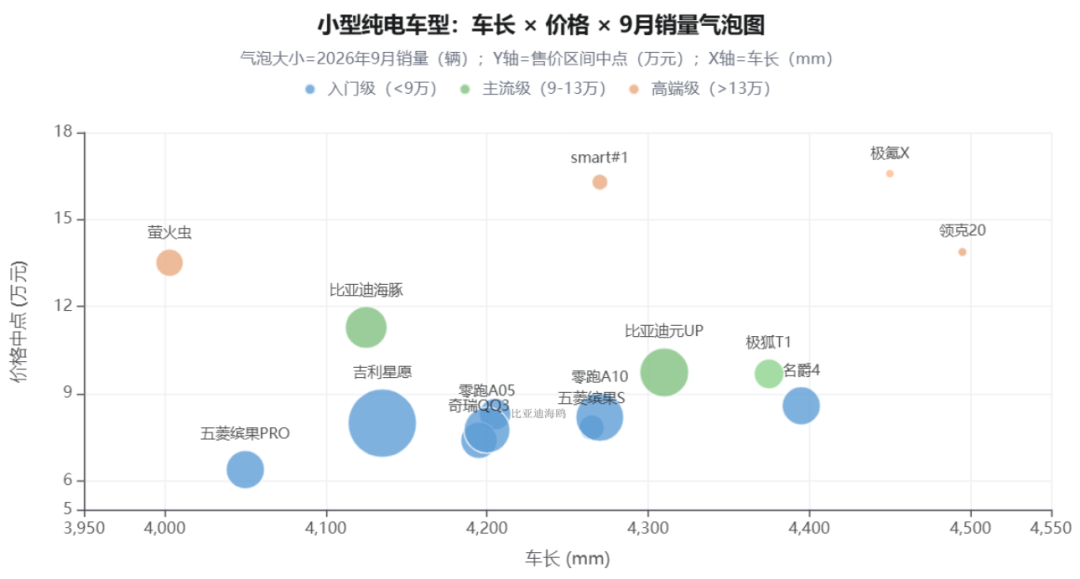
According to statistics, models that can become hits (monthly sales of 5,000+) number only about a dozen: Geely Xingyuan, BYD Yuan UP, BYD Dolphin, Wuling Bingo, Chery QQ3, Leapmotor A05, BYD Seagull, MG4, NIO Firefly, Arcfox T1 and others are all on the list.
Look closely at the price bands, and the gap immediately widens. The vast majority of models on the list are priced in the 60,000-90,000 yuan range, with only Firefly officially priced at 120,000-150,000 yuan.
Look further down, and the Smart #1, regarded as a standard-bearer for premium pure electric small cars, sold only more than 2,400 units in September—already its best result in recent years after its annual model update and price cut.
Other players focused on the premium small car route are faring even worse.
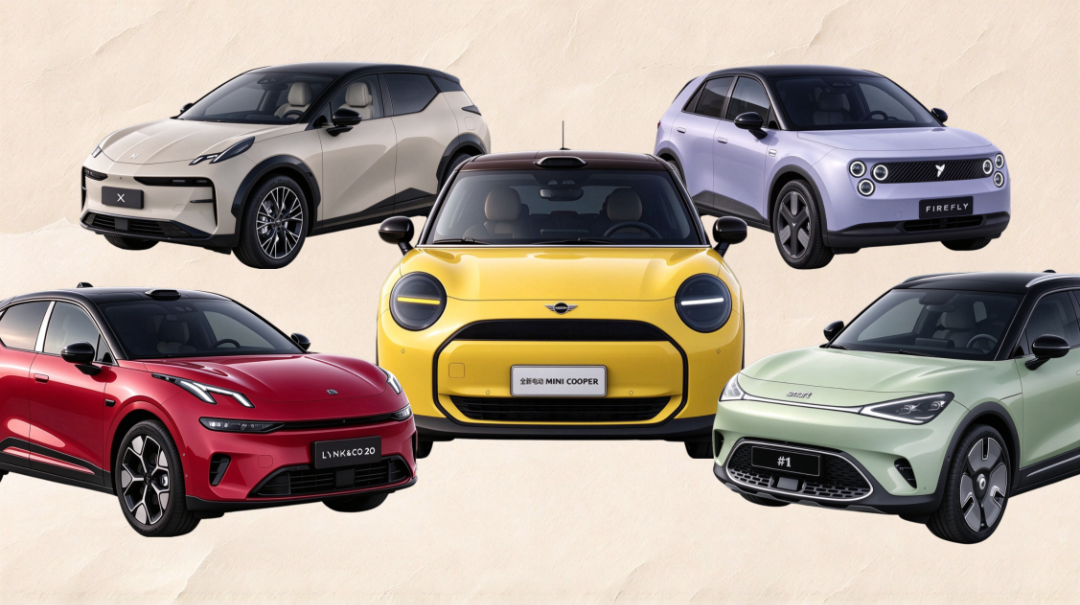
MINI monthly sales are already below 1,000 units, the Audi Q2L electric version was discontinued early, and Volvo EX30 monthly sales are even only in double digits; Zeekr X, which also follows the premium small car route, has likewise never ranked high in sales. In addition, Lynk & Co 20 had some sales in the early launch period, then went quiet for a time. After the facelift and price cut, its value for money improved, and there may be some room for imagination going forward.
In other words, on the premium electric small car track, apart from Firefly, the other players have basically all failed.
Why can a bunch of Smarts combined still not beat Firefly? You should know that when Firefly first came out, many people criticized its appearance, and the battery swapping promoted earlier has still not materialized. So why has it broken through?
With this question in mind, we sorted through the competitive landscape of the pure electric small car market. The purpose is not to boast about how right Firefly has been, but to use this industry and market phenomenon to truly explore whether this path of premium pure electric small cars is still necessary at all.
01 Cars are getting bigger, and small cars are bound to be cheap
Now the entire industry is racing toward bigger cars. As mentioned earlier, C-class SUVs are the fastest-growing track, but this growth is entirely built by piling up model after model. According to statistics, over the past year, more than 30 C-class SUV models have been added. With so many new cars entering the market, sales would not fail to grow.
With more and more big cars and increasingly intense price competition, small cars have invisibly been squeezed into the sub-100,000 yuan price band and are finding it even harder to turn things around.
Why are automakers all willing to build big cars, even if they have to squeeze in and even if the probability of success is extremely low, they still take the risk? By contrast, making a small car, as long as the price is right, can basically sell explosively, yet automakers are unwilling to enter?
From the perspective of automakers, it is not that they do not want to make premium small cars, but that the market landscape, competitive pressure, and the characteristic that "building small cars is much harder than building big cars" determine the outcome.
Big cars have high unit prices and thick margins, so no matter how fierce the competition, from 150,000 to 500,000 yuan, every company is willing to crowd into the big car track.
Small cars are different. They look small in size, but parts and whole-vehicle validation are just as numerous; what is saved is only a bit of material. Therefore, the output value of small cars is inherently relatively low. Take an entry-level small car with monthly sales of over 10,000 units as an example. The output value others generate by grinding out more than 10,000 units a month is equivalent to me selling only 2,000 big cars priced at more than 300,000 yuan each. The two are not on the same order of difficulty.
This also means that building small cars must rely on huge scale to amortize costs. Only top large manufacturers such as BYD, Geely, Wuling and Leapmotor have the confidence to lay out in this area. Even for top brands, the profits of small cars are pitifully thin, and the break-even line often runs to the range of 20,000 units.
Even for new forces, it is almost very difficult to touch this track. The sales volume cannot support it, making small cars is not profitable, it is detrimental to the company's development, and it is even less helpful for brand improvement. It is also very difficult for a company to make a cheap small car to lower its brand value and recognition.
In fact, luxury brands including BBA are also gradually cutting ties with entry-level small cars. Although entry-level small cars can expand a brand's customer base and awareness, given the diluted and lowered brand value, exchanging that cost for sales of tens of thousands of small cars is not a good deal no matter how you look at it.
On the consumer side, this contrast is even more realistic. There is a very realistic consumer logic here: with a budget of 150,000 yuan, you can absolutely get a mid-size SUV with advanced intelligent driving, and a family can travel with ease. Under this premise, asking consumers to spend 120,000-130,000 yuan on a small car that most of the time is driven by only 1-2 people, many people's first reaction is that it is not worth it.
In a perception where the entire market is seeking bigger, premium small cars are fundamentally trapped in an extremely narrow niche market.
Therefore, the volume-driving A0-class small cars on the market are basically concentrated in the 50,000-100,000 yuan range. Over time, market consensus has become more and more entrenched: small electric vehicles should be at this price.
Once a brand steps out and says it wants to make a more premium small car, just 50,000-60,000 yuan more expensive than the same class, consumers generally ask: they are all electric small cars, all based on the underlying logic of motor + battery, so why should yours be so much more expensive?
The market does not naturally give results; instead, it gives lesson after lesson.
So the small cars that sell well now are all economy volume models without exception, and a general consensus has gradually settled: for A0 small cars around 4.2 meters long with a wheelbase of 2.6-2.7 meters, the mainstream price is 60,000-90,000 yuan. Once you step out of this range, sorry, the market and consumers will not accept it.
02 Selling small cars at high prices is getting harder and harder
Firefly is an exception. In terms of product positioning and definition, it has been relatively restrained.
Most industry analysis of why Firefly sells well focuses on the fact that it found a unique playbook and precisely captured its own audience.
It carries the NIO badge and comes with luxury brand endorsement. The official price of 120,000-150,000 yuan does not look low, but most users choose the BaaS battery rental plan, which directly lowers the entry threshold to 80,000-90,000 yuan, putting it in the same transaction range as the Seagull and Xingyuan.
In other words, behind Firefly's hot sales, keywords such as "cheap" and "value for money" are still indispensable.
The main demand in the small car market is for mobility, and behind that is the current consumption environment. Simply put, consumer attitudes are more pragmatic, and people are more cautious about spending.
But users who buy Firefly and those who buy Seagull or Xingyuan are not the same kind of people to begin with.
Users who choose Xingyuan or Seagull have value for money as their core demand. Their budget is fixed, and they prioritize space and price. At the same price, of course, the higher the configuration and the larger the size and space, the better. As for quality and safety, those naturally have to come later.
Those willing to buy Firefly value quality, safety, personality, and NIO's brand endorsement. Even though it is only a 400V architecture, charging speed is not particularly fast, and the configuration is not aggressive, it still has an audience.
Of course, there is also the psychological advantage brought by BaaS: the battery does not belong to you, so you do not have to worry about battery degradation or residual value anxiety. After three to five years, you can even swap in a new battery, greatly reducing concerns about range and vehicle condition. Even paying about 300 yuan a month in battery rent is, for this group of users, equivalent to the cost of a meal, with very little pressure.
This is also what makes Firefly difficult to replicate. The product did not rely on hard competition; rather, NIO's years of brand accumulation, battery swapping system and BaaS model together lifted Firefly. In addition, it achieved the best result among small cars in C-IASI crash tests, and its quality control and safety foundation are solid. Only with multiple supports did this special case emerge.
Beyond this special case, it is very difficult for other premium small electric cars to find room, especially in an era when electrification has just penetrated entry-level small cars. For premium small cars to sell at high prices, the threshold is already absurdly high.
Last month's launch price of Lynk & Co 20 is a very typical example. The old model was priced on the high side and did not have much advantage against the many Xingyuan and Seagull models. The new model directly did the opposite: the entire lineup moved to 800V, was equipped with LiDAR, hardware was fully upgraded, and the official guide price was cut by 12,000 yuan, with maximum benefits stacking up to 17,000 yuan in discounts.
The essence of this strategy is that Lynk & Co saw reality clearly: selling small cars at high prices does not work, and to drive volume, it must stack equipment and cut prices. The current situation of Smart and MINI, the first batch of premium electrified players, also confirms this logic.
Not long ago, the Smart #1 annual model was updated, with prices coming down from the original 170,000-180,000 or 200,000 yuan to 140,000-150,000 yuan. Sales saw an obvious rebound, but they are still below the Smart #1's peak sales.
MINI has launched 3-4 pure electric models, but China no longer publishes data. Judging from insurance registration numbers, together they total only about 1,000 units. The brand dividends of Mercedes-Benz and BMW in China are no longer what they used to be, and the premium support they can give Smart and MINI is becoming weaker and weaker.
So looking back at Smart, the strategy of getting bigger it adopted earlier has actually fallen into the endless involution of the Chinese market, while losing the distinctive characteristics it should have had.
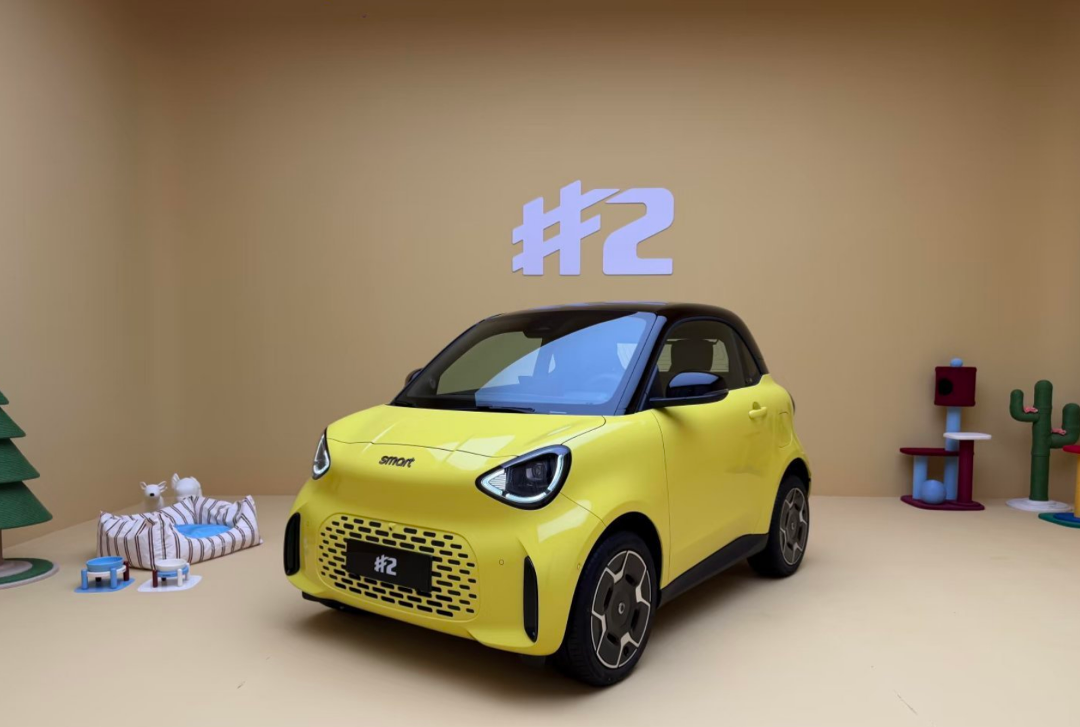
Next, Smart will launch a two-door two-seat micro electric vehicle #2. A limited edition has already gone on sale, priced at 113,000 yuan. The estimated transaction price after the official launch will fall in the 80,000-100,000 yuan range.
But in this price range, there are still the Wuling Hongguang MINI and Geely Panda ahead, which can be had for 30,000-50,000 yuan. Last year, with subsidies, they could easily exceed 10,000 units a month; this year, once subsidies stopped, their true colors were immediately revealed. If Smart's two-door small car can reach 3,000 units in monthly sales after launch, that would already be a good result; it will be hard to replicate the volume myth of cheap mobility vehicles.
In the end, in the electric era, giving small cars high premiums based on brand sentiment is becoming harder and harder. Smart and MINI could thrive in the past because they lived off brand filters accumulated over the long fuel era. Firefly's success is an isolated case created by the superposition of model, brand and pricing strategy.
This kind of case has no precedent, and it should be very difficult for another to appear later.
Editor in charge: Li Sijia Editor: He Zengrong
THE END
-
![]()
When Every Company Dons the AI "Hat"
-
![]()
Toy Giant ZURU Moves China HQ to Shenzhen's China Resources Tower with 30,000 sqm Lease
-
![]()
SDD Spec-Driven Development Tutorial — The More Features You Add, the More AI Starts "Making Things Up"
-
![]()
Xpeng MONA's Three Models Overlap in Price Range of 119,800 to 176,800 Yuan, Beginning to Compete with Themselves
-
![]()
Avatr Cancels Launch Event: Carmakers Spend 8.12 Million Yuan on a Grand Show, Yet 87% of New Cars Peak in Their First Month
-
![]()
XPeng Robotaxi Cleared for Full-Area Demonstration Operations in Guangzhou — the Real Test Has Only Just Begun
-
![]()
BYD Enters the Million-Employee Era: The World's Largest Automaker by Headcount
-
![]()
Tesla's Q3 Earnings: Profits Halved, Yet the Stock Rose—Here's Why