October New Energy Vehicle Sales Revealed: Leapmotor Up 51% Year-on-Year, While NIO, Li Auto and Harmony Intelligent Mobility All Decline
 11/02 2026
 535
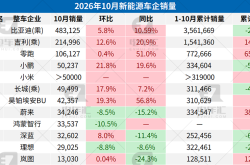
October 2026 new energy vehicle sales data has been gradually released, with the auto market showing a different trajectory from previous years during the "Silver October": leading automakers continued to push higher, BYD set a new monthly sales high for the year, Leapmotor's year-on-year growth remained above 50%, but NIO, Li Auto and Harmony Intelligent Mobility all posted simultaneous month-on-month and year-on-year declines, further intensifying industry differentiation. The China Passenger Car Association had previously estimated October new energy retail sales at about 1.07 million units, with penetration at about 66.9%. Judging from the performance of various automakers, the resilience of new energy vehicles is clearly stronger than that of the overall market.
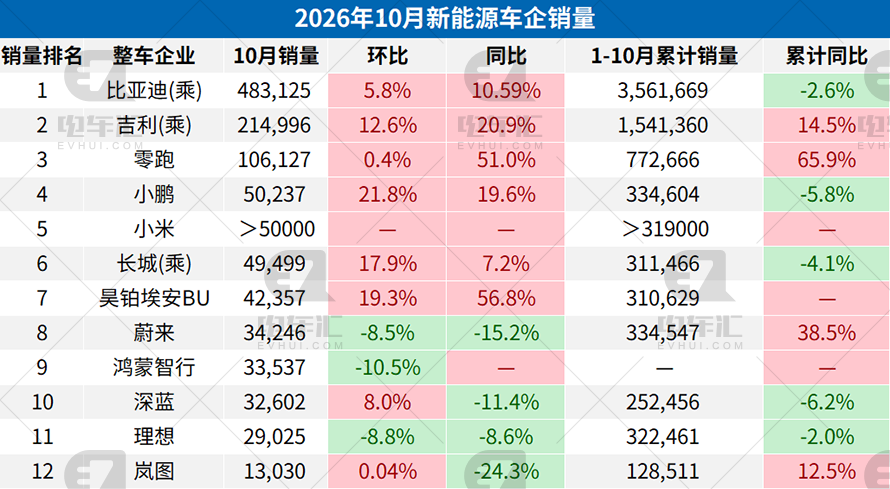 (Statistics only include automakers that published sales data on time on the 1st of each month)
BYD Passenger Vehicles
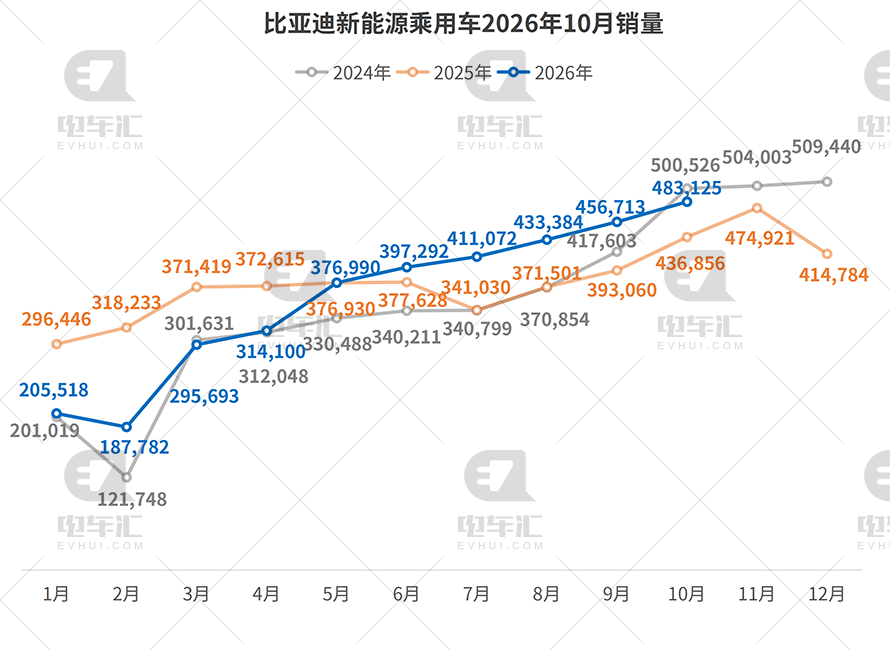
In October, BYD's new energy passenger vehicle sales reached 483,125 units, up 5.8% month-on-month and 10.59% year-on-year, setting a new monthly high for the year; cumulative sales from January to October reached 3,561,669 units, with the cumulative year-on-year decline narrowing to 2.6%, continuing to rank first in domestic new energy passenger vehicle sales.
The consecutive month-on-month increases were driven by both new product launches and recovering orders since late September: prior order data for the 43rd week showed BYD's weekly orders surged 40% month-on-month, and October sales delivered on this wave of order momentum.
On the export front, BYD's overseas business remained at a high level, overseas localized production continued to land, and second-generation Blade batteries and megawatt-level flash charging technology accelerated their deployment to overseas models. Overseas markets remain the core lever for hedging domestic fluctuations.
On the product side, multiple facelifted models from the Ocean Network and Dynasty Network continued to be launched, and the product matrix and channel inventory preparations for the year-end sales push are relatively sufficient.
Geely New Energy
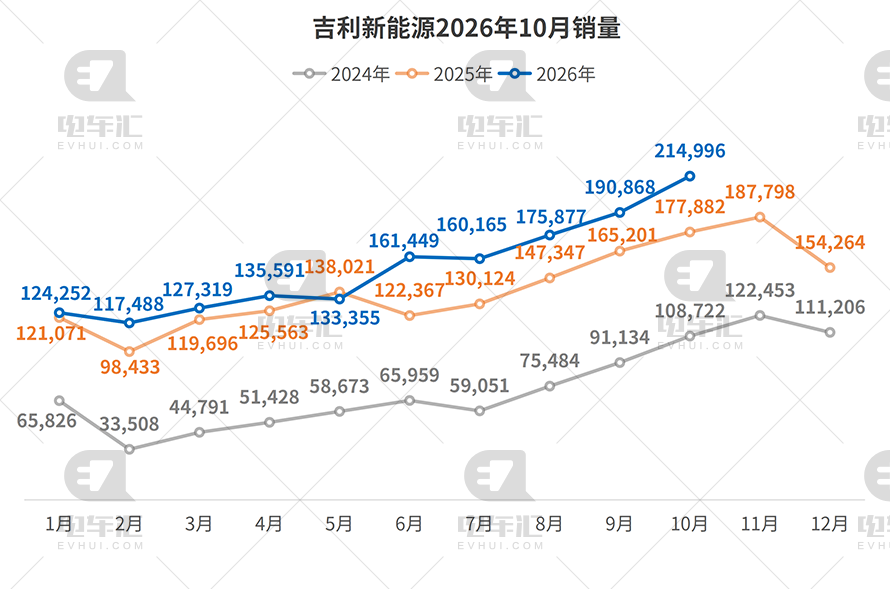
In October, Geely's new energy vehicle sales reached 214,996 units, up 12.6% month-on-month and 20.9% year-on-year; cumulative sales from January to October reached 1,541,360 units, up 14.5% year-on-year, firmly ranking second in the industry. The Galaxy series continued to drive volume, overseas exports and localized manufacturing in Europe advanced in parallel, and the synergy effects of multiple brands continued to be released.
Leapmotor
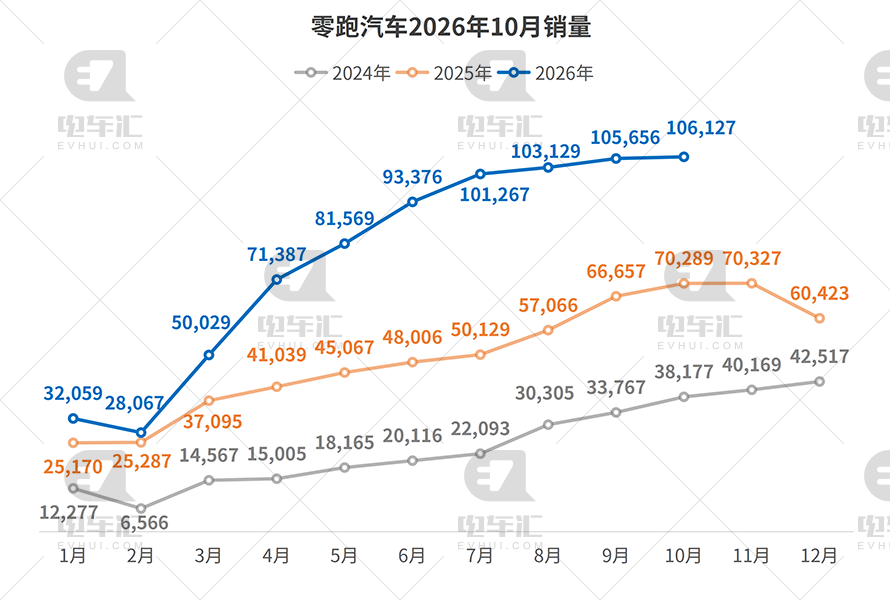
In October, Leapmotor delivered 106,127 units, up 0.4% month-on-month and 51.0% year-on-year; cumulative deliveries from January to October reached 772,666 units, up 65.9% year-on-year, the highest cumulative growth rate among leading automakers. After stabilizing monthly sales at the 100,000-unit level, Leapmotor's scale-driven cost advantages continued to materialize, orders in Europe and the Middle East grew steadily, and localized assembly at its Spanish plant is underway.
XPeng
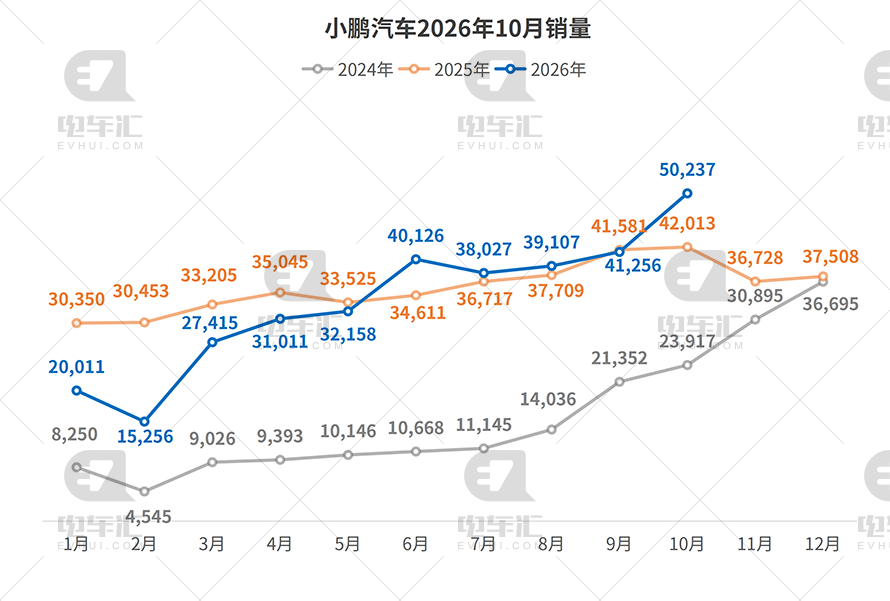
In October, XPeng delivered 50,237 units, up 21.8% month-on-month and 19.6% year-on-year, with monthly deliveries returning to the 50,000-unit level; cumulative deliveries from January to October reached 334,604 units, with the cumulative year-on-year decline narrowing to 5.8%. With new models ramping up and orders recovering, XPeng became one of the leading new forces with the most obvious month-on-month improvement in October, and the localized adaptation of Turing AI smart driving continued to advance in the European market.
Xiaomi Auto
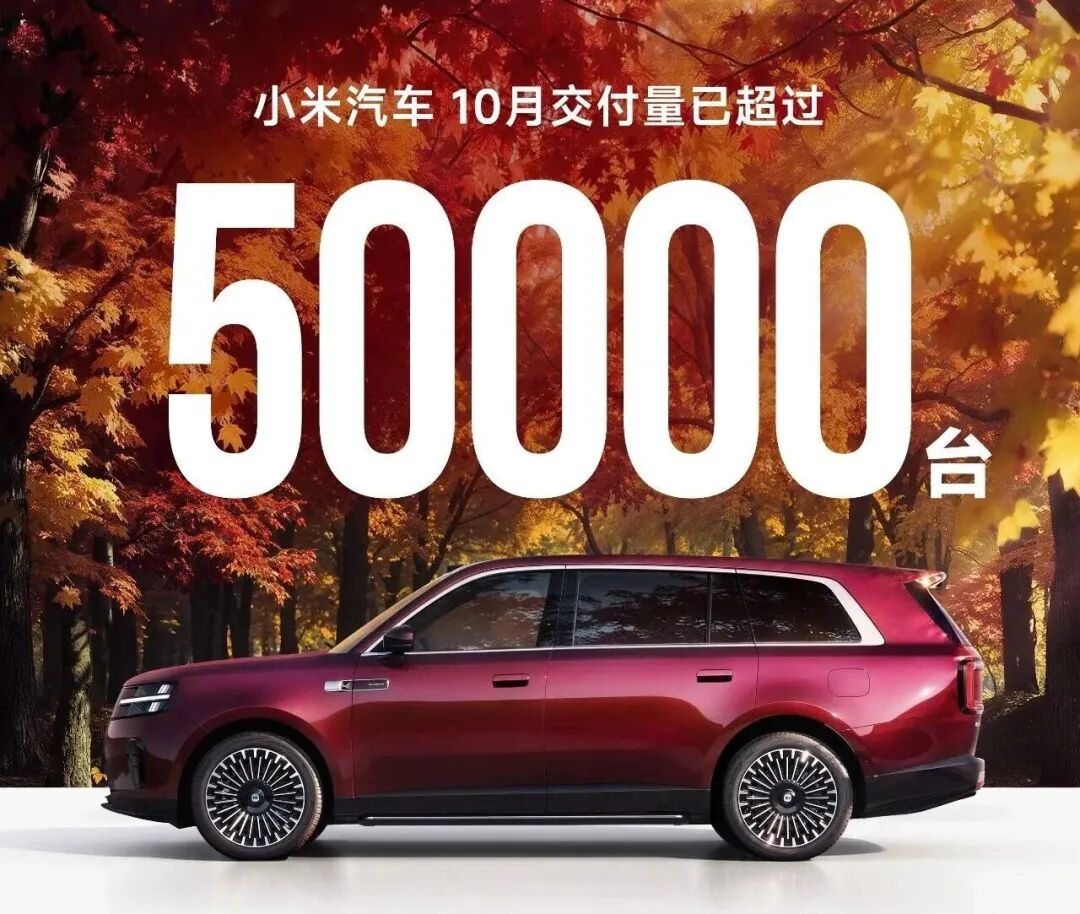
In October, Xiaomi Auto's deliveries remained above the 50,000-unit level, with cumulative deliveries from January to October exceeding 319,000 units. After the launch of two extended-range SUVs in the Pengcheng series, Xiaomi completed its dual-category layout of pure electric plus extended-range, with monthly deliveries stabilizing at the edge of the first tier of new car-making forces.
Great Wall Motor
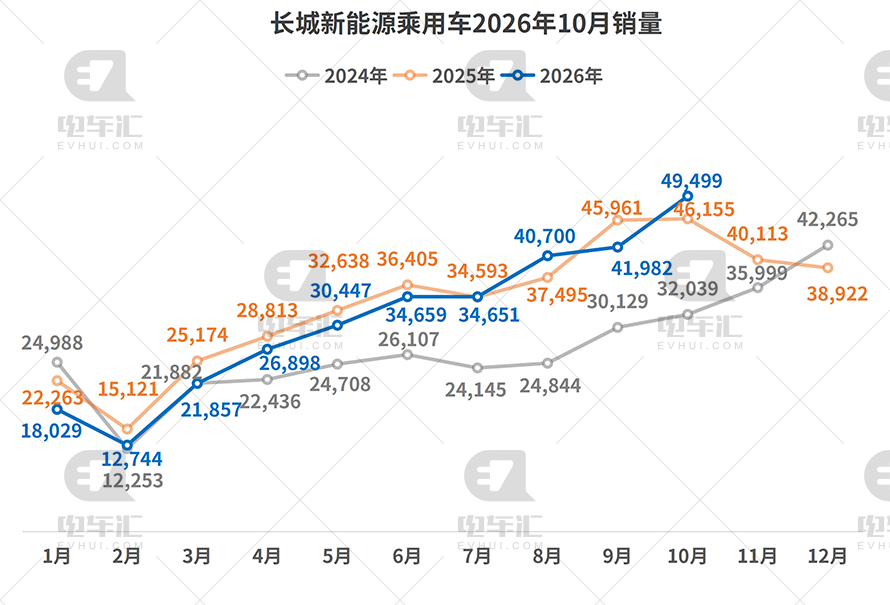
In October, Great Wall's new energy passenger vehicle sales reached 49,499 units, up 17.9% month-on-month and 7.2% year-on-year; cumulative sales from January to October reached 311,466 units, down 4.1% year-on-year. The pace of new energy transformation accelerated, with monthly sales approaching the 50,000-unit threshold.
Hyptec AION BU
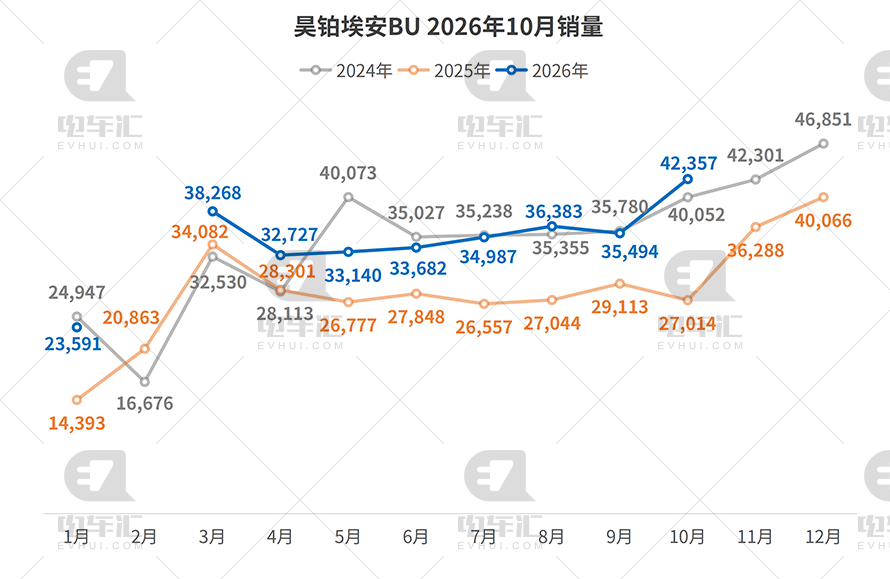
In October, Hyptec AION BU sales reached 42,357 units, up 19.3% month-on-month and 56.8% year-on-year; cumulative sales from January to October reached 310,629 units. Its year-on-year growth rate was second only to Leapmotor among major automakers, overseas channels in Southeast Asia and the Middle East continued to expand, and the second-generation AION V continued to serve as the mainstay.
NIO
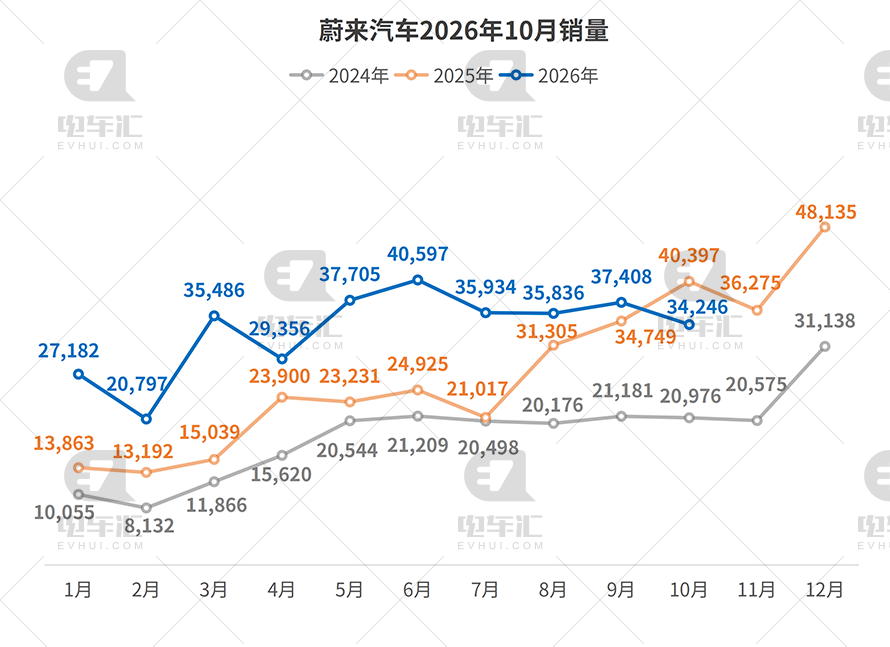
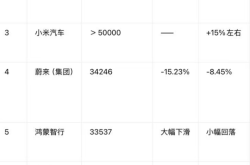
In October, NIO delivered 34,246 vehicles, down 8.5% month-on-month and 15.2% year-on-year, making it one of only two leading automakers with a year-on-year decline; however, cumulative deliveries from January to October reached 334,547 units, up 38.5% year-on-year, with the full-year base still intact. Onvo and Firefly multi-brand volume faced pressure, overseas battery swap network expansion and battery asset operations continued to advance, and whether the year-end new product cycle can reverse the monthly slump is a key point to watch.
Harmony Intelligent Mobility
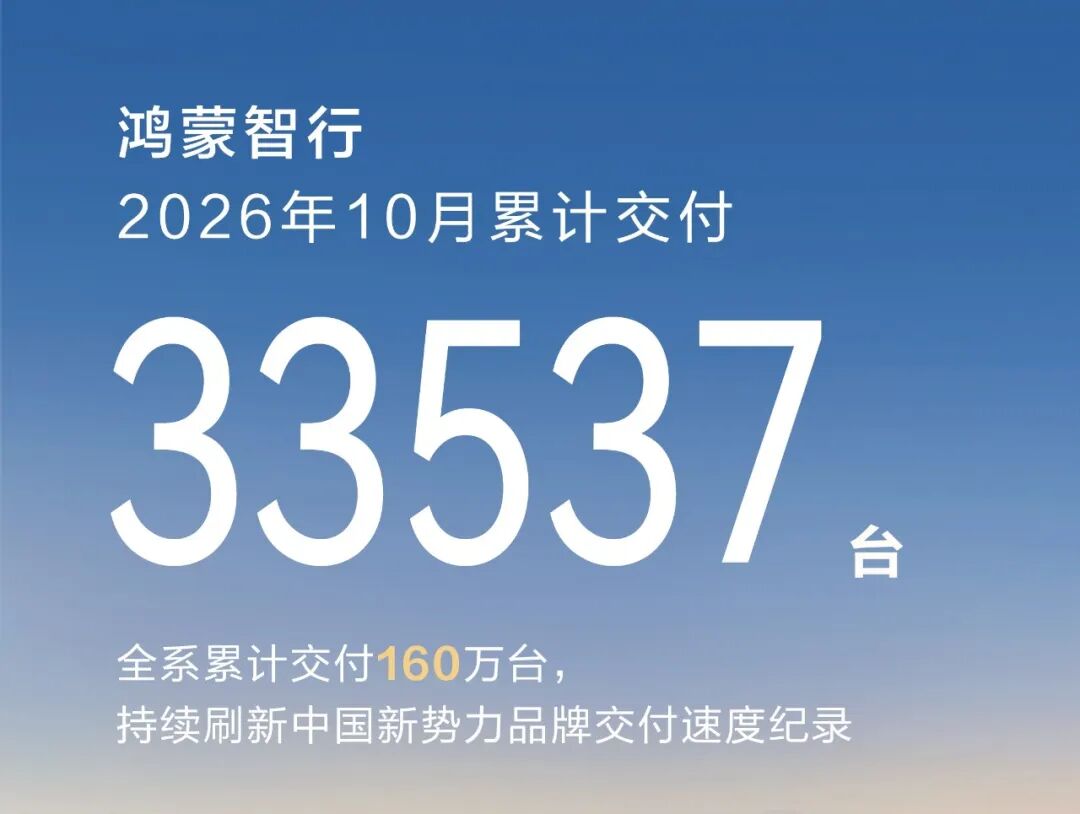
In October, Harmony Intelligent Mobility delivered 33,537 new vehicles, down 10.5% month-on-month. Deliveries of the AITO and Luxeed series declined, high-end new products have not yet fully taken over volume ramp-up, and new models from Maextro and Stelato are in the early stages of ramp-up, with the pain of the product transition period in the fourth quarter being evident.
Deepal
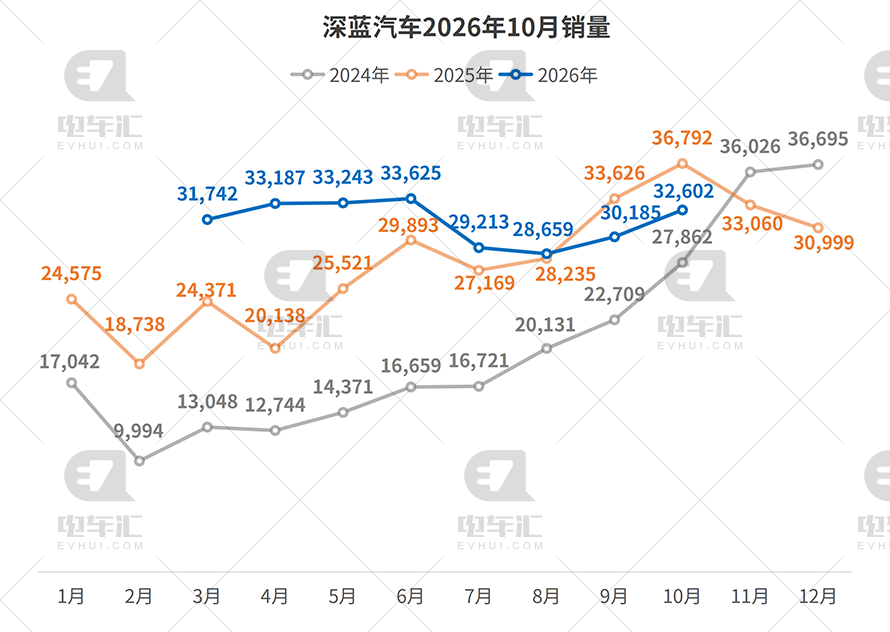
In October, Deepal sales reached 32,602 units, up 8.0% month-on-month and down 11.4% year-on-year; cumulative sales from January to October reached 252,456 units, down 6.2% year-on-year. The domestic market faced pressure, while overseas markets became the main source of incremental growth. Its products have covered multiple countries worldwide, with right-hand-drive models positioned for Southeast Asia and Australia.
Li Auto
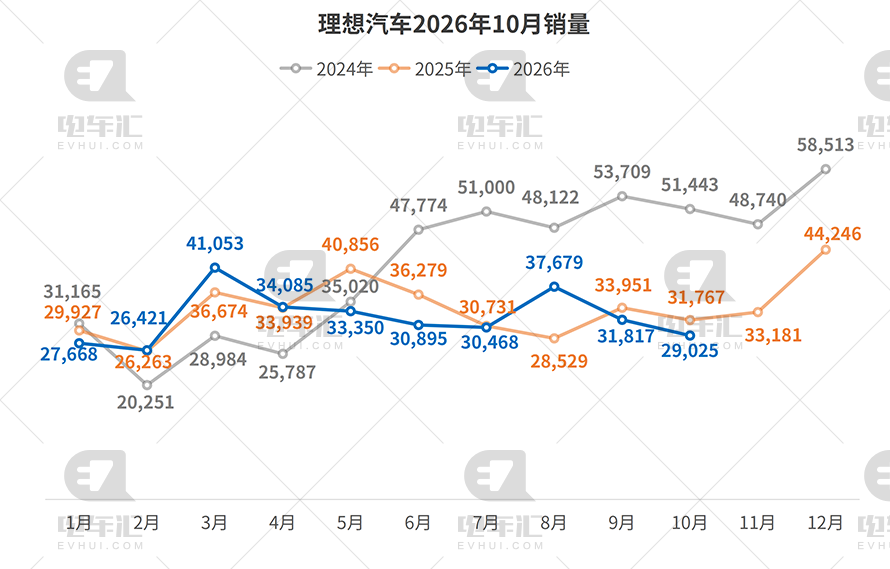
In October, Li Auto delivered 29,025 vehicles, down 8.8% month-on-month and 8.6% year-on-year; cumulative deliveries from January to October reached 322,461 units, down 2.0% year-on-year. With the transition between the pure electric i series and the extended-range L series, monthly deliveries fell below 30,000 units, a rare monthly low for Li Auto in recent years. Overseas localized production and smart driving OTA upgrades continued to advance, and the year-end major facelift models are key to a turnaround.
Voyah
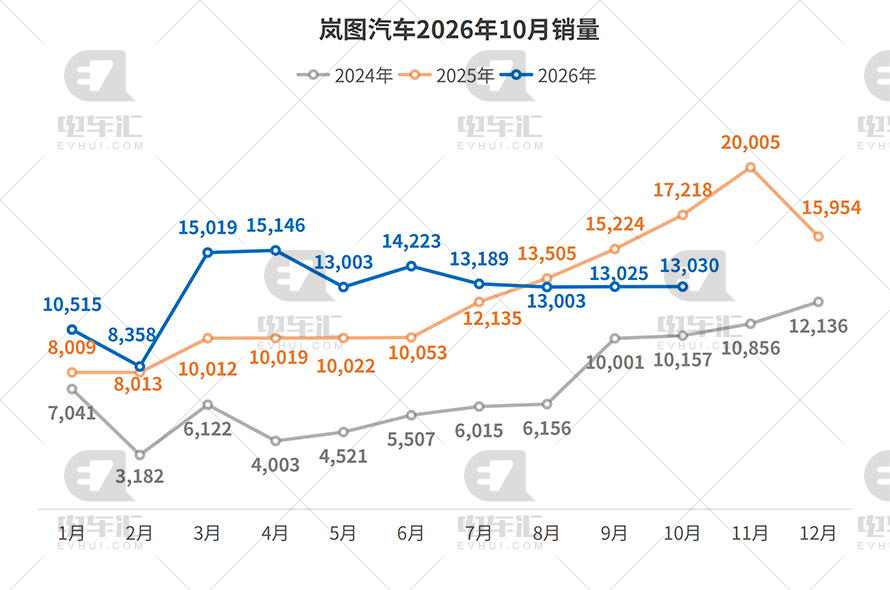
In October, Voyah delivered 13,030 vehicles, roughly flat month-on-month and down 24.3% year-on-year, the largest decline on the list; cumulative deliveries from January to October reached 128,512 units, up 12.5% year-on-year. Intensified competition in high-end new energy vehicles combined with a gap in new products put pressure on Voyah's monthly performance, while Middle East market penetration and cooperation with Huawei Qiankun smart driving continued to advance.
The October rankings present three distinct characteristics. First, "the strong get stronger": BYD, Geely and Leapmotor together accounted for the majority of sales among the top twelve on the list, and all posted positive month-on-month growth, corroborating Cui Dongshu's judgment that "the auto market will bottom out and recover in 2027, with industry differentiation intensifying." Second, "the ranking of old and new forces is changing": Leapmotor's cumulative growth rate of 65.9% stood far ahead, XPeng, Xiaomi and Great Wall improved significantly month-on-month, while NIO, Li Auto and Harmony Intelligent Mobility, three former leaders, all declined simultaneously, accelerating the reshuffling of the second tier. Third, "resilience from the cumulative perspective": BYD's cumulative decline narrowed to 2.6%, just one step away from turning positive. If month-on-month growth continues in November and December, it is expected to match last year's level for the full year, which is already a rare achievement for a large automaker in the domestic price war environment.
-
![]()
Tech Stocks Plunge: Is Faith in AI Still There? New Energy Weekly Summary
-
![]()
After the Hundred-Billion-Yuan Financing Closed, DeepSeek Unveiled Its Super-Agent Architecture
-
![]()
October New Energy Vehicle Sales Revealed: Leapmotor Up 51% Year-on-Year, While NIO, Li Auto and Harmony Intelligent Mobility All Decline
-
![]()
Apple Chooses Qwen—and There's More to It Than Meets the Eye
-
![]()
The Battle Against DJI: How Ying Shi Lost 100 Billion Yuan in Market Value
-
![]()
Modern China's Predicament: Hard to Break Through by Merely Changing the General Manager
-
![]()
Cutting Corners or Compliance? iPhone Duo Teardown Reveals China-US Structural Differences — Apple Says Component Variations Are Normal
-
![]()
Leapmotor Retains the Crown as Xpeng and Xiaomi Break 50,000: The New Forces Sales Landscape Gets Another Shake-Up