Global Automotive Glass Leader with a Strong Dividend Track Record
 11/06 2026
 563
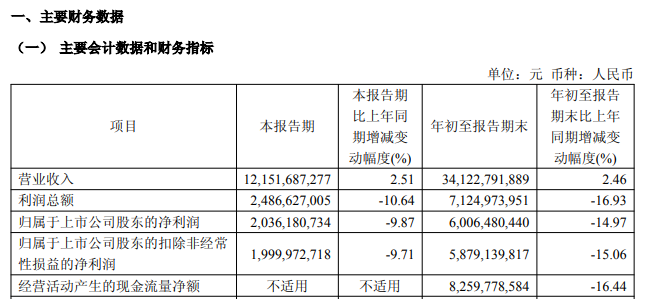
As a leader in the global automotive glass market, Fuyao Glass has delivered consecutive years of performance growth with solid operating quality. In the first three quarters of 2026, the company reported operating revenue of RMB 34.123 billion, up slightly by 2.46% year on year, while net profit attributable to the parent company came in at RMB 6.006 billion, down 14.97% year on year—a decline mainly driven by a substantial increase in exchange losses. The company plans to adopt appropriate foreign exchange tools to hedge against currency risks going forward.
Beyond its performance growth, Fuyao Glass has been remarkably generous with dividends. Since its listing in June 1993, the company has distributed a cumulative RMB 42.830 billion in cash dividends and bonus shares to investors, equivalent to 64.38% of its net profit attributable to the parent company over the same period. The interim dividend for 2026 stood at RMB 2.61 billion, with a payout ratio of 65.73%.
Revenue Up, Profit Down in the First Three Quarters
Why did profit turn down during the year? From 2021 to 2025, Fuyao Glass achieved consecutive years of performance growth, with operating revenue of RMB 23.603 billion, RMB 28.099 billion, RMB 33.161 billion, RMB 39.252 billion and RMB 45.787 billion respectively—a compound annual growth rate of about 18%. Net profit attributable to the parent company over the same period was RMB 3.146 billion, RMB 4.756 billion, RMB 5.629 billion, RMB 7.498 billion and RMB 9.312 billion respectively, representing a CAGR of approximately 31%.
In the first three quarters of 2026, the company posted operating revenue of RMB 34.123 billion, up 2.46% year on year—a notably slower pace—while net profit attributable to the parent company fell sharply by 14.97% year on year to RMB 6.006 billion, falling into a "revenue up, profit down" situation. The root cause of modest revenue growth paired with a sharp profit decline lies in exchange losses, which amounted to as much as RMB 1.067 billion.
Fuyao Glass stated that it will address foreign exchange risks through the following measures: expanding its international footprint; reasonably matching the scale of foreign-currency assets and liabilities with the expansion of overseas business; optimizing the currencies used for business settlement; matching receipts and payments in the same currency; and adopting appropriate foreign exchange tools such as exchange rate locking, forward foreign exchange contracts, currency swap contracts, currency swaps and other financial derivative products to achieve the purpose of hedging against foreign exchange risks.
According to disclosed figures, from 2013 to 2025, the company's cumulative exchange gains reached RMB 1.578 billion. Even including the exchange loss in 2026, cumulative exchange gains still exceeded RMB 500 million. Overall, gains have outweighed losses, which also confirms the effectiveness of the company's approach to managing exchange rate fluctuations.
Growth slowed during the year, while gross margin rose. Fuyao Glass provides full solutions for safety glass and automotive trim for various transportation vehicles, including the design, production, sales and service of automotive-grade float glass, automotive glass, locomotive glass, roof racks and window trim.
Fuyao Glass is unquestionably the leader in the global automotive glass market. Brokerage research reports in 2026 generally cited a market share of about 34%, meaning that one out of every three pieces of automotive glass in the world comes from Fuyao. Its domestic market share is about 68%—nearly seven out of every ten pieces of automotive glass in China come from Fuyao—clearly demonstrating the company's leading position.
From 2023 to 2025, the company's automotive glass revenue was RMB 29.887 billion, RMB 35.712 billion and RMB 41.889 billion respectively, with year-on-year growth of 16.79%, 19.49% and 17.3%. Gross margins fluctuated, at 30.59%, 30.15% and 31.32% respectively.
During the same period, float glass achieved operating revenue of RMB 5.708 billion, RMB 5.961 billion and RMB 6.48 billion respectively, with year-on-year growth of 25.82%, 4.42% and 8.71%. Gross margins rose continuously, at 28.71%, 36.04% and 39.64% respectively.
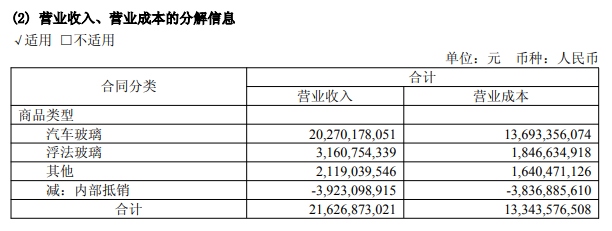
In the first half of 2026, automotive glass achieved operating revenue of RMB 20.27 billion, up 3.75% year on year, with a gross margin of 32.45%, up 1.55 percentage points year on year; float glass achieved operating revenue of RMB 3.161 billion, up 2.11% year on year, with a gross margin of 41.58%, up 2.17 percentage points year on year. While revenue growth of the two core products slowed, profitability still improved—living up to its reputation as an automotive glass leader.
Domestic automobile production and sales both declined. According to statistics from the International Organization of Motor Vehicle Manufacturers (OICA), global automobile sales from January to September 2026 totaled 72.52 million vehicles, up 3% year on year, with growth momentum weaker than in the first half. The decline in China's share in the first three quarters was the core variable behind the weaker global growth. Data from the China Association of Automobile Manufacturers shows that from January to September 2026, China's automobile production and sales were 23.246 million and 23.271 million vehicles respectively, both down 4.5% year on year.
Furthermore, domestic automobile sales were only 15.066 million vehicles, plummeting 22.4% year on year—a sign of weak domestic demand momentum—while export sales reached as high as 8.205 million vehicles, surging 65.8% year on year, making exports an important growth driver. The China Association of Automobile Manufacturers predicts that full-year exports are expected to exceed 10 million vehicles.
More than half of Fuyao Glass's revenue comes from China—about 54% in 2025—meaning domestic production and sales have a relatively large impact on the company's performance. In the first half of the year, domestic automobile production and sales were 14.993 million and 15.017 million vehicles respectively, down 4% and 4.1% year on year. Against this backdrop, it was no easy feat for the company to still maintain slight performance growth. To break through, it must further expand overseas markets. However, the U.S. automobile market has also contracted, and whether emerging markets such as India can provide more incremental growth remains to be seen.
Solid Operating Quality with a Strong Dividend Track Record
Strong R&D, over RMB 7.2 billion invested in five years. As a global automotive glass leader, Fuyao Glass attaches considerable importance to R&D investment. From 2021 to 2025, R&D expenses were RMB 997 million, RMB 1.249 billion, RMB 1.403 billion, RMB 1.678 billion and RMB 1.913 billion respectively, totaling RMB 7.24 billion over five years. The R&D expense ratio remained broadly stable, at 4.22%, 4.44%, 4.23%, 4.27% and 4.18% respectively—all above 4%.
In the first three quarters of 2026, the company's R&D expenses were RMB 1.625 billion, up 16.65% year on year, and the R&D expense ratio further rose to 4.76%, mainly because the company further increased investment in R&D projects, continued to pursue R&D innovation, and promoted technological upgrading and improvement of product added value.
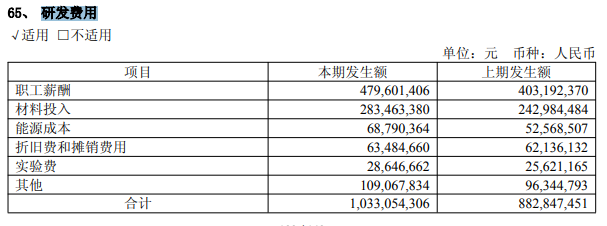
The bulk of R&D expenses was employee compensation, with the interim report amount and proportion at RMB 480 million and 46.43% respectively. At the end of 2025, R&D personnel numbered 6,338, accounting for 14.9%, mainly those with bachelor's degrees—as many as 3,844. At present, the company has built a relatively complete industrial ecosystem: sand mine resources, high-quality float technology, process equipment R&D and manufacturing, multifunctional integrated glass, extension into the aluminum trim industry, globally deployed R&D centers and supply chain networks, and a unique talent training and development mechanism—together forming a systematic industrial advantage and "moat."
With the rapid development of automotive intelligence, automotive glass and trim have evolved from merely providing shelter from wind and rain into components of smart cockpits and platforms for perception and interaction with the outside world. Fuyao Glass has strengthened market insight and technological insight, pursued cross-sector integration, continuously improved glass manufacturing technology and raw material research, and launched high-value-added products such as smart panoramic roof glass, dimmable glass, head-up display glass, super-insulated glass, lightweight ultra-thin glass, coated heatable glass and flush tempered laminated glass. The proportion of related products in revenue has increased, rising 8.03 percentage points year on year in the 2026 interim report.
Solid operating quality. As an automotive glass leader, Fuyao Glass has good operating quality. From 2021 to 2025, operating cash flow was RMB 5.677 billion, RMB 5.893 billion, RMB 7.625 billion, RMB 8.5662 billion and RMB 12.055 billion respectively, with net profit cash content of 180.44%, 123.92%, 135.45%, 114.19% and 129.45% respectively.
In the first three quarters of 2026, the company's operating cash flow was RMB 8.26 billion, down 16.44% year on year, and net profit cash content was 317.51%, mainly because notes payable at the end of the previous year were settled during the year, increasing cash outflows year on year, and during the reporting period the company reduced commercial bills and increased cash-settled procurement.
As of the end of the period, the company's notes receivable and accounts receivable were RMB 688 million and RMB 7.618 billion respectively, totaling RMB 8.306 billion, while notes payable and accounts payable were RMB 3.222 billion and RMB 2.725 billion respectively, totaling RMB 5.947 billion. Customers owed the company far more than the company owed suppliers.
Consistent, substantial dividends. Fuyao Glass has always been quite generous with dividends: RMB 3.393 billion in 2023, RMB 4.698 billion in 2024, RMB 5.481 billion in 2025, and an interim dividend of RMB 2.61 billion in 2026, with a dividend payout ratio as high as 65.73%, continuously strengthening returns to shareholders.
Since its listing in June 1993, Fuyao Group has distributed a cumulative RMB 42.830 billion in cash dividends and bonus shares to investors, equivalent to 64.38% of the net profit attributable to shareholders of the listed company cumulatively achieved through the first half of 2026, giving investors reliable and stable returns.
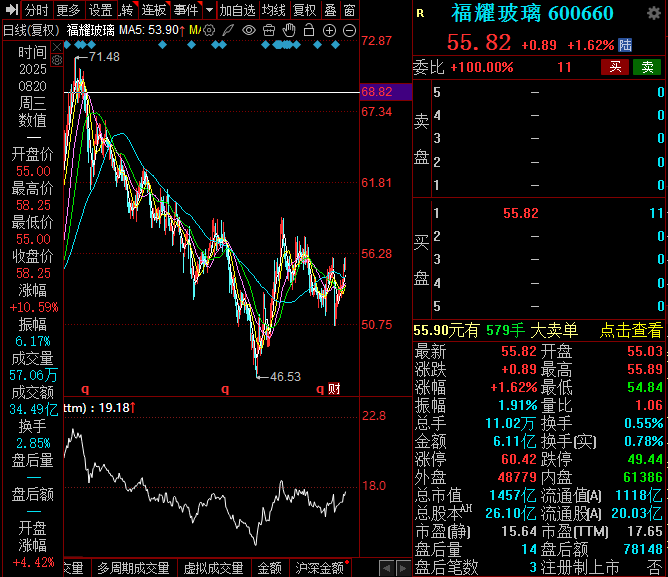
In the secondary market, after the company's share price reached a high of RMB 71.48 per share in September 2025 (forward-adjusted, same below), it entered a relatively prolonged decline, hitting a low of RMB 46.53 per share. The stock price then rebounded rapidly. The closing price on November 5 was RMB 55.82 per share, down 22% from the high, with a total market value of RMB 145.7 billion and a TTM price-to-earnings ratio of 17.65 times.
(Short, Plain and Fast Interpretation—original work, please do not reprint without permission! PS: If the manuscript infringes rights or the data is incorrect, please contact us promptly for correction.)

-
![]()
Why Can Longgang's Cross-Border E-Commerce Keep Its Lead Steady Despite Industry-Wide Headwinds?
-
10 Years On: Chip Performance Has Grown 40-Fold and Memory 8-Fold—So Why Do Phones Still Lag?
-
![]()
B2B Buyer's Guide: Waveguide Supplier Directory and Technology Roadmap Comparison
-
![]()
Will Automotive Chips Keep Getting More Expensive in 2027? How Much Will Cars Cost Across Four Price Tiers?
-
![]()
Gree Electric: Draining the Reservoir
-
Volkswagen Is Feeling the Pain—Badly
-
![]()
Five-Meter Body and Magnetorheological Suspension: Can the Second-Generation Seal 07 Max Out Driving Control?
-
![]()
Global Automotive Glass Leader with a Strong Dividend Track Record