Observation | XGIMI and OBE Enter the AI Glasses Track, Extending the Battlefield of Projector Manufacturers from Living Rooms to Faces
 10/20 2026
 415
Early this year, XGIMI, a leading smart projector manufacturer, showcased three AI glasses products and announced the launch of its new sub-brand, MemoMind. On June 28, MemoMind One was launched on Kickstarter for overseas crowdfunding. On October 15, XGIMI began pre-sales of the MemoMind One AI display glasses on domestic e-commerce platforms, with a final price of 2,294 yuan after subsidies.
Around the same time, OBE, a leading enterprise specializing in 1LCD projection, released the AI Audio Recording Glasses developed in collaboration with DingTalk on October 13. These glasses are designed for office audio recording scenarios, focusing on audio recording capabilities to meet all-day wearability needs, with pricing starting at 1,299 yuan.
Going forward, XGIMI plans to continue launching products without displays. RUNTO predicts that OBE may also continue to release versions with displays.
Thus, leading companies in the smart projector market, representing the two major technological routes of DLP and 1LCD, have officially embarked on business layouts for smart glasses as their "second growth curve."
From large-screen projection devices to wearable hardware for the human eye, the battlefield of the domestic projection industry has shifted from living rooms and bedrooms to faces. In fact, this is not a coincidence. RUNTO believes that two main factors are driving the transformation and upgrading of projector manufacturers, as well as the high degree of alignment in their directions: 1) As their core business, the projection market has experienced long-term stagnation in scale, with price wars compressing profits and limited prospects, making it unable to sustain corporate value; 2) Projections and AR glasses with displays are essentially imaging systems combining micro-optical engines and micro-display chips, sharing technological roots, with extensive overlapping capabilities and supply chains.
Sluggish Projection Market Drives Leading Companies to Seek Incremental Breakthroughs
According to RUNTO data, in the first half of 2026, sales of smart projectors (excluding laser TVs) in China reached 2.056 million units, a year-on-year decrease of 26.0%. Sales revenue amounted to 3.34 billion yuan, a year-on-year decline of 27.0%. The decline in the third quarter remained above 20%.
Multiple factors are collectively suppressing industry growth. On one hand, amid the current overall sluggish consumer spending, discretionary consumption demand has weakened, reducing the willingness to upgrade home large-screen hardware. On the other hand, the industry is trapped in a dilemma where "price cuts lead to losses, while maintaining prices makes it difficult to increase sales volume," especially with the recent rigid increase in storage component costs, further compressing profit margins. Meanwhile, the prices of large-screen LCD TVs continue to decline, exerting direct pressure on projectors in terms of contrast and brightness, significantly diverting demand for home large screens. Additionally, although potential growth scenarios such as automotive and commercial projections are being explored, their market size is limited and cannot offset the declining pressure in the home market in the short term.
Retail Volume of China's Smart Projector Market (2020-2026)
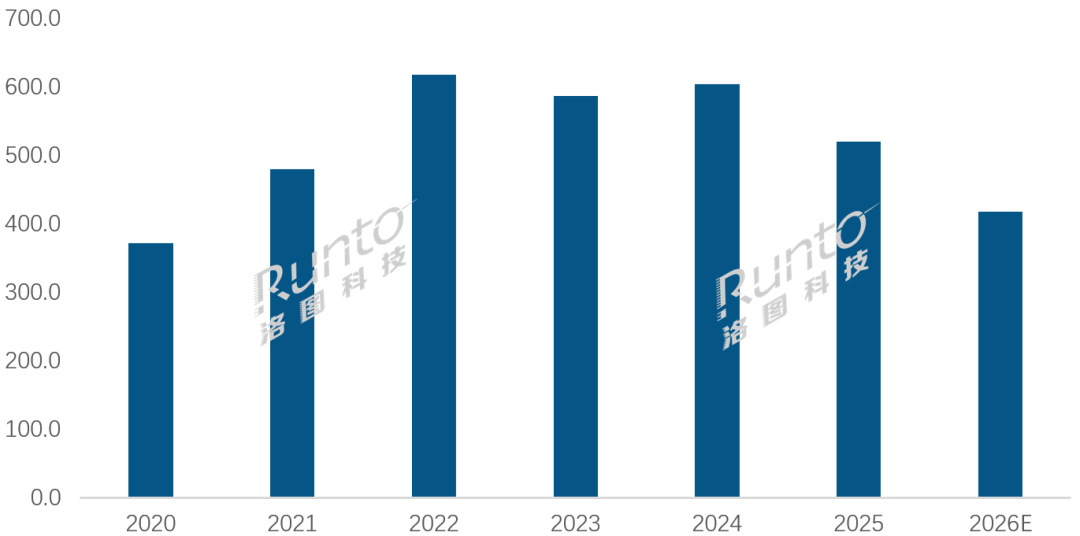
Data Source: RUNTO, Unit: 10,000 units
In the projection industry, most companies' revenues are highly dependent on the single projection segment, with a simplistic product line structure. Against this market backdrop, the ceiling for business growth is gradually becoming apparent, and risk resistance is clearly insufficient. In the long run, it is difficult to sustain continuous investment in human resources and capabilities within the company, ensure the efficiency of offline stores, or fulfill corporate value in the capital market.
As a leading enterprise in China's smart projector market, XGIMI's financial report reflects the contraction pressure in the large-screen market. Its 2026 interim report shows that XGIMI's total revenue in the first half of the year was 1.606 billion yuan, a slight year-on-year decline of 1.22%. Domestic market revenue declined significantly year-on-year. Although overseas business achieved rapid growth, it is still difficult to fully offset the pressure from the domestic market's downturn.
As a leading company in the 1LCD segment, OBE is one of the few brands in the industry that has maintained counter-trend growth during the overall market downturn. Benefiting from the consolidation of competition in the 1LCD segment and the prominence of the leading effect, coupled with its own product structure upgrades, the brand has maintained positive growth in revenue and market share.
Despite the divergent growth states of their core businesses, leading companies all hope to break free from the limitations of home large screens and explore more application scenarios for display technologies. In fact, in addition to XGIMI and OBE, Vidda has already launched audio-based smart glasses. On the supply chain side, Appotronics has previously released AR glasses optical engines based on the LCoS route, while Goertek Optics is independently developing miniaturized LCoS optical engines, waveguide components, and reserve ing (reserving) capabilities for smart glasses system integration and mass manufacturing.
Rapid Development of Smart Glasses, Diverging Tracks Match Cross-Industry Needs of Projector Companies
In contrast, the smart glasses market is accelerating its growth globally and in China. Especially in China, in 2026, smart glasses were selected as the only new category in the national subsidy catalog.
According to RUNTO data, in the first half of 2026, sales of smart glasses in China reached 909,000 units, a year-on-year increase of 85.5%. Sales revenue amounted to 1.88 billion yuan, a year-on-year increase of 98.7%, making it one of the few high-growth segments in the consumer electronics category, in stark contrast to the continuous contraction of the smart projector market.
Quarterly Sales Volume of China's Smart Glasses Market (2024-2026 H1)
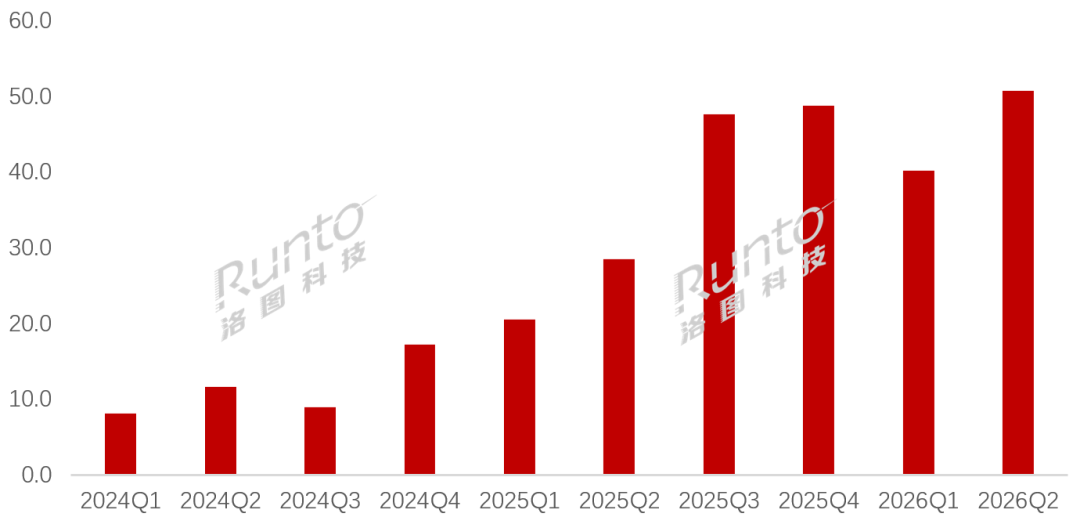
Data Source: RUNTO, Unit: 10,000 units
Moreover, in the near term, with the lightweight implementation of AI, products priced around 1,000 yuan have begun to incorporate offline large models, rapidly expanding the target demographic from tech enthusiasts to ordinary consumers.
RUNTO categorizes the smart glasses market into three segments based on function: AR glasses, camera glasses, and audio glasses. At the same time, it also aligns with the viewpoint in
The requirements for capabilities vary significantly across different segments, leading to differentiated strategies for projector companies entering the market. Audio glasses focus on voice interaction and lightweight scenarios, with lower optical implementation thresholds, making them suitable for rapid product launches and market validation. This is the primary exploration direction for Vidda and OBE. AR display glasses require high capabilities in micro-optical engines, optical coupling, and image quality calibration, aligning with the long-term accumulated optical engineering advantages of XGIMI and Appotronics, making them the core tackle key problems (focus) tracks for technology-oriented leading companies. Camera glasses emphasize imaging algorithms and have weaker associations with projection technology systems, resulting in lower overall Layout (layout) willingness in the projection industry.
Technological Foundations and Practical Challenges for Projector Companies Entering the Smart Glasses Market
Projector companies have long delved into core technologies such as micro-display chip selection, light source control, color calibration, and speckle suppression, accumulating mature optical debugging and image quality optimization systems that can directly empower AR display glasses.
At the same time, the experience gained by projector manufacturers in miniaturizing optical engines, stacking overall device structures, lightweight design, and thermal management over the years can be reused in the hardware development of smart glasses. The engineering experience accumulated in audio-visual calibration over the long term can also well adaptation (adapt to) the acoustic calibration and overall device optimization needs of audio-based glasses.
Although projector companies entering the smart glasses market have a clear technological homology foundation and hardware engineering accumulations that ordinary cross-industry manufacturers lack, RUNTO believes that significant differences still exist between long-distance projection and near-eye display, and some capabilities cannot be directly transferred and reused. A series of unavoidable practical challenges also exist in the cross-industry process.
Traditional projection involves long-distance real-image projection, relying on lenses to project images onto external screens. Smart glasses rely on components such as waveguides and Birdbath to generate near-eye virtual images, with completely different optical path logics and imaging constraints. 1) Projection optical engines cannot be simply miniaturized and directly used in glasses products. They need to address the rigid requirements of wearable devices for lightweight design, low power consumption, and high light transmittance, requiring the overcoming of a series of new optical challenges.
2) The second challenge lies in the new proposition of wearable products. Traditional projection devices do not have constraints related to prolonged wear on the face, whereas smart glasses are intimate wearable hardware. Weight distribution, long-term wearing comfort, thermal control, myopia (myopia) lens adaptation, and industrial design are all areas that projector companies have had little prior exposure to, requiring the establishment of entirely new research and development and validation systems.
3) Shortcomings also exist in software ecosystems and channel accumulations. The core capabilities of projector companies are concentrated at the hardware level, lacking software ecosystem accumulations in AI large model adaptation, intelligent interaction, and scenario application development. Simultaneously, they lack offline channels and user operation systems corresponding to the glasses category. At this stage, most can only integrate third-party AI capabilities to address software capability shortcomings. Fortunately, the business focus of leading projector manufacturers has shifted overseas, and the completed channel construction facilitates the expansion of overseas smart glasses business.
RUNTO's Summary of Viewpoints
Overall, leading projector companies' Layout (layout) in smart glasses does not constitute a complete cross-industry pivot, nor is it merely chasing trends. It represents a pragmatic strategic exploration under pressure from their core businesses, migrating their core capabilities of "building optical engines and creating large-screen imagery" from living room and bedroom screens to the lenses in front of their eyes.
The scenarios of projections and glasses complement each other, with highly overlapping user profiles—both catering to audiences who enjoy immersive large-screen audiovisual experiences. Brand recognition can be transferred, forming a full-scenario large-screen ecosystem of "fixed projections + portable glasses." Meanwhile, leveraging technological homology advantages, they can also seize the next-generation wearable display track and the next-generation human-computer interaction interface.
However, it cannot yet be seen as a "guaranteed success." The advantages of projector companies cannot eliminate the core barriers posed by wearable design, software ecosystems, and imaging principles. Additionally, pain points in consumer usage of smart glasses and long-term wearing habits still need to be addressed by the industry, and the long-term market volume and effective business increments remain to be verified.
-
![]()
Can Leapmotor Truly ‘Lead the Charge’? The Cost-Quality Trade-off Behind Export Profits
-
AI-Driven Short Dramas: A Formidable Competitor to the Gaming Industry?
-
Automotive Industry Undergoes Profound Transformation
-
![]()
Observation | XGIMI and OBE Enter the AI Glasses Track, Extending the Battlefield of Projector Manufacturers from Living Rooms to Faces
-
![]()
September Compact Car Sales Review: Traditional Fuel-Powered Models Remain Dominant
-
![]()
In the First Three Quarters, 8.2 Million Vehicles Sold: Overseas Markets Emerge as a Competitive Frontier for Chinese Automakers
-
![]()
China and the EU Both Achieve Success! Will the Export Volume of New Energy Vehicles to Europe Rise or Fall?
-
![]()
After a Year of Restructuring, WM Motor Encounters Fresh Hurdles in Production Restart