OpenAI Account Bans Are Just the Tip of the Iceberg: The "Reckoning" of AI Compute Is Unfolding Simultaneously in Washington and Wall Street
 11/09 2026
 574
Caigou Business Review | Insightful Business Editorial Team Original
Author | Xuanniao
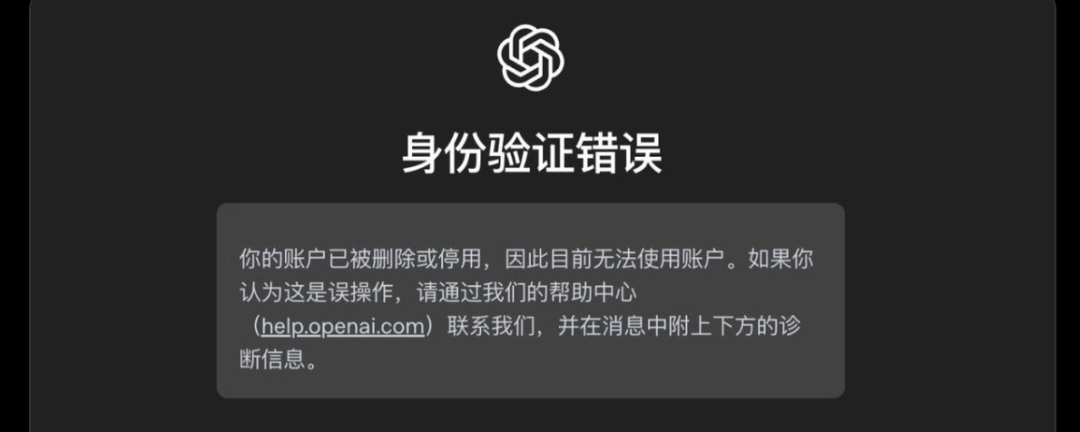
In the first week of November 2026, ChatGPT users on the Chinese internet experienced an unannounced "cyber demolition." Overnight, a large number of accounts were deactivated, with the reason field stating coldly: "suspected to be from an unsupported country or region." Wails and speculation flew through the community: some said it was guilt by association from third-party top-ups, some said reverse proxies had been taken down, and others dug up the IPO filing OpenAI had submitted just days earlier, trying to read the real motive for this ban between the lines of the prospectus.
Almost simultaneously, on November 5 the Nasdaq plunged, the Philadelphia Semiconductor Index fell 12% in a single day, Nvidia dropped more than 9%, and its market value evaporated by over $440 billion. A midterm election suddenly turned "AI capital"—the core narrative that had supported a three-year bull market in U.S. stocks—from a "perpetual motion machine" into a "high-risk asset."
The account bans and the crash look like two independent events, but if you stretch out the timeline and shift your gaze from Silicon Valley's server farms to polling stations in Texas, electricity meters in Arizona, and the model weights released by a Hangzhou company in early 2025, you will find they are connected to the same nerve: resource expectations are being repriced, and the first cut made by OpenAI and its peers was aimed at overseas accounts.
An "AI Infrastructure Boom" Strangled by Electricity Bills and Ballot Boxes
To understand the account bans, you first need to understand what U.S. AI companies fear right now.
What they fear is not that the models cannot run, but that the physical foundation for running the models is turning from a "national strategy" into a "political liability." The results of the 2026 midterm elections put this on the table: the Democratic Party not only retook both the Senate and the House, but also won landslide victories in multiple governorships and state legislatures. Texas, a data center stronghold, even flipped blue, and one of the campaign promises of newly elected Governor Gina Inojosa was to "immediately pause data center construction." Ballotpedia's statistics are even more blunt: of roughly 50 proposals on the 2026 ballot aimed at constraining data centers, at least 46 won majority voter support.
Voters are not abstractly "anti-AI"; they are voting with their electricity bills. In Phoenix, Arizona, the utility company in areas dense with data centers proposed a one-time 45% increase in electricity prices for "major power users," and ordinary residential users could not escape a 14.5% increase either. In Baltimore, Maryland, due to its proximity to the Virginia data center corridor, residents' electricity bills rose 80% over the past three years. A 2025 Bloomberg analysis was even more alarming: Americans living near data centers saw monthly energy bills rise by as much as 267% compared with five years earlier. International Energy Agency data shows that in 2025 alone, the electricity consumption of AI data centers grew by about 50%.
The water problem is equally acute. Cooling systems compete with residents for already strained water resources, and the backlash is especially fierce in arid regions. Harvard Business School professor Shane Greenstein put it incisively: the scale of AI data centers far exceeds that of traditional facilities, concentrated electricity use drives up residential electricity prices, noise and water consumption from cooling equipment are increasingly prominent, and the economic benefits to local communities are unclear.
Thus, an "AI hegemony" narrative once embraced by both parties became a hot potato in the autumn of 2026. Survey data from Heatmap News shows that since 2026, at least $260 billion in planned data center investment in the United States has been canceled due to local opposition, while nearly $1 trillion in projects face varying degrees of resistance. UBS strategists estimate that nearly one-third of the U.S. compute expected to come online by 2028 now faces the risk of construction halts or delays. Data from regulatory intelligence firm RegLayer shows that at least 47 large projects encountered delays, withdrawals, or obstruction in 2026; Bernstein analysts estimate that only about 35% of the planned U.S. data center project pipeline is truly credible.
In other words, AI companies do not want to stop building—they cannot build. What constrains U.S. AI companies are resources: electricity, water, land, political permits, and so on, and solving all these factors ultimately comes down to money. The problem is that the AI sector now has "no money."
The Kill Line: When "Certain to Win" Becomes "Might Win"
But resource constraints did not appear only in 2026. Electricity prices were rising and the public was complaining, and these signals had been accumulating well before the midterm elections. What truly pushed the situation from "tension" to "contraction" was the detonation of another hidden fuse.
In January 2025, DeepSeek-R1 was released, claiming to achieve performance comparable to OpenAI o1 with a training cost of about $6 million, while the training cost of GPT-4 was estimated at around $100 million. That number alone was striking enough, but what was truly devastating was the chain reaction it triggered: Nvidia's market value evaporated by nearly $600 billion in a single day, setting the record for the largest single-day market value loss in the history of a U.S. company—a figure that even exceeded the $500 billion total budget of the "Stargate" project just announced by Trump.
What is "Stargate"? It is the largest AI infrastructure plan in history, launched in January 2025 under White House leadership with OpenAI joining forces with SoftBank and Oracle: $500 billion over four years, 10 gigawatts of capacity, aimed at "ensuring the United States' leadership in global AI." Before DeepSeek appeared, this narrative was self-consistent: the United States would use absolute compute superiority to lock up the admission ticket to AGI; the larger the capital expenditure, the deeper the moat, and the winner takes all. But DeepSeek proved one thing at a cost of less than a fraction of that: the marginal returns of stacking compute may be far less steep than assumed in Wall Street models.
The emergence of DeepSeek smashed the U.S. AI narrative to pieces. An obscure little Chinese company, using a few million dollars of compute cost, built domestic AI capabilities into a product comparable to American AI. Moreover, the price of this domestic model is far, far lower than that of American AI models, and most critically, DeepSeek is an open-source model. Open source means it can be deployed locally; anyone can deploy their own model. This directly shattered several labels attached to American AI: far ahead in technology, massive funding, closed models, and so on. A phenomenon emerged in the AI world: beating DeepSeek earns no reward, while losing to DeepSeek gets you killed outright.
The internet meme "kill line" precisely captures this state. DeepSeek did not "kill" American AI companies; it killed the certainty of "certain to win." The U.S. AI narrative degenerated from "America will definitely win, so unlimited investment is rational" to "America might win, so every investment needs to be recalculated." Capital can accept high risk, but it cannot accept uncertainty at the narrative level. When "they help whoever wins" becomes the default mentality of capital, hesitation turns into retreat: investment that is not absolute equals no investment.
The U.S. midterm elections in November 2026 happened to provide a political catalyst for this retreat. The Democratic sweep of Congress means the approval environment for data center expansion will shift from the "green channel of the Trump era" to the slow lane of "item-by-item review, community hearings, and environmental assessment." The "one-third of 2028 compute at risk" warned by UBS turned from a "tail risk" into a "base case" the moment the election results came out. So U.S. stocks completed their pricing with an epic sell-off: the Magnificent Seven tech giants together evaporated about $1.04 trillion in a single day.
The Essence of the Account Bans: "Resource Rationing"
Now back to OpenAI's account bans.
OpenAI's official explanation is that it is cracking down on the "anti-AI influence movement" and clusters of accounts associated with unsupported regions. These technical reasons certainly exist, but seeing only this layer misses the more important signal. If you place the account bans in the chain of "shrinking resource expectations—capital hesitation—compute reckoning," the logic becomes unusually clear: when incremental resources are no longer supplied without limit, the allocation of existing resources must be prioritized. And overseas accounts—especially those in regulatory gray areas, with complex payment chains and the highest political risk—are the group first squeezed off the rationing list.
This was not invented by OpenAI alone; Anthropic had already walked this path. In the second half of 2025, Anthropic banned 1.45 million accounts; during the same period it received 52,000 appeals, and only 1,700 were overturned. In 2026, it went further, requiring high-risk users to submit government identification and undergo facial verification—something holders of mainland Chinese ID cards could almost never pass. Earlier, Claude Code was even reported to have built hidden identification logic into the client, judging whether a user was connected to China through local time zones and proxy domains, and hiding markers in system prompts sent back to the server. Members of Anthropic's technical team later acknowledged the existence of this mechanism, calling it an "anti-abuse experiment."
You can call this compliance, or you can call it risk control, but from the perspective of resource economics, it is an unspoken rationing system: in an environment where the growth curve of compute supply is forced to slow while compliance costs and geopolitical risks soar simultaneously, AI companies need to reserve limited inference capacity for users with the highest output per unit of compute and the least political friction. U.S. enterprise customers, government contracts, and those paying groups that will not trigger congressional hearings are clearly at the front of the priority list. Chinese-language users—whether because of third-party top-ups, sharing, or "coming from unsupported regions"—happen to form the tail most easily cut off in this priority chain.
Account bans are, in essence, the use of shrinking account permissions to match the contraction of resource expectations in the physical world. OpenAI and its peers cannot publicly say, "We don't have enough electricity, the political environment has changed, so please stop using it for now," but "unsupported regions" and "anti-abuse" provide a respectable technical exit.
Let the Bullets Fly a While
After the midterm elections, Trump posted on Truth Social saying he "100% supports superintelligence" and likened data centers to "gold," claiming that only foolish leaders would fail to recognize this. But the market reaction shows that investors no longer buy this rhetoric very much. National Economic Council Director Hassett tried to reassure the market, saying that already scheduled projects would not be affected by referendums, but even he had to admit that the new political majority "may intervene and create chaos."
On the Democratic side, Senator Warren is expected to become chair of the Senate Banking Committee, wielding subpoena power, and the probability is rising that AI executives such as Jensen Huang will be invited to Capitol Hill for a chat. The regulatory pendulum swinging from "deregulation and accelerated infrastructure" toward "review costs and constrained expansion" is almost a foregone conclusion.
And above all this hangs the most basic question: if the physical costs of AI ultimately have to be borne by ordinary people's electricity bills and water taps, and the identity of the "winner" is no longer certain, how long can capital's patience last? What UBS calls "one-third of compute at risk" and what Bernstein calls "only 35% credible" point to the same conclusion: the capital expenditure narrative of U.S. AI infrastructure is undergoing a hard landing from "faith-driven" to "cash-flow-driven."
OpenAI's account bans are merely a tiny, technical, yet highly symbolic action in this hard landing. It tells all developers and users who rely on overseas AI capabilities one thing: when resource expectations tighten, the first door to be closed is often the one farthest from the decision-making center.
As for "they help whoever wins"—the reason this line from the film Let the Bullets Fly endures on the Chinese internet is that it precisely describes the behavior pattern of capital when facing uncertainty. That kill line from DeepSeek did not sentence American AI to death; it merely turned "winning" from an established fact back into a hypothesis awaiting verification—and capital never pays in advance for a hypothesis.
Once a bullet flew from a machine room in Hangzhou with a training cost of $6 million, toward a compute center in Virginia, then toward a trading screen on Nasdaq, and finally landed in an account-ban email received by an ordinary Chinese-language user.
Disclaimer: This article is written based on publicly available information or information provided by interviewees, but Caigou Business Review and the author do not guarantee the completeness or accuracy of the information mentioned or displayed in the article, and it does not represent the position of any institution. If there is any infringement, please contact us for deletion. Under no circumstances does the information or opinions expressed in this article constitute investment advice to anyone.
▼
-END-
-
![]()
Thailand Begins to Settle Old Scores with Chinese Automakers
-
![]()
Why Did It Take smart Seven Years to Perfect a Small Car Priced at 99,900 Yuan?
-
![]()
Tesla's All-Electric Pickup Cybertruck Is About to Be Discontinued: 70,800 Units Sold in 33 Months, Production Line to Be Freed Up for Cybercab in Mid-2027
-
![]()
OpenAI Account Bans Are Just the Tip of the Iceberg: The "Reckoning" of AI Compute Is Unfolding Simultaneously in Washington and Wall Street
-
![]()
Multiphoton Microscopy Imaging Technology No. 55: Self-localized Ultrafast Pencil Beams for Volumetric Multiphoton Imaging
-
![]()
China and the US have already settled their AI competition—and it's not even close: Multiple US states move to halt data center construction
-
![]()
Huguang Shares: Revenue Down 8.05%, Profit Plummets 80.25% Amid Wave of New Designations, Gross Margin Falls 3.74 Points
-
![]()
BYD Executive Responds to Maserati Acquisition Rumors: BYD's Cars Are the Fastest in the World