Insta360: At the Dawn of a New Valuation Era
 09/17 2026
 437
【Tide Business Review/Text】
Approximately a week ago, Insta360 Innovation, a beacon of technological innovation, witnessed its stock price dip below the 100 yuan mark.
From a peak of 377 yuan over a year ago to its current level near 100 yuan, this shift has inevitably sparked discussions in the market. Concurrently, Insta360's financial report for the first half of the year revealed a similar downward trajectory, with revenue reaching 5.517 billion yuan in the first half of 2026, marking a 50.29% year-on-year increase. However, net profit attributable to the parent company plummeted to only 30.4073 million yuan, a staggering 90% decline year-on-year.
Where has the profit gone? What ails Insta360?
To address these two burning questions in the market, it's crucial to focus on two key aspects: firstly, how Insta360 has allocated its profits; secondly, how the market should perceive Insta360.
Recent market discussions have shed light on the matter, revealing that the profit depicted in Insta360's first-half financial report is largely a strategic decision. For instance, the company holds inventory worth 6.212 billion yuan and has invested over 1 billion yuan in R&D, accounting for nearly 20% of its revenue. Additionally, to mitigate supply chain fluctuations, Insta360 made strategic purchases of memory chips worth nearly 2 billion yuan.
From the traditional securities market perspective, this first-half financial report appears lackluster, with declining profit margins and high inventory levels fueling pessimistic sentiment.
But is this the full picture?
Perhaps the traditional "yardstick" used by the market fails to accurately gauge the true essence of this company.
When a company in the midst of transformation, shifting from a hardware-centric approach to a technological ecosystem, is still evaluated using the valuation model of traditional manufacturing, the misalignment extends beyond price to perception.
With all negative factors already factored in, Insta360 stands poised at the starting point of a new valuation era.
01 Great Companies Often Undergo "Valuation Rewrites"
A retrospective glance at business history reveals an intriguing pattern: nearly all great companies have experienced a "secondary valuation" by the market.
The initial valuation is frequently based on past successes, tinged with enthusiasm and bubbles. When the bubble bursts and stock prices plummet, the market is compelled to re-evaluate the company's intrinsic value. The second valuation truly delves into the company's core.
Amazon serves as a classic example.
In 2000, the dot-com bubble burst, and Amazon's market value evaporated by over 90%, with its stock price plummeting from a peak of nearly $200 billion to about $3.6 billion by year-end. Wall Street criticized and ridiculed Amazon's "long-termism" as a facade for "sustained losses."
Under the old framework, Amazon was perceived as an unprofitable online bookstore and an internet bubble with no future.
However, Bezos did not slash R&D or halt investments in logistics and technology. Under immense pressure, he channeled every earned penny into AWS (Amazon Web Services) and infrastructure.
Years later, when AWS's profits began to soar and Prime membership loyalty became a formidable moat, the market finally adopted a new yardstick.
They no longer measured Amazon by "retail profit margins" but re-priced it based on "cloud computing potential" and "user lifetime value."
Amazon's second valuation wasn't triggered by a sudden improvement but by the market's newfound ability to measure it accurately.
The same narrative unfolds with Tesla.
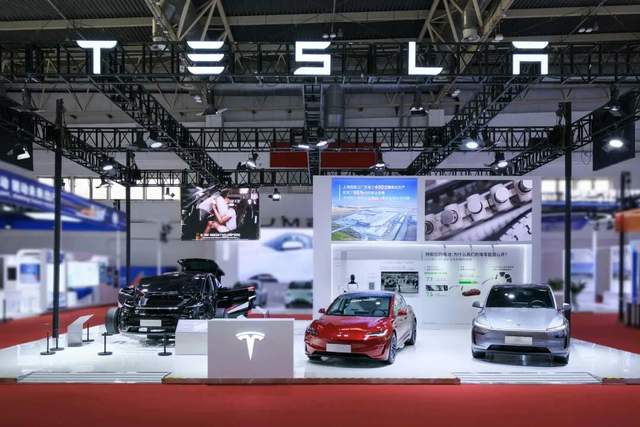
From being dismissed as a "PPT car-making" venture to becoming the world's highest-valued automaker, Musk endured ridicule, short-selling, and a decade of skepticism. For a considerable period, the market used traditional automakers' PE ratios to gauge Tesla, concluding it was severely overvalued and a massive bubble.
Until it dawned on people that Tesla wasn't merely selling cars but "AI + energy + software" mobile terminals. When FSD (Full Self-Driving) iteration speed outpaced all traditional automakers and the energy network closed loop gradually formed, the market's valuation logic underwent a complete overhaul (reconstruction).
Tesla's second valuation marked a perceptual awakening.
And then there's Netflix.
During its transition from DVD rental to streaming, Netflix's stock price plummeted by over 70%, users voiced loud complaints, and the media predicted its doom. Yet, Reed Hastings stood firm and persisted with the transition.
When streaming user numbers exploded and content became a core asset, the market finally re-priced Netflix using a "subscription-based + SaaS valuation" model. Its market value multiplied dozens of times.
These stories convey a universal truth:
Secondary valuation is the rite of passage for great companies.
It often entails painful crashes, prolonged doubts, and solitary perseverance. But it is this baptism that purges speculative capital and leaves behind the true long-termists.
02 An Old Yardstick Fails to Measure New Innovations
In the capital market's narrative, the valuation framework dictates asset pricing.
For an extended period, Insta360 has been pigeonholed by the market as a "consumer electronics hardware company." Under this outdated framework, the market's logic is simplistic and crude: focus on gross profit margins, net profit margins, inventory turnover, and PE (price-to-earnings ratio).
Applying this old yardstick to Insta360 naturally leads to a pessimistic conclusion.
Hardware is a challenging business, characterized by short product lifecycles, significant supply chain fluctuations, and razor-thin profits once embroiled in a price war. When Insta360's gross profit margin declined due to chip price hikes and strategic stockpiling, the old framework's alarm bells rang.
However, the blind spot of the old framework is its failure to recognize that Insta360 is not merely "selling hardware" but "building an ecosystem."
In the first-half financial report of 2026, a truth concealed by the profit statement emerged: Insta360's App monthly active users grew by 67%, and cloud storage paying users surged by 124%.
What does this signify?
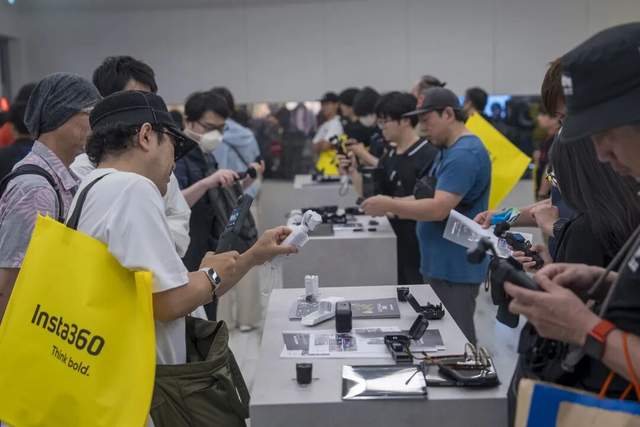
It indicates that Insta360 is transitioning from one-time hardware transactions to fostering long-term user relationships. With over 10 million devices shipped globally, these 10 million touchpoints are being transformed into high-frequency interactive digital assets. Overseas revenue accounting for 63.40% underscores its global market penetration.
From an SaaS (Software as a Service) or internet platform perspective, this 124% growth in cloud storage paying users represents Insta360's true "second curve." Yet, under the old yardstick, these growths are overshadowed by the decline in hardware profits.
The market is fixated on Insta360's "inventory," overlooking that in a tech company's balance sheet, "inventory" can sometimes be the "ammunition" for future growth.
When a company's core value is migrating from "hardware manufacturing" to "technology platform + user ecosystem," continuing to use PE for valuation is akin to measuring height with a weighing scale.
No matter how large the number, it's meaningless.
03 What Should Insta360's "New Yardstick" Measure?
Returning to Insta360.
With a 74% drop in stock price and a profit statement that appears unimpressive, this is precisely the opportune moment for the market to conduct a "secondary valuation."
So, what should the new yardstick for measuring Insta360 be?
Firstly, focus on the conversion rate of R&D investment, not absolute profit.
In the first half of 2026, Insta360 invested 1.036 billion yuan in R&D, accounting for nearly 20% of its revenue. To hardware companies, this is a profit-draining black hole; but to tech companies, it's the foundation for building barriers.
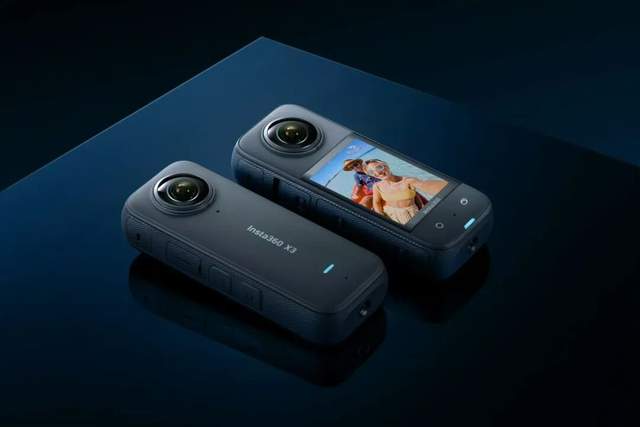
Insta360 is simultaneously advancing multiple new categories, including panoramic cameras, gimbal cameras, wireless microphones, custom chips, and drones. Each category demands underlying technological support.
The market should not inquire, "How much did you earn this year?" but rather, "Did each yuan of R&D investment create new value more cost-effectively than last time?"
If Insta360's optical, chip, and algorithm capabilities can be modularly reused, and if new products can leverage the advancements of previous ones, then this improvement in R&D efficiency is a more compelling metric than short-term profit.
Secondly, focus on the thickness of the user ecosystem, not hardware sales.
The vulnerability of the hardware business lies in the one-time realization of user value at the point of device sale.
However, Insta360's App MAU growth of 67% and cloud storage paying user growth of 124% indicate that Insta360 is cultivating a unique relationship with its users.
Which moments did users capture? Which automatic edits did they accept? How did they refine the results? These authorized, anonymized feedbacks are forming a profound understanding of user recording preferences.
The more users engage, the more accurate the understanding; the more accurate the output, the higher the retention; the higher the retention, the stronger the willingness to pay. This is a virtuous cycle.
The market should price Insta360 using "user lifetime value (LTV)" and "ecosystem stickiness," not "hardware shipments."
Thirdly, focus on the depth of technical barriers, not the breadth of product categories.
In the consumer electronics field, long-term leading technical barriers are rare. Chips can be reverse-engineered, functions can be imitated, and supply chains will eventually diffuse.
Insta360's moat lies not in the number of SKUs it offers but in its "ability to continuously create thresholds."
Identifying needs earlier, deploying technology earlier, and commercializing products earlier. By the time followers arrive, Insta360 has already moved to the next intersection.
This "time difference" premium is Insta360's true value.
Fourthly, focus on the organization's ability to evolve, not just scale expansion.
Insta360's management admitted in a letter to shareholders that the matrix organization had introduced issues such as reduced efficiency and slow bottleneck capability building. Now, they are reconstructing the organization by "business purpose" and "module," building shared capability platforms.
This is an extremely important signal.
After enterprise scale expands, high-quality collaboration becomes scarcer than technology and capital. Insta360 needs to achieve a state where the more products it has, the lighter the company feels.
If Insta360 can establish an internal "capability asset sheet" to track the reuse rate of common modules, the proportion of new products adopting mature modules, and the sunk costs of failed projects, then its innovation productivity is improving.
This is the cornerstone for supporting the next decade of growth.
04 Lay Down the Burden and March Forward Lightly
A stock price decline exerts pressure on management but is not necessarily detrimental to the company's long-term development.
High valuations often come with high expectations. To sustain a high stock price, companies may be compelled to pursue short-term profits, curtail long-term investments, and even distort their actions.
When the bubble bursts and the stock price returns to a reasonable range, companies can instead shed their burdens.
Speculative capital has departed, and the opportunities that remain are for long-termists who will accompany the company through cycles.
-
The Crux of AI Phones Resides in AI
-
![]()
Burying Yesterday's Expertise: An AI Self-Reflection by a DeepSeek Engineer
-
![]()
The Year's Most Unexpected "Power Couple": Not Sun Yuchen and Jing Tian, but Huawei and Seres?
-
Automotive Industry Major Reshuffle Countdown: Nine Departments Chart the Course for 2030, Weak Contenders Exit, Strong Ones Merge
-
![]()
Insta360: At the Dawn of a New Valuation Era
-
GAC Group’s Compelling Advantage: Exactly What FAW Seeks
-
Insta360: At the Dawn of a New Valuation Era
-
![]()
China’s Autonomous Delivery Vehicles Set Foot in Europe