POLYVISION's IPO Review: Persistent Decline in Gross Profit Margin and Weakening Industry Outlook
 10/27 2026
 360
Source: Xiaocaimi
Guangdong Polyvision Electronics Co., Ltd. (hereinafter referred to as "POLYVISION") is gearing up for an Initial Public Offering (IPO) on the Main Board of the Shanghai Stock Exchange. The Listing Review Committee of the Shanghai Stock Exchange is set to hold its 54th deliberation meeting for 2026 on October 27, 2026, where POLYVISION's application will be under scrutiny. 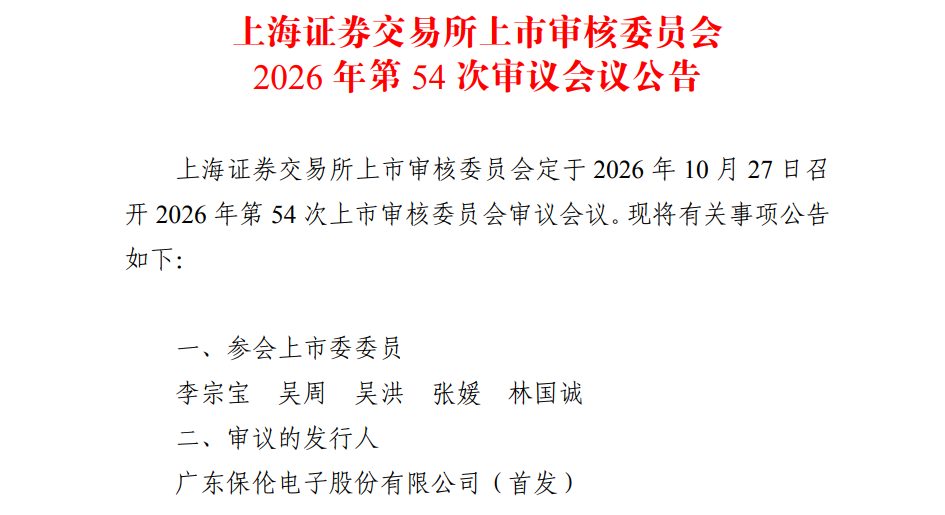
POLYVISION specializes in the research and development, manufacturing, and marketing of professional audiovisual products. Its product lineup includes public address systems, professional sound reinforcement systems, intelligent conference systems, display terminal systems, command and management systems, and lighting enhancement systems. All these products are marketed under the renowned "itc" brand.
During the reporting period spanning from 2023 to June 2026, POLYVISION recorded revenues of RMB 3,042,604,300, RMB 2,788,176,900, RMB 2,767,506,900, and RMB 1,093,297,500, respectively. The corresponding year-on-year growth rates were -8.36%, -0.74%, and +1.54%. Notably, the revenue demonstrated a downward trajectory over the full fiscal years, with a marginal increase of less than two percentage points in the first half of 2026 compared to the preceding year. During the same timeframe, the company's net profits stood at RMB 589,069,200, RMB 413,420,000, RMB 423,706,600, and RMB 86,177,800, respectively, with year-on-year growth rates of -29.82%, +2.49%, and +2.38%. A significant decline in net profit was observed in 2024. 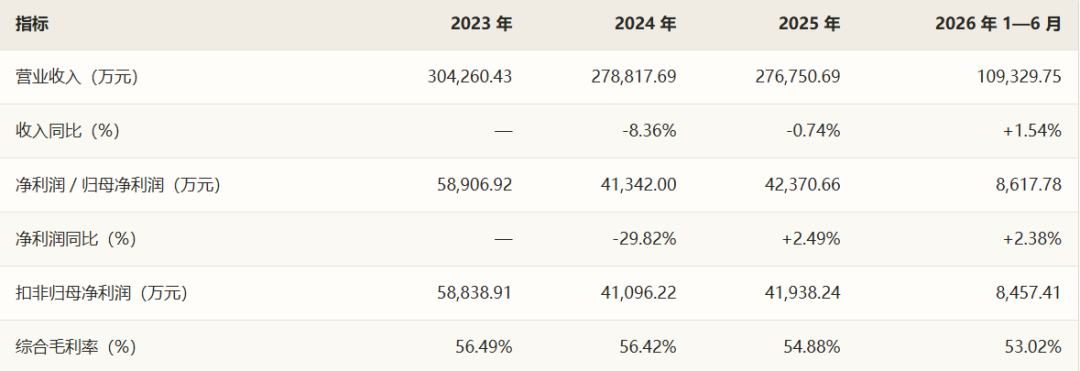
In aggregate, POLYVISION's revenue witnessed a cumulative decrease of 9.04% from 2023 to 2025, while net profit plummeted by 28.07% over the same period. Although net profit rebounded by 2.49% in 2025, this occurred amidst declining revenue and a reduction in gross profit amounting to RMB 54,241,500. The rebound in net profit that year was primarily attributable to a decrease in period expenses totaling RMB 65,874,300, which offset the decline.
In the first half of 2026, the company's revenue and net profit increased by a mere 1.54% and 2.38% year-on-year, respectively, while the gross profit margin continued its downward spiral. The company's overall gross profit margin dwindled from 56.49% in 2023 to 54.88% in 2025 and further to 53.02% in the first half of 2026. According to the prospectus, among POLYVISION's main products, the top three contributors—intelligent conference systems, professional sound reinforcement systems, and public address systems—accounted for 73.62% of the main business revenue in 2025 and generated approximately 79.61% of the main business gross profit. The contraction in revenue from these products had a profound impact on profits.
Specifically, revenue from intelligent conference products amounted to RMB 701,557,000 in 2025, marking a year-on-year decrease of 2.87% and representing 25.36% of the total revenue. The gross profit margin for these products stood at 57.37% that year. Despite an increase in sales volume, the average revenue per unit exhibited a downward trend. Revenue from professional sound reinforcement products reached RMB 693,137,300, showing a meager year-on-year increase of 0.28% and accounting for 25.06% of the main business revenue, with a gross profit margin of 61.50%. As the company's core high-margin product, its growth remained largely stagnant. Revenue from public address products was RMB 641,762,400, experiencing a year-on-year decrease of 11.04% and representing 23.20% of the main business revenue, with a gross profit margin of 59.11%. Revenue from these products has been on a continuous decline since 2023. 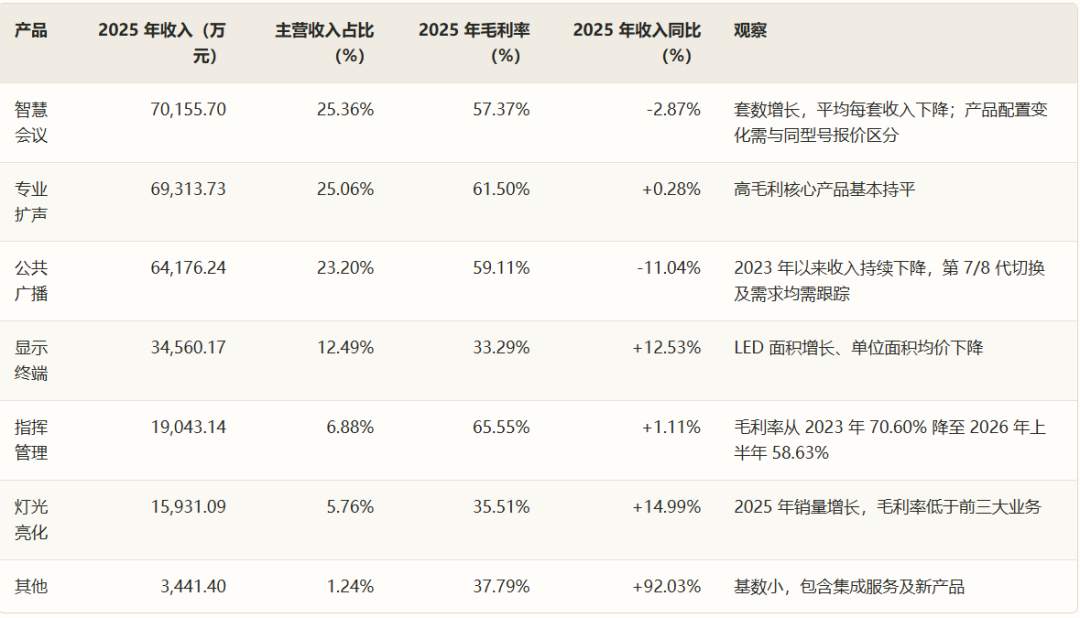
From an industry standpoint, AVIXA's 2025 Professional Audiovisual Industry Outlook projects global spending on professional audiovisual terminals to rise from USD 332 billion in 2025 to USD 402 billion in 2030. However, it has revised downward the previously forecasted five-year growth rate from 5.3% to 3.9% and highlights India as the leading growth market in the Asia-Pacific region. Against the backdrop of declining and stagnant revenue for POLYVISION's main products, coupled with a weakening industry outlook, the question remains: how will the company's future performance unfold?
-
![]()
Leapmotor’s Staff Increases by 9,732 in Just Over a Year. Can Zhu Jiangming’s ‘Mini BYD’ Outpace Geely and BYD?
-
![]()
Why Are AI Glasses So Popular, Yet Goertek's Q3 Sales Drop by 2.4 Billion Yuan with Inventory Reaching 22.4 Billion Yuan?
-
![]()
POLYVISION's IPO Review: Persistent Decline in Gross Profit Margin and Weakening Industry Outlook
-
![]()
Audi’s Strategic Split: SAIC-Audi’s Two-Year Plan Leads to Gasoline Vehicle Sales Until 2027 End | Mirror Pro
-
![]()
Racing to Become the "Pioneer Large-Scale Model Stock on the U.S. Stock Exchange": Anthropic Reports Over $80 Billion in Losses Within Half a Year
-
![]()
Wang Teng, Ex-Xiaomi Exec, Proves Prescient Half a Year Ago: Domestic Smartphone and Tablet Product Lines Face Discontinuation Wave
-
![]()
Post-2000s Female Employee Causes Stir at XPENG Launch Event
-
Anthropic Still Needs to Keep 'Sprinting'