The Largest IPO in History Has Officially Filed Its Application
 10/30 2026
 489
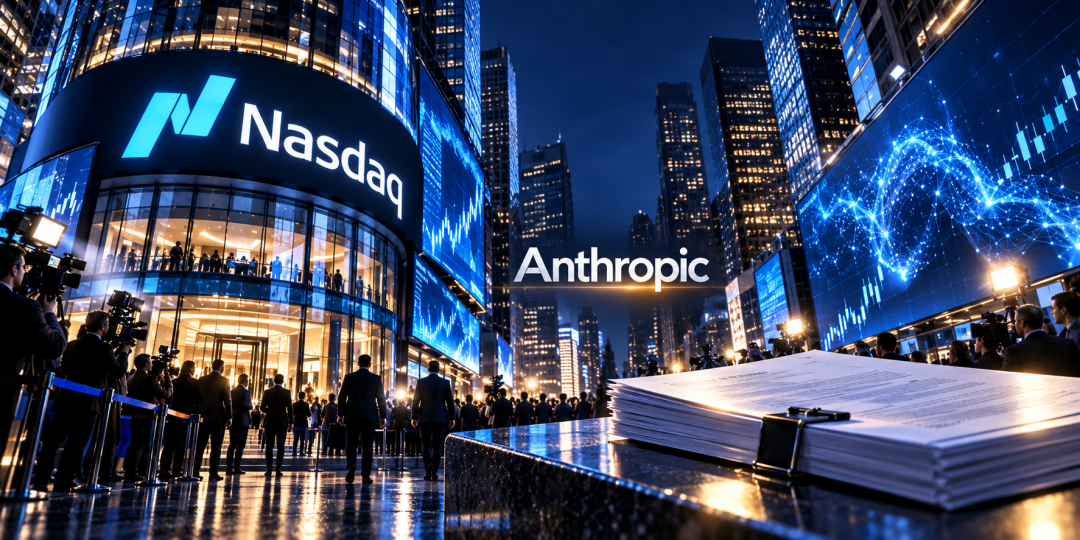
An AI company founded just five years ago is finally about to open its books to Wall Street. On October 26 local time, Anthropic—the developer behind Claude—publicly submitted its U.S. IPO registration documents, applying to list on Nasdaq under the proposed ticker ANT.
Two sets of figures in the prospectus stand out: revenue of approximately $16.3 billion in the first half of 2026, and a net loss of roughly $80.7 billion. The rapid revenue growth shows that large models have found customers willing to pay. The massive loss and long-term computing power contracts also reveal another side of this business: every step forward in the technology race requires capital, chips, and customer demand to keep the relay going.
As of October 27, the issue price, number of shares offered, and final valuation had not yet been announced. Public filing still leaves a long road ahead before an official listing.
What Are Investors Seeing?
Anthropic was founded in 2021, and its founding team includes Dario Amodei and Daniela Amodei, both formerly of OpenAI. The company develops the Claude series of large models, with revenue coming from personal subscriptions, enterprise services, and developer APIs. Its fundraising pace has accelerated in tandem with AI demand.
Funding Timeline: Round / Funding Amount / Post-Money Valuation — March 2025 Series E $3.5 billion $61.5 billion; September 2025 Series F $13 billion $183 billion; February 2026 Series G $30 billion $380 billion; May 2026 Series H $65 billion $965 billion.
In just over a year, the company's post-money valuation climbed from $61.5 billion to $965 billion. Investors are willing to pay high prices because they see the potential of AI entering scenarios such as enterprise office work and software development, and they are also betting that leading model companies can secure an important position. Private financing prices reflect investors' judgments about the future at the time. After moving to the public market, revenue, costs, customers, and cash flow will face more frequent scrutiny.
Revenue Is Growing Rapidly, and Enterprise Customers Have Become Key. Statistical Period / Operating Revenue — Full Year 2024 approximately $386 million; Full Year 2025 approximately $4.59 billion; First Half of 2026 approximately $16.29 billion. Note: 2026 is half-year data, while the first two items are full-year data, so the statistical periods differ.
In 2025, Anthropic's revenue was nearly 12 times that of the previous year. In the first half of 2026, the company's revenue had already exceeded three times its full-year 2025 revenue. Reuters reported that Claude already serves more than half of Fortune 500 companies. This business is moving from demonstrating capabilities to solving specific problems. Programming tools are one example: enterprises can hand generated code to engineers for testing and can also measure how much time a task saves. When products enter daily work processes, payments become more sustainable.
Enterprises also care about cost-effectiveness when paying. Fast answers are only the starting point; whether results are reliable, whether data is secure, whether the product can integrate with existing systems, and whether usage costs can be covered by efficiency gains will all affect renewals. Competition among large models has already entered one enterprise procurement list after another.
Behind the $80.7 Billion Loss
The net loss of approximately $80.7 billion in the first half is a very large number, but its meaning is easy to misread. First Half of 2026 / Metric / Amount — Operating revenue approximately $16.29 billion; Operating loss approximately $693 million; Net loss approximately $80.7 billion; Loss related to changes in fair value of financing instruments approximately $72.4 billion. Note: The metrics have different scopes and cannot simply be added together. Losses related to fair value changes include non-cash accounting effects.
Of the net loss, about $72.4 billion came from changes in the fair value of financing instruments such as convertible notes. Changes in the company's valuation affect the carrying value of related financial instruments. Therefore, this net loss cannot be directly understood as the company actually consuming the same amount of cash.
Changes in the main business are also worth watching. Reuters, citing the prospectus, reported that Anthropic's operating loss in the first half was about $693 million, narrower than about $2.14 billion in the same period a year earlier.
Revenue growth is improving operating performance, but the company still needs to prove whether this improvement can continue. Every time an AI company adds a batch of customers, it has the opportunity to earn more revenue, but it also needs to pay computing costs for model training and user calls. Whether revenue can consistently outpace costs determines how much profit ultimately remains from scale growth.
Computing Contracts Are Long, and Revenue Still Has to Catch Up
Beyond the current financial report, the market is more concerned about future computing bills. According to Reuters statistics based on the prospectus, Anthropic's computing and infrastructure expenditure arrangements with multiple partners total more than $600 billion, covering a period of about ten years.
Partner / Related Long-Term Expenditure Arrangements — Amazon at least approximately $110 billion; Google at least approximately $114.5 billion; Microsoft at least approximately $44.9 billion.
Note: Contract terms, constraints, and payment timing vary.
The above amounts are long-term arrangements and cannot be regarded as current expenses or cash already paid, nor should they be directly added together to estimate annual spending. Locking in computing power in advance has a business logic. Chips, data centers, and electricity all take time to build, and when customer demand rises, computing capacity must keep up. But at the moment the contracts are signed, future orders have not all been secured.
If user demand continues to grow, these investments have the opportunity to translate into service capacity; if growth is slower than expected, long-term spending commitments could put greater pressure on cash flow. Companies such as Amazon and Google are also investors and partners.
Industry collaboration can help Anthropic obtain capital and infrastructure, and investors also need to keep watching cooperation terms, customer sources, and capital flows to judge the quality of business growth.
Competition is also fierce. Companies such as OpenAI and Google are all advancing models and enterprise products. Models update quickly and customers have many choices, so today's technological advantage must be defended through continuous R&D and product experience. Security, intellectual property, and regulatory changes will also affect business expansion.
The Market Is Pricing In High Expectations
Reuters reported on October 26 that the valuation discussed by some existing and potential investors was about $1.5 trillion, while the market had previously discussed about $2 trillion.
Both are market expectations, not the IPO pricing announced by Anthropic. Valuation Reference / Amount / Nature — May 2026 Series H $965 billion disclosed post-money valuation; recent discussions among some investors about $1.5 trillion expected in media reports; final IPO valuation not yet announced, subject to official offering documents.
The fact that investors are willing to discuss such a high valuation means they are buying the future: enterprises will continue to increase AI investment, leading models can remain competitive, and revenue growth will ultimately translate into sustainable profit.
All these conditions need time to verify. The higher the valuation, the smaller the margin for error left for future performance. A good product can attract users, but good investing also requires considering the purchase price and future cash returns.
The AI Industry Steps in Front of the Public Market
Anthropic's prospectus submission gives a clearer public reference for the financial condition of a leading large-model company. If it lists successfully in the future, the market will continue to observe its revenue, profit, cash flow, and computing investment, and these data will also affect investors' understanding of the entire AI industry chain.
For the industry, bustling financing and impressive model demonstrations are now meeting more specific tests: whether products can truly help customers save time and generate revenue, and whether enterprises are willing to pay for them over the long term. AI has moved from technology demonstrations into real business settings. Next, technological capability will still determine how fast a company can go, while customer value and operating capability will determine how far it can go.
What do you think about this topic? We look forward to your civilized and rational comments in the message area.
Disclaimer: This article is only an analysis of financial hot topics. Data and materials are cited from public queries, company announcements, and Tonghuashun iFinD. The views are for reference only and do not constitute any investment or consumption advice. #FinancialHotTopics #InDepthInterpretation #BusinessFinance #InvestmentBankingCircle #ListedCompanies #PrimaryMarket #IPO #AI
-
Mercedes-Benz's All-Electric E-Class
-
![]()
The Largest IPO in History Has Officially Filed Its Application
-
![]()
Prefabricated Data Centers Are Suddenly Catching On
-
![]()
Two Contrarian Bets: Can Wang Tao Really Succeed Zuckerberg?
-
![]()
Diffraction or Scattering? The Two Physical Mechanisms Behind Stray Light in Optical Waveguides
-
![]()
Solid-State Batteries: Policy Targets 2030, but Industry Leaders Say the Technology Is Only at Level 4
-
AI Is About to Dismantle America's Internet Toll Booths?
-
![]()
Phone Sales Hit a Ten-Year Low While Prices Keep Climbing—What's Going On?