68% of Notebook Production Costs Tied to CPU, Memory, and SSD! Manufacturers Grapple with Tough Choices
 10/12 2026
 518
Kuaikeji, October 11th – A recent report from TrendForce reveals that the three key components—CPU, memory, and SSD—now constitute 68% of the material costs for a mainstream notebook priced at $900 (Kuaikeji note: roughly equivalent to 6,022 RMB at current exchange rates). This leaves manufacturers at a crossroads: should they raise prices, cut costs, or absorb the cost increases themselves? Projections indicate that global notebook shipments could experience a single-digit decline by 2027.
In the early part of 2026, notebook shipments held up reasonably well, thanks to an improved CPU supply situation, early stockpiling efforts by manufacturers, and consumers opting to upgrade their devices ahead of schedule. However, this uptick does not signify a genuine market recovery; rather, some consumers simply accelerated their planned upgrades, leading to a subsequent depletion in demand over the following quarters.
Making matters worse, the availability of low-cost inventory is dwindling, and manufacturers are now contending with across-the-board price hikes for CPUs, memory, and SSDs. TrendForce data indicates that during the third quarter of 2026, these three components made up approximately 68% of the Bill of Materials (BOM) for a $900 notebook.
Faced with these challenges, manufacturers are now confronted with three primary options: passing the cost increases on to consumers through higher prices, which could dampen demand; absorbing the costs internally to keep prices stable, thereby sacrificing profits; or reducing the device configurations to maintain current pricing, which would diminish the product's competitiveness in the market.
TrendForce forecasts that if CPU and memory prices continue to soar, global notebook shipments could see a shift from a low single-digit decline to a high single-digit decline by 2027. The current outlook assumes a low single-digit decline, but this is contingent on prices not escalating further.
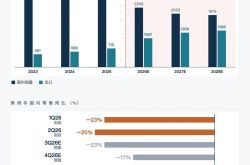
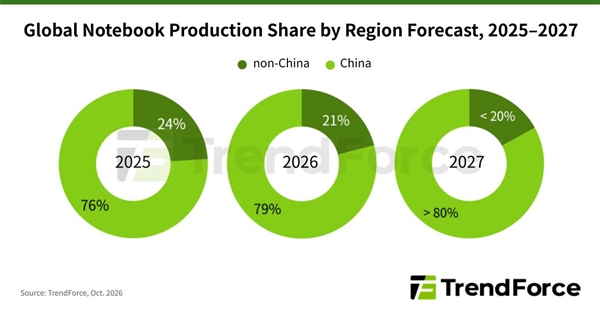
On the production front, adjustments are also underway. Rising production and supply chain management costs are prompting manufacturers to reconsider their manufacturing strategies. TrendForce predicts that the share of global notebook production capacity located outside of China will decrease from 24% in 2025 to 21% in 2026, with the possibility of dropping below 20% in the near future.
-
![]()
J.P. Morgan's 2027 Forecast for China's Auto Industry: Three Hurdles, Competing for Share in a Shrinking Market
-
![]()
Nominal vs. Effective Computing Power: Key Considerations for Autonomous Driving
-
![]()
Final Verdict: Unveiling the Scale of China’s Domestic Off-Road Vehicle Market
-
![]()
Geely Launches Global Dealer Recruitment Drive for Battery Sales!
-
AI Assistant: Beyond Mere 'Chatting'
-
![]()
68% of Notebook Production Costs Tied to CPU, Memory, and SSD! Manufacturers Grapple with Tough Choices
-
![]()
Young People’s Disillusionment with Mercedes-Benz and BMW: The Decline of the Premium Brand Pricing Model
-
![]()
Zunjie V800 Brake Pedal Bracket Base Upgrade Plan to Be Finalized by Month-End, With Upgrades Commencing in November