Why Are European and American Automakers Venturing into Diverse Sectors?
 09/29 2026
 433
From manufacturing missiles to engaging in energy storage, and competing for computing power contracts—what strategic motives underpin European and American automakers' ventures into seemingly unrelated sectors?
In recent years, the European and American automotive sectors have encountered challenges. On one hand, the demand growth for traditional fuel vehicles has plateaued, with European and American markets experiencing sluggish expansion. On the other hand, Chinese automakers, spearheaded by SAIC, Chery, and BYD, are aggressively expanding their global footprint.
Data underscores the industry's predicament. As of the first half of this year, the European STOXX 600 Automotive Index (SXXP AUTOS) has plummeted nearly 20%, marking it as the worst-performing sector for the year. Stock prices of several traditional automakers have halved from their 2021 peaks. Concurrently, data from the European Automobile Manufacturers' Association (ACEA) reveals that from January to May this year, the market share of gasoline and diesel vehicles in the EU market has dwindled to 30.1%, a 7.9 percentage point decline from the same period last year.
In stark contrast, from January to May this year, the market share of pure electric vehicles in Europe has surged to 20%, a 4.7 percentage point increase from the same period last year. By 2025, the average capacity utilization rate of European vehicle assembly plants is projected to reach only 55%. According to Bloomberg, European automakers may be compelled to close up to eight plants as a consequence.
Amidst these traditional automotive challenges, Europe's defense industry is experiencing a rare expansion phase. Following the Russia-Ukraine conflict in 2022, European nations have urgently bolstered their defense capabilities and indigenous military supply capacities. European Commission President Ursula von der Leyen stated that various projects would be leveraged to mobilize up to €800 billion in defense investment, signaling Europe's entry into an 'era of arms expansion.' The substantial demand for production capacity appears to align with the idle factories in the automotive industry, as if drawing a direct connection between them. Amidst this trend, major automakers are taking proactive steps, and a grand 'cross-industry military engagement' is unfolding.
The 'Arms Race' Among Automotive Titans
Renault initiated the 'first move' in the automotive arms race. In January this year, Renault not only partnered with military firm Turgis Gaillard to establish a drone production line at its main automotive chassis factory in Le Mans, France, but also collaborated with French defense technology giant Thales to develop dual-use military and civilian vehicles. At the Eurosatory Defense Exhibition, its hybrid all-terrain military reconnaissance vehicle, named 4 TROOP, was officially unveiled, showcasing its ability to swiftly militarize automotive platforms.
Similarly, Volkswagen has been reported to be in discussions with Israel's state-owned military enterprise Rafael Advanced Defence Systems, planning to fully transition a near-closing vehicle assembly plant from traditional automotive production to manufacturing components for missile defense systems. According to local media, the Osnabrück plant in Lower Saxony is a potential candidate for this capacity transformation. The objective is to retain all 2,300 jobs at the plant and sell the system to European governments. Currently, the German government is actively supporting this plan, and if workers agree to switch to weapons production, the relevant production lines could become operational within 12 to 18 months.
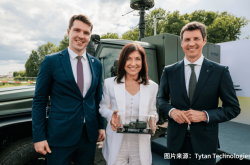
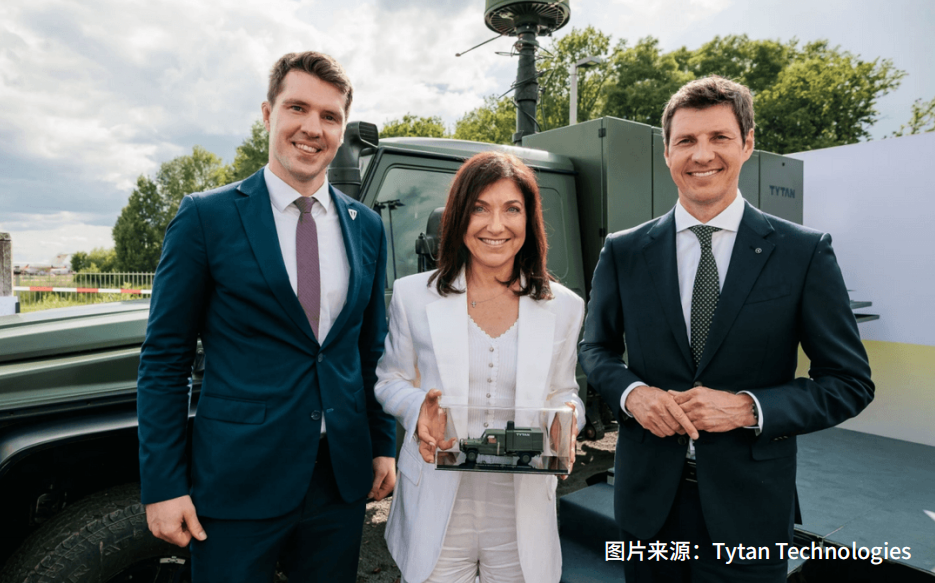
In addition, Mercedes-Benz Group announced in June this year its collaboration with German defense startup Tytan Technologies to construct mobile anti-drone combat vehicles based on the G-Class SUV and Sprinter van chassis. Mercedes-Benz CEO Ola Källenius stated that the group is willing to actively participate in defense equipment manufacturing as long as it holds commercial value. Across the ocean, General Motors is also in talks with U.S. military giant Lockheed Martin, planning to produce components for weapon systems such as the 'Patriot' missile and 'Tomahawk' cruise missile, aiming to replenish the ammunition stocks of the United States and its allies that have been continuously depleted due to multiline conflicts.
On the surface, this transformation appears almost logical. The automotive industry boasts the world's most sophisticated large-scale manufacturing system, with advantages in material handling, precision welding, complex supply chain management, and a reserve of skilled technical workers—all highly valued by the traditional defense industry. Historically, during the two World Wars, numerous cases of automakers fully transitioning to military production existed. However, despite frequent related news, analytical voices within and outside the industry remain remarkably composed. Some industry experts point out that automakers' transition to the defense sector is far from a 'panacea' for resolving capacity crises and even harbors profound contradictions in fundamental logic.
Firstly, the automotive industry is characterized by large-scale, platform-based, and standardized production modes. An ordinary automaker's annual output often reaches millions of units, enabling the amortization of high research and development costs and fixed investment costs only at such massive scales. In contrast, defense products are typically 'high-end customizations.' Taking missiles as an example, even at full capacity, the annual production of top-tier equipment like the Patriot or Tomahawk often numbers only in the hundreds to thousands, completely on a different scale from the automotive industry.
Secondly, automotive production is highly process-oriented and automated, relying on complex supply chains and assembly line rhythm control to pursue the highest efficiency and consistent quality within unit time. Defense production, however, is small-batch, highly customized, less tolerant of costs but extremely demanding on reliability, and orders are heavily influenced by geopolitics.
The two are akin to the difference between 'mass-produced ready-to-wear clothing' and 'high-end custom gowns,' with vastly different production methods, quality control systems, and research and development cycles. Germany's largest industrial union, IG Metall, explicitly states, 'The defense industry cannot absorb a large number of workers from the automotive industry, nor can it solve structural unemployment. Automotive production is mass-scale, while defense production is small-scale customization; the production modes are fundamentally different.' Relevant data shows that the European automotive and supplier sectors employ over 13 million people, while the entire European defense industry is expected to need only about 760,000 additional workers by 2030.
On the other hand, Europe lacks a unified defense market. Countries, out of national security considerations, have erected high walls in terms of bidding, export controls, and security certifications, which are incompatible with the automotive industry's globalized platform business model. Moreover, having industrial workers accustomed to manufacturing 'family cars' produce missile components inherently faces significant ethical choice pressures. According to Reuters, Volkswagen's cooperation with Israeli military enterprises once stalled due to objections from Qatar, a major shareholder with 17% voting rights (given its complex relations with Israel), highlighting the political sensitivity involved.
Therefore, some industry analysts jokingly refer to automakers' foray into the defense sector as an 'opportunistic self-rescue' approach of 'anything but cars.' Indeed, producing certain missile casings or assembly harnesses may temporarily preserve a near-closing factory and thousands of jobs, but it cannot provide the large-scale, stable, and continuous orders required by the automotive industry, nor can it fill the massive profit gaps caused by declining sales. Expecting defense orders to cure 'chronic illnesses' such as electrification pains, cost overruns, and declining competitiveness is undoubtedly just a desperate move by automakers.
Energy Storage as the Second Growth Avenue
When defense orders prove to be merely a drop in the bucket, another sector with higher technological homology to the automotive industry is bursting with potential, driven by the AI wave: energy storage.
In May this year, Ford announced a $2 billion investment to establish Ford Energy, a subsidiary that will directly shift capacity originally planned for electric vehicle production to manufacturing grid-scale energy storage systems comparable to Tesla's Megapack. General Motors followed suit, collaborating with startup Peak Energy to develop sodium-ion batteries specifically designed for grid energy storage while utilizing its joint venture with LG Energy Solution to mass-produce lithium iron phosphate batteries and actively deploy secondary utilization energy storage projects for retired electric vehicle batteries. Earlier, Volkswagen announced an additional €12 billion investment over the next three years in the power battery supply chain, building two new battery factories in Europe and simultaneously establishing a complete battery recycling system.
The core logic driving this transformation is the explosive growth in energy demand in the AI era. The operation of large language models like ChatGPT requires the consumption of hundreds of thousands of kilowatt-hours of electricity daily, meaning that future 'computing power factories' composed of hyperscale data centers will become unprecedented 'power behemoths.'
To ensure their stable operation, balance grid peaks and troughs, and even provide emergency support during power outages, energy storage systems are crucial. According to China Merchants Securities estimates, by 2030, the energy storage demand in the U.S. data center market alone could reach 122-245 GWh. For automakers seeking a 'second growth curve,' this represents a trillion-dollar market even broader than the automotive industry.
The idle production capacity in the hands of automakers can precisely meet this demand. On one hand, the technological foundation of shifting from automotive power batteries to grid-scale energy storage batteries belongs to the same category of chemical energy storage, with high commonalities in battery chemistry, module Pack, battery management systems, and even manufacturing processes, making the cost of technological migration almost negligible.
On the other hand, the growth potential and valuation space of being merely an automaker are tending to peak. For automakers like Ford and General Motors, which are relatively cautious in electrification, large-scale production can further dilute battery costs, forming a positive cycle. Tesla's success with Megapack has already proven the feasibility of this path. By 2025, Tesla's energy business revenue accounted for 13.5% of its total revenue, becoming its undeniable second pillar.
The Capacity Scramble Race Has Commenced
It is worth mentioning that while European and American automakers are tentatively laying out in the defense and energy storage sectors, a 'capacity scramble' race spanning the North American continent is unfolding along the U.S.-Mexico-Canada border.
On July 1, 2026, the review of the United States-Mexico-Canada Agreement (USMCA) reached a critical turning point: the United States announced its refusal to extend the agreement under existing terms. This decision has filled the agreement's long-term prospects with uncertainty and created negotiation conditions for the United States to raise the threshold for 'North American-made' rules.
According to The Wall Street Journal, the United States intends to increase the proportion of domestically produced components ('regional content level') required for vehicles to qualify for zero-tariff benefits from 75% to 82% and mandates that more than half must originate from the United States. This is undoubtedly a death sentence for all automotive giants outside the North American region.
In the past, 'where to build cars' was a cost calculation, but now it may mean a life-or-death decision. If these clauses are finalized, automakers will not only have to restructure their component supply chains but also extensively replace non-North American suppliers, leading to a significant short-term increase in component procurement costs.
Facing this existential regulatory upheaval, Stellantis Group has unveiled the largest investment plan in its century-long history for the U.S. market—$13 billion. This massive fund will be used to increase U.S. domestic vehicle production (planned to rise by 50%), restart factories, and create thousands of new jobs. Its goal is clear and explicit: to reduce reliance on imports from Mexico and Canada, have more Jeep and Ram models produced on the U.S. industrial belt, and avoid potential hefty tariff risks.
German luxury brands are also planning to transition from 'exporters' to 'local manufacturers.' Recently, BMW announced the completion of a $1.7 billion investment in its South Carolina plant, which will begin producing pure electric vehicles in the United States from the end of 2026. Mercedes-Benz stated that it will inject $4 billion into its Alabama plant in the United States over the next few years to promote localized production of its models and plans to invest over $7 billion in total in its U.S. operations in the coming years, while consolidating up to 500 jobs into a new research and development center in Atlanta.
Meanwhile, power battery enterprises are also accelerating their localized layout in North America. From Japanese and South Korean battery giants like Panasonic, LG, and SK On to Chinese power battery enterprises such as CATL, Gotion High-Tech, and Envision AESC, the total planned capacity has exceeded 200 GWh. This not only provides support for local automakers like Tesla, Ford, and General Motors but also targets the rapidly growing North American energy storage market.
Looking back from this historical turning point, the current dilemma of European and American automakers is essentially a profound self-rescue effort centered around revitalizing excess capacity and reusing idle capacity.
However, this so-called "capacity scramble" has never been a straightforward journey lined with rewards. Venturing into the military sector is merely a stopgap measure, a temporary fix that fails to address the underlying structural issues plaguing the industry. While the energy storage sector presents a promising second growth curve, it demands substantial long-term investment in resources and the gradual accumulation of capabilities. The North American capacity scramble, in particular, is a reactive move spurred by changes in trade regulations, yet it is fraught with significant policy and commercial risks.
The genuine path to breakthrough does not lie in "escaping the automotive industry" through speculative cross-industry ventures. Instead, it requires a return to the core principles of the automotive sector. Only by swiftly developing and delivering truly competitive products can companies solidify their positions amid the global industrial reshuffling.
Image: Sourced from the Internet
Article: Auto Review
Layout: Auto Review
-
![]()
What Cars Can You Buy with a 100,000 Yuan Budget? The Options Far Surpass Your Expectations
-
![]()
AI Fuels Wealth Creation, Shakes Up the Rich List
-
![]()
The Unveiling of 'Mega Project - Dawning 8000': How Cutting-Edge Computing Power Transforms Scientific Research
-
![]()
Why Are European and American Automakers Venturing into Diverse Sectors?
-
![]()
Has Geely Quietly Surpassed BYD Once Again?
-
![]()
The automotive chips that have seen the most significant price hikes are automotive-grade memory chips, with the cost per vehicle increasing by up to 6,000 yuan
-
![]()
Flash Charging Era Approaches: Geely and NIO Forge Strategic Alliance
-
![]()
Harmony Intelligent Mobility Alliance’s Suspected 2027 New Product Launch: AITO Excluded, Shangjie and Luxeed Set to Dominate the 300,000-500,000 Yuan Market Segment | Mingjingpro