US Lawmakers Attempt to Impose a Permanent Ban on Chinese Cars: 'Otherwise, Annual Sales Will Reach 1.9 Million Units'
 09/30 2026
 473
Lead
Introduction
Bans may shut doors, but they cannot sever genuine connections. If Chinese cars flood the US market, which current models do you think will be hit hardest? Clue: The Model Y and Camry are on the list.
The US auto industry is attempting something it is not entirely confident about—using legislation to permanently exclude Chinese cars from the country.
In early September, John Bozzella, CEO of the Alliance for Automotive Innovation, representing traditional Detroit automakers, wrote to lawmakers urging a 'permanent ban' on Chinese cars entering the US market.
From legislative measures to administrative actions, and from tariffs to technological blockades, the US is constructing an unprecedented containment net.
However, as Washington sharpens its knives, MarketCheck has issued a forecast that makes Detroit even more uneasy: If Chinese cars enter the US market without restrictions, annual sales could reach 1.9 million units within five years, capturing about a 14% market share.
This figure surpasses the retail share that South Korean brands have achieved in the US after nearly four decades of effort. Ironically, this forecast is not based on speculation but on data from the UK and Canadian markets, which have already opened their doors to Chinese cars.
In the UK, Chinese brands started with less than a 1% market share and approached 14% within four years. Canada replaced a 100% surtax with a 6.1% tariff plus quotas this year, but analysis indicates that demand will soon far exceed these quotas.
Thus, a sharp contradiction emerges: The more aggressively the US seeks to ban Chinese cars, the more it reveals its fear—and the more it fears, the more it underscores the real impact of Chinese cars.
Will the ban or the market surge arrive first? How long can the US market remain closed? And if it cannot stay shut, who will suffer the most?
01 Attempting a Permanent Ban on Chinese Cars
John Bozzella has called for a 'permanent ban' on Chinese cars entering the US market. What progress has been made?
The Senate version of the Connected Vehicle Security Act already has 51 co-sponsors, while the House version has over 100. The Biden administration implemented regulations in early 2025 effectively banning connected vehicle technologies linked to China from US passenger cars. Washington also maintains tariffs exceeding 100% on Chinese electric vehicles.
On September 24, Republican Senator Bernie Moreno and Democratic Senator Elissa Slotkin planned to use the 'unanimous consent' procedure to fast-track the bill but temporarily postponed the procedural vote.
The reason is straightforward: Republican Senator Rand Paul stood alone in opposition.
Under the Senate's 'unanimous consent' procedure, any single senator can block legislation. Slotkin said all Democrats support advancing the bill, with only one Republican opposed—'my understanding is 99 to 1.' But that single vote has temporarily halted the bill's fast-track.
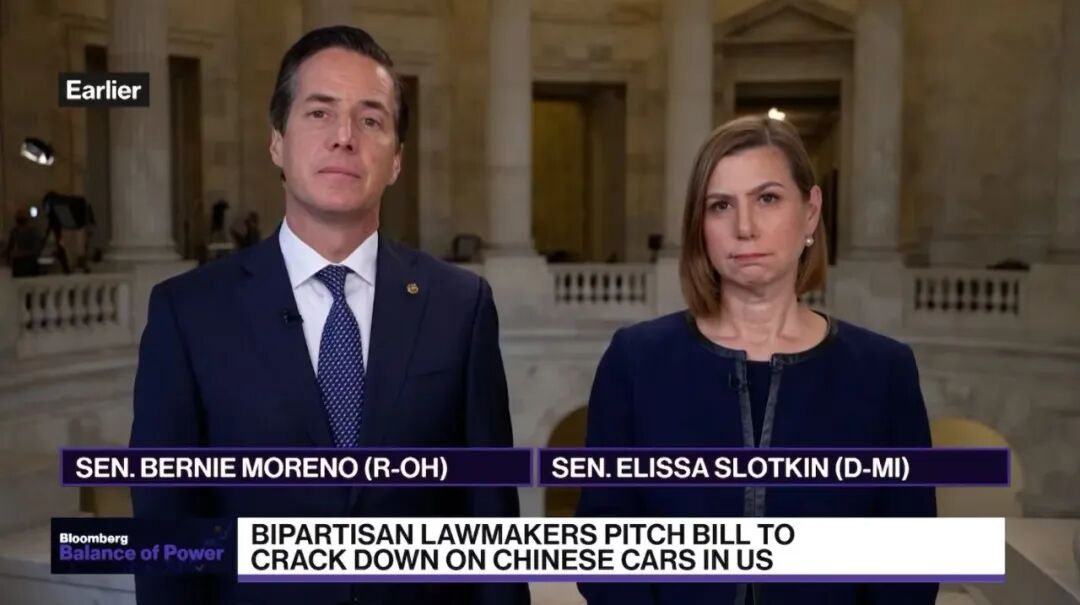
Moreno expressed hope that the bill would be approved the following week and push the House to pass identical legislation after it reconvenes in November. The problem is, time is not on their side.
What makes automakers even more nervous is Trump's stance. Earlier this month, Trump told Fox News he would allow Chinese automakers to build cars in the US. This statement raised alarms in Detroit.
Last week, automakers, suppliers, and dealers jointly urged Trump to 'maintain policies that keep the door closed to Chinese automakers, preventing them from selling, importing, or manufacturing vehicles in the US.'
Slotkin's statement was even more intense: 'I believe if President Trump allows these Chinese companies in, it will be the beginning of the end for the US auto industry.' As a representative from Michigan, she clearly feels pressure from her constituency and industry.
The bill's scope is also expanding. Senator Ted Cruz proposed banning companies with more than 15% Chinese ownership from selling vehicles in the US. This threshold could affect Mercedes-Benz—Chinese investors hold nearly 20% of its shares.
Moreno said Mercedes would have until 2030 to comply and could still obtain exemptions if needed. Slotkin said discussions on how Mercedes would comply are ongoing. This means the permanent ban targets not just Chinese brands but could reshape global automotive ownership and compliance structures.
With 51 Senate supporters, the bill would make the ban permanent and prevent the White House from granting exemptions to Chinese manufacturers for selling vehicles in the US. From the current situation, the US is just a few steps away from permanently banning Chinese cars.
But these steps will not be easy. China strongly opposes the move, and trade will naturally be a core issue when Trump meets with Xi Jinping.
Moreno said China produces nearly four times as many cars as the US, and Congress must ensure that hundreds of thousands of US auto jobs do not face the risk of being 'completely dominated' by Chinese companies. This sounds like industrial protection, but behind it lies naked fear.
02 Could Chinese Cars Sell 1.9 Million Units Annually in the US?
Fear is not unfounded. To understand what would happen if Chinese cars entered the US, the UK provides the best reference.
According to UK Department for Transport vehicle registration statistics, five Chinese brands held a combined market share of just 0.97% in the UK in 2021. By 2024, this figure had steadily risen to 2.94%.
The real breakthrough came in 2025: 14 Chinese brands led by MG, BYD, Jaecoo, and Omoda tripled their sales, capturing 9.29% of the market. By 2026, they are expected to hold nearly 14% of the market.
From less than 1% to nearly 10%, Chinese brands achieved this in just four years.
Geely's UK sales director told Car Dealer magazine in August that he expects Chinese brands to soon capture half of the UK market. This sounds exaggerated, but given the speed, no one dares to dismiss it lightly.
Canada provides another test case. In March, the Canadian government replaced a 100% surtax on Chinese-made cars with a 6.1% tariff and a 49,000-vehicle quota, increasing annually by 6.5%.
The Canadian market is roughly the same size as the UK, and these numbers are strikingly similar to those in the UK. According to MarketCheck's Canadian new vehicle sales data and referencing the UK experience, Chinese car sales could hit the quota ceiling by 2029.
By 2030, demand for Chinese cars is expected to reach 178,400 units—three times the quota. By 2031, this figure could rise to 265,900 units. Quotas can limit import volumes, but they cannot suppress demand.
When price, configuration, and product strength create an overwhelming advantage, consumers will vote with their wallets.
Applying the UK's rapid market entry strategy to the US auto market yields a sobering outlook. MarketCheck forecasts that Chinese automakers will sell approximately 217,000, 346,600, and 401,200 units in their first three years in the US.
In the fourth and fifth breakthrough years, sales will rise to 1.28 million and 1.9 million units, equivalent to 9.3% and 13.9% market shares, respectively.
What does 1.9 million units mean? This surpasses the current combined 11.4% retail share held by South Korean brands, which have been competing in the US market since 1986. It took Hyundai, Kia, and Genesis nearly four decades to reach this position, but Chinese brands could approach or even surpass it within five years.
Of course, this assumes 'no restrictions.' If the Connected Vehicle Security Act passes, if 100% tariffs remain, and if the 15% ownership threshold takes effect, these figures remain speculative.
But the value of analysis lies in showing the US auto industry just how significant the impact would be if the door opens.
Chinese automakers' strategy is no mystery: ultra-low prices, rapid dealership expansion, and value-packed configurations. Setting aside national security concerns, this unrestrained rapid market entry capability represents the greatest threat posed by Chinese cars.
Without high barriers in the UK market, Chinese brands proved themselves in four years. Canada imposed quotas, but demand is expected to triple them.
03 Would the Camry and Model Y Suffer Most?
In this projection, while some Chinese car sales in the US market would be incremental, most would come at the expense of established models.
MarketCheck's demand and elasticity model based on US retail sales data shows that 57% to 62% of Chinese car purchases would come at the expense of existing US market brands. Models priced between $25,000 and $45,000 would face the greatest impact—the core price range for mainstream US family vehicle purchases.
By sales volume lost, the five most affected models would be the Toyota Camry, Tesla Model Y, Tesla Model 3, Toyota RAV4, and Honda CR-V, each losing 10% to 16% of their current sales.
Other notable entries in the top 25 include a Japanese brand's pure electric model ranked 12th and a Korean brand's pure electric vehicle ranked 14th. Entry costs in this segment are already very high, with both losing 11% of their market share to Chinese cars.
By 2030 and 2031, displaced sales from other brands would reach approximately 721,000 and 1.07 million retail units, respectively. This means that within less than five years, 6 to 9 percentage points of market share would shift from existing models to this new entrant: Chinese cars.
Why is the US market so vulnerable?
Cars are already expensive, and inflation since 2020 has driven prices higher. According to MarketCheck's new vehicle sales data, the average US new car sticker price in August 2026 was $50,835, up from $40,898 in January 2020.
Meanwhile, entry-level brands have moved upmarket, leaving the low-end segment vacant. This is a natural product and market cycle: Japanese brands once did this, Korean brands took over the entry-level position, and now Korean brands are also moving upmarket, leaving the entry-level segment open again.
What about the Big Three US automakers? Ford and General Motors have already abandoned sedans to focus on pickups and SUVs, leaving more space for low-priced new entrants than ever before.
Worse, external conditions are changing rapidly. American love for fuel-efficient Japanese cars intensified after the 1973 oil crisis. Today, rising gasoline prices due to the Iran war are expected to accelerate electric vehicle adoption—which plays to China's strengths.
High interest rates and weakening consumer confidence will also challenge the US market, as car buyers shift to lower-priced models. In other words, the US market is pushing consumers toward Chinese cars on its own.
04 Can the Ban Stop Chinese Cars and Manufacturing?
So, can the ban block Chinese cars?
Legislatively, the US is approaching a permanent ban. The Senate bill has 51 supporters, the House version has strong momentum, and while Trump wavers, lobbying pressure from automakers and dealers is immense.
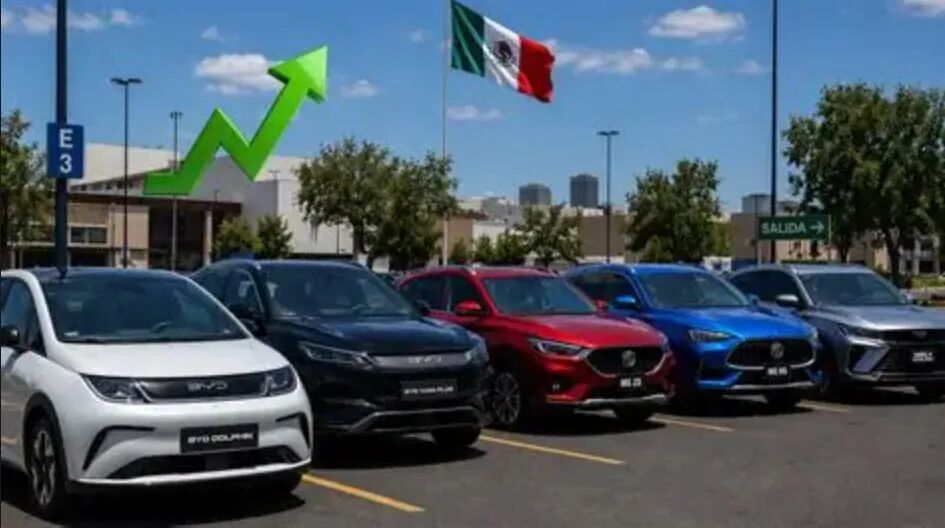
However, globalized supply chains and trade routes are difficult to completely block with a single wall. Mexican dealers are already selling Chinese cars, Canada imposed quotas but demand is expected to triple them, and Chinese brands approach 14% of the UK market.
Chinese automakers are already expanding across Europe, Southeast Asia, Latin America, and the Middle East. The US is just one piece of the puzzle. Even if the bill passes, Chinese cars could enter through third-country assembly, technology licensing, joint ventures, or other means.
More importantly, Chinese automakers' cost advantages and technological iteration speeds cannot be eliminated by a single ban.
The US auto industry has reason to worry. Chinese automakers are ready to enter aggressively, armed with price, speed, and product strength. If legislation does not act, significant market disruption is likely. But even if legislation acts, the disruption will only be delayed, not eliminated.
The real question is not 'Should we ban them?' but 'Is the US auto industry ready to compete?'
From the UK to Canada, from Mexico to the Middle East, the Chinese car offensive is already underway. How long the US market remains closed depends not on Washington's wishes but on the speed at which the global automotive industry restructures.
The forecast of 1.9 million units and 14% market share may not be a question of 'if' but 'when.'
The anxiety in Detroit and Washington has only just begun.
Editor-in-Chief: Shi Jie Editor: Wang Yue
THE END
-
![]()
New Breakthrough: GAC Group Reveals Plans to Purchase 50% Stake in FAW Toyota
-
![]()
Is an Extra 60,000 Yuan Worth It for L3 Autonomous Driving?
-
![]()
Leveraging DSec as a Framework? Unveiling How Muse Significantly Elevates CPU Demand
-
![]()
US Lawmakers Attempt to Impose a Permanent Ban on Chinese Cars: 'Otherwise, Annual Sales Will Reach 1.9 Million Units'
-
![]()
GAC Takes Stake in FAW Toyota: Good News for BYD and Geely
-
![]()
The RSI Craze Hits Embodied AI: Ideals, Realities, and an Unreachable Endpoint
-
![]()
Queen of Chips Teams Up with AI Godmother to Take on Nvidia's Huang
-
![]()
Changsha Offers a 'New Solution' to China's Robot Industry