A Staggering 4 Billion 'Deficit' Looms Large: Haima Automobile Faces Severe Challenges in Q3
 10/28 2026
 509
Authored by | Guanchejun
The automotive sector has been abuzz with numerous discussions lately, yet the quiet release of the first Q3 financial report from an A-share listed automaker may have gone unnoticed by many.
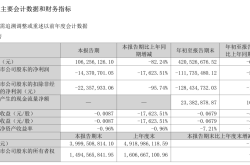
On October 27th, Haima Automobile, a seasoned player in the automotive industry, unveiled its Q3 financial results: a revenue of RMB 421 million, marking a year-on-year decline of 66.45%; quarterly revenue plummeted to just RMB 106 million, down 82.24% from the previous year. This downturn is far more severe than a mere 'halving' and can aptly be described as an 'ankle-severing' blow.
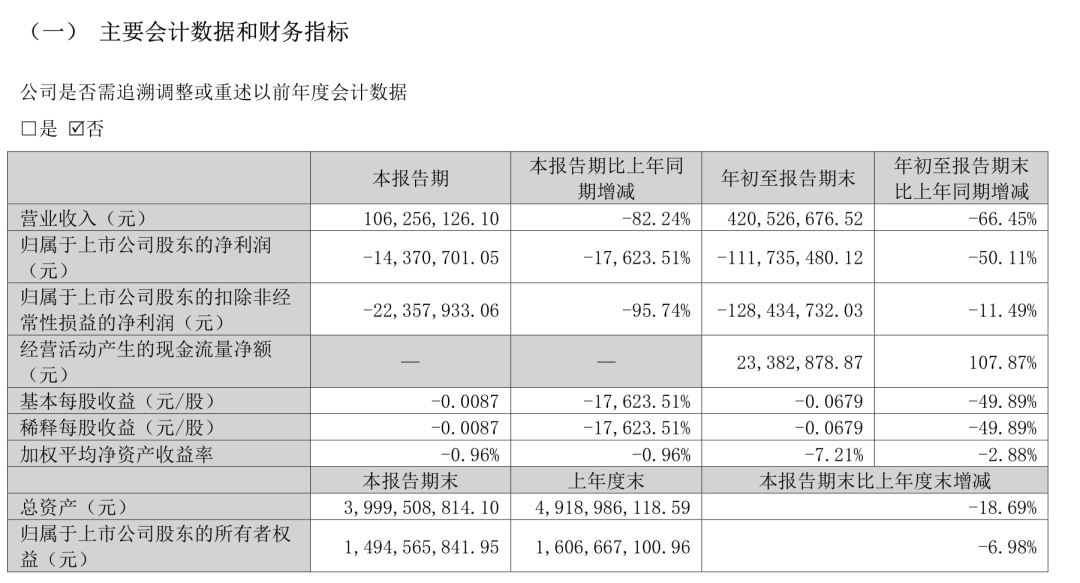
However, a closer examination of the data by Guanchejun reveals a complex financial landscape for Haima Automobile, characterized by two contrasting scenarios: on one hand, revenue is in freefall, while on the other, the company is desperately trying to stem the financial bleeding. What exactly is unfolding here?
01
Let's first delve into the revenue collapse. Over the first three quarters, Haima Automobile reported a net loss after non-recurring gains and losses of RMB 128 million, with basic earnings per share at -RMB 0.0679 and a weighted average return on equity of -7.21%.
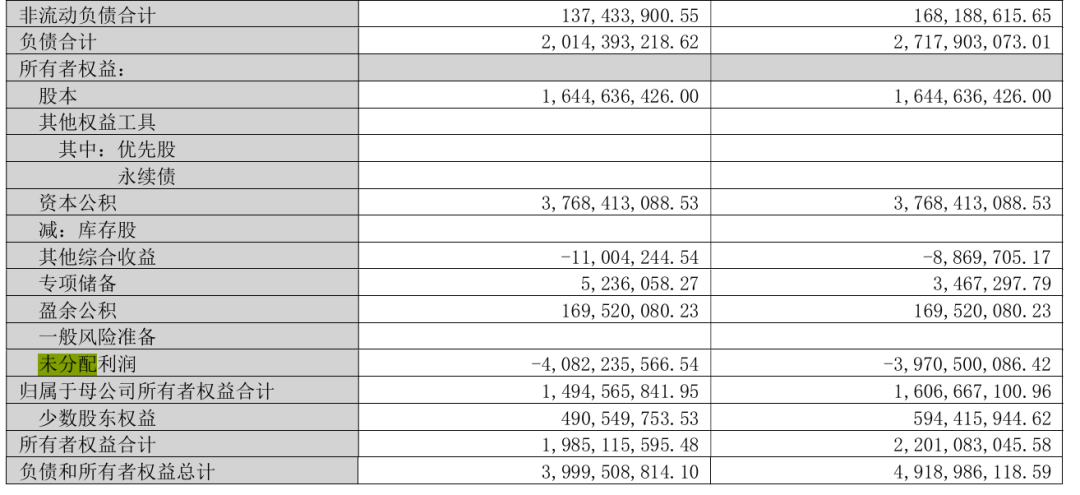
Total assets shrank from RMB 4.919 billion at the end of the previous year to RMB 4 billion, representing an 18.69% reduction. The undistributed profits column reveals a staggering deficit of -RMB 4.082 billion.
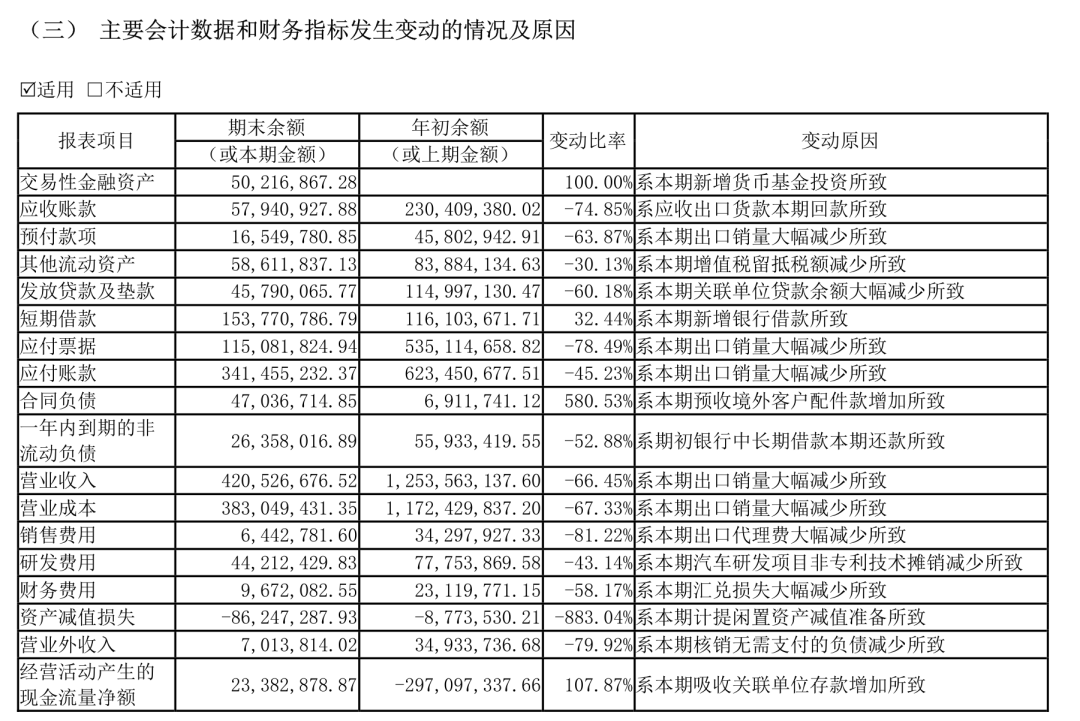
Upon analyzing the reasons for these changes, Guanchejun observed that the phrase most frequently cited in the announcement was: 'due to a significant decrease in export sales during this period.'
Consequently, in the first three quarters, Haima Automobile's prepayments decreased by 63.87%, notes payable dropped by 78.49%, accounts payable fell by 45.23%, and selling expenses decreased by 81.22%. All these indicators point to a stalled overseas sales performance.
According to public reports, in 2025, Haima's largest customer accounted for over 70% of its sales, with overseas revenue contributing over 80%.
As international situations fluctuate, Haima finds itself in a precarious position, akin to being in the ICU.
Additionally, in the first three quarters, Haima Automobile reported an asset impairment loss of -RMB 86.247 million, a year-on-year increase of 883%. The announcement attributed this to 'provision for impairment of idle assets.'
Idle production lines and devalued equipment have led to a 43.14% year-on-year cut in R&D expenses, leaving only RMB 44.21 million. For an automaker aspiring to transition to new energy, the shrinking R&D investment is a more alarming sign than the losses themselves.
02
Now, let's shift our focus to the efforts to stem the financial bleeding.
Firstly, the operating cash flow has turned from negative to positive. In the first three quarters, Haima Automobile's net cash flow from operating activities was RMB 23.38 million, a year-on-year improvement of 107.87%, compared to -RMB 297 million in the same period last year. The operating cash flow in Q3 was approximately RMB 159 million, marking a positive trend for two consecutive quarters.
Automotive losses are narrowing sequentially. In Q3, Haima's net loss attributable to the parent company was significantly lower than in Q2. Moreover, the gross profit margin is also on the rise: in the first three quarters, the comprehensive gross profit margin was 8.91%, a year-on-year increase of 2.44 percentage points, and in Q3, it reached 14.31%, a notable year-on-year surge.
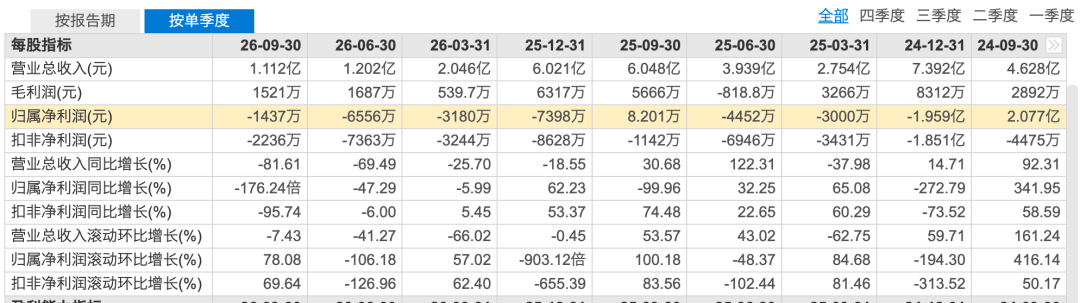
Guanchejun noted that in the first three quarters, Haima Automobile's combined sales, administrative, R&D, and financial expenses decreased by nearly RMB 100 million year-on-year, indicating that management has truly tightened its belt.
Lastly, there's still a narrative to unfold. Haima is the sole enterprise in the Hainan Free Trade Port with production qualifications for fuel vehicles, pure electric vehicles, and hydrogen energy vehicles simultaneously. The battery-swap model EX02 has completed engineering development and entered the product announcement phase. Cooperation with Toyota on hydrogen fuel technology continues, with a focus shifting to next-generation models.
03
In summary, from Guanchejun's perspective, Haima's Q3 report paints a vivid picture of a seasoned automaker struggling amidst a retreating market tide: revenue has collapsed, yet the structural framework remains intact; losses persist, but cash flow is showing signs of improvement (hemostasis); the story is still unfolding, but the audience is dwindling.
Haima Automobile's revenue of RMB 421 million in the first three quarters, in the context of the 2026 Chinese automotive market, cannot be considered 'small and beautiful' but rather 'small and precarious.'
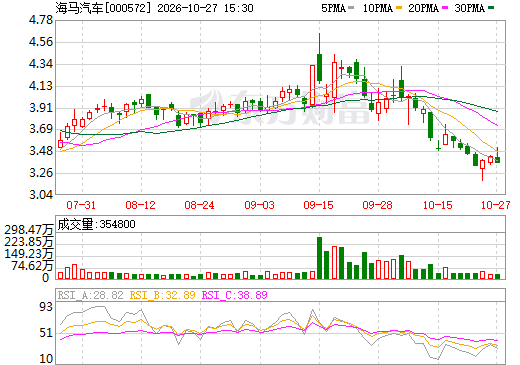
When the '15th Five-Year Plan for the Development of the Intelligent Connected New Energy Vehicle Industry' was unveiled in mid-September, Haima Automobile's stock price surged on the back of hydrogen energy and battery-swapping concepts. It is said that leading automakers in the industry rely on scale and technology, while those at the tail end depend on asset disposals and policy support.
Does Haima Automobile still have a chance to turn its fortunes around? Is it awaiting an ace in the form of asset restructuring, or will it fade away from the mainstream automotive market? The clock is ticking for Haima to prove its mettle.
Unless otherwise stated, the charts in this article are sourced from publicly disclosed information through various channels. We hereby acknowledge and express our gratitude. The views expressed in this article are for reference only and do not constitute investment advice.
This article is original content from Leverage Auto Observations and is prohibited from being reproduced without authorization. If reproduction is required, please obtain authorization. Additionally, when authorized for reproduction, please indicate the source and author at the beginning of the article. Thank you!
-
![]()
Anthropic Also Eyes Cloud Provider Partnerships
-
![]()
Can the ZON 09, Priced from 169,900 Yuan, Strike a Balance Among Model 3, Xiaomi SU7, and Itself?
-
![]()
What's Ailing XPENG?
-
![]()
From Recommendation to Mandatory: The Countdown Begins for C-V2X's 'Birth Certificate'
-
![]()
The Auto Market Price War: A Call for an Immediate Halt
-
![]()
A Century-First: Audi Unveils Dual-Brand Strategy, with Chinese Tech Pioneering Its Future
-
![]()
Chery Sets Sights on North American Market
-
![]()
A Staggering 4 Billion 'Deficit' Looms Large: Haima Automobile Faces Severe Challenges in Q3