Sunway Communication Doubles Down on High-End MLCC Amid Net Profit Decline, Despite Target's Losses and Domestic Breakthrough Challenges
 09/29 2026
 552
Sunway Communication (300136.SH) is making a strategic push into the high-end MLCC sector, with its wholly-owned subsidiary set to acquire a 55% stake in Sunway Electronic Technology (Yiyang) Co., Ltd. (hereinafter referred to as "Yiyang Electronic Technology") for RMB 1.1 billion.
Securities Star has observed that, despite the sector's attractiveness, the target company's financial health is less than promising, with cumulative losses of RMB 275 million over the past 18 months. This is particularly concerning given Sunway Communication's own declining net profit, raising questions about whether this acquisition can serve as a new growth engine for the company. Considering the entrenched nature of the global MLCC market, which is unlikely to undergo significant change in the near term, the target company faces substantial hurdles in achieving a domestic breakthrough.
Beyond the acquisition, Sunway Communication's plan to raise RMB 6 billion through a private placement for expansion has also drawn market attention. However, given the low share of orders and revenue from related products such as satellite communications and RF devices, there are doubts about the company's ability to effectively utilize the new capacity. Furthermore, the decision by the company's controlling shareholder to reduce holdings during the private placement period has sparked controversy.
01. Target Company Struggling Financially, Project Progress Lags Behind Expectations
Public information reveals that Sunway Communication's core businesses encompass antennas and modules, wireless charging modules and related products, EMI/EMC devices, high-precision connectors, acoustic devices, automotive connectivity products, and passive components, with applications spanning consumer electronics, commercial satellite communications, smart cars, IoT/smart home, and other sectors.
The acquisition announcement stated that, in response to the rapidly growing global demand for high-end MLCC products and to accelerate its strategic布局 (layout) in the high-end MLCC business, Sunway Communication's wholly-owned subsidiary, Yiyang Sunway, plans to utilize its own or raised funds to acquire a 55% stake in Yiyang Electronic Technology. Upon completion of the transaction, Yiyang Sunway will hold a 70% stake in Yiyang Electronic Technology, which will then be consolidated into the company's financial statements.
The target company operates in a high-potential sector, focusing on consumer electronics, AI computing power, smart cars, and other areas. It aims to achieve import substitution of high-end chip multilayer ceramic capacitors (MLCCs) through independent development of ceramic materials.
As of the evaluation benchmark date of June 30, 2026, the book value of Yiyang Electronic Technology's net assets stood at RMB 916 million. The income approach valuation yielded a total equity value of RMB 1.43 billion for shareholders, representing a 56.08% premium, with the transaction price set at RMB 1.1 billion.
Securities Star notes that the target company's profitability is a cause for concern. In the first halves of 2025 and 2026, its revenues were RMB 61.1502 million and RMB 126 million, respectively, with net losses of RMB 183 million and RMB 92.4102 million, respectively, resulting in cumulative losses of RMB 275 million over the past 18 months.
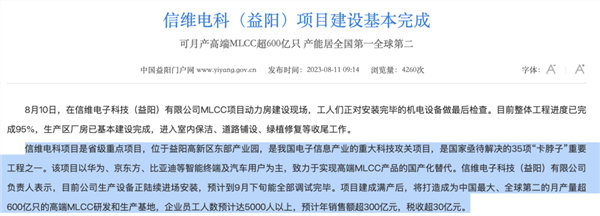
More notably, the target company's project progress has fallen short of expectations. In August 2023, the China Yiyang Portal reported that the Sunway Electronics project, led by Yiyang Electronic Technology, was expected to be fully operational by late September. Once at full capacity, the project aimed to become a high-end MLCC R&D and production base with a monthly output exceeding 60 billion units, estimated annual sales revenue exceeding RMB 30 billion, and taxes exceeding RMB 3 billion. Comparing these figures with current performance reveals a significant gap between actual progress and initial plans.
Despite Yiyang Electronic Technology's losses, Sunway Communication remains optimistic about its future development.
The company believes that the MLCC industry, in which the target operates, is experiencing a structural upswing. As capacity utilization and the share of high-end products increase, its gross margin is expected to gradually improve. With the explosive growth in demand for high-performance MLCCs from AI servers, this acquisition will accelerate the company's business breakthroughs in high-end passive components and represents a crucial strategic choice for its second growth curve.
It should be noted that the global MLCC market, dominated by Japanese and South Korean companies, is unlikely to undergo significant change in the short term. The top five companies—Murata, Samsung Electro-Mechanics, Taiyo Yuden, TDK, and Kyocera—collectively hold over 70% of the market share. Yiyang Electronic Technology faces multiple barriers, such as improving yield rates and obtaining customer certifications, to achieve a domestic breakthrough. Meanwhile, the target's ongoing losses will also exert pressure on Sunway Communication's net profit.
02. Exchange Losses Erode Net Profit, Private Placement's Capacity Absorption Uncertain
Securities Star has observed that Sunway Communication's current profitability is under pressure. In the first half of 2026, the company achieved revenue of RMB 4.032 billion, up 8.88% year-on-year, reversing the decline seen in the same period last year. However, net profit attributable to shareholders fell by 6.99% to RMB 150 million. Due to increased cash outflows from purchases, the net cash flow from operating activities declined by 59.18% year-on-year to RMB 440 million.
Notably, while the company maintained steady growth in Q1, the net profit decline in the first half was primarily driven by Q2's performance, with net profit attributable to shareholders in that quarter falling by 45.89% to RMB 43.3995 million.
The significant increase in financial expenses was the main reason for the decline in net profit in the first half of 2026. With a high proportion of overseas revenue, the company generated RMB 2.745 billion from overseas markets in the first half, accounting for 68% of total revenue. Meanwhile, exchange rate fluctuations resulted in exchange losses, leading to a substantial increase in financial expenses and, consequently, a significant impact on current net profit.
In the first half of 2026, the company's financial expenses surged by 204.09% year-on-year to RMB 84.3054 million. During the same period, administrative and selling expenses also increased by 4.04% and 7.73% year-on-year, respectively, reaching RMB 198 million and RMB 34.6588 million.
Losses from previously acquired target companies also impacted Sunway Communication's net profit. The antenna supplier Sunway Chuangke and electronic component company Jiangsu Ju Yongchang Electronics, acquired earlier by the company, have underperformed. In the first half of 2026, these two subsidiaries reported net losses of RMB 19.487 million and RMB 19.0778 million, respectively.
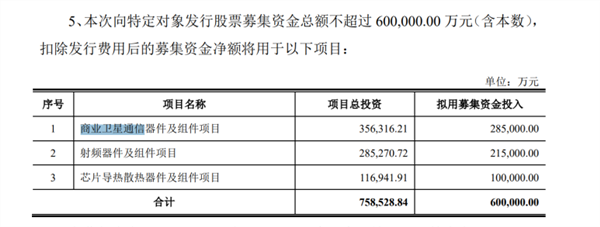
Securities Star notes that while deepening its presence in the communications and consumer electronics industries, Sunway Communication is expanding into downstream markets such as commercial satellite communications and smart cars. Against this backdrop, the company launched a RMB 6 billion private placement plan and secured CSRC registration approval in May this year. The prospectus revealed that the proceeds would be invested in three areas: commercial satellite communication devices, RF devices and components, and chip thermal management devices.
Data disclosed shows that related products from the private placement projects are still in their incubation stage, with their market potential yet to be validated. From January to March 2026, revenue from products related to the private placement projects was just RMB 347 million, accounting for 17.42% of total revenue.
In terms of orders on hand, as of the end of March 2026, orders for products related to the private placement projects totaled 84.8164 million units/sets, representing just 9.93% of the annual production capacity of 853.75 million units/sets upon project completion—a relatively low share. Given the current revenue and order volumes, uncertainty remains over whether Sunway Communication can fully absorb the new capacity from the private placement projects.
Notably, during the private placement period, the shareholding reduction by Peng Hao, the company's controlling shareholder, chairman, and general manager, has raised questions. From April 20 to April 21, 2026, Peng Hao reduced his holdings by 9.6375 million shares via block trades at an average price of RMB 77.5 per share, cashing out a total of RMB 747 million. (This article was first published by Securities Star, Author | Li Ruohan)
-
![]()
Save up to 12,000 RMB in Car Purchase Subsidies: Here's What You Need to Know
-
![]()
NIO and Geely Forge a 'Strategic Alliance'
-
![]()
Shenlong Technology Achieves in Just Over a Month What a 40-Year Joint Venture Couldn't
-
![]()
New Energy Vehicles Face a 'Scale Dilemma': Wan Gang and Zhu Huarong Offer Solutions!
-
![]()
What are the Eight Redundancies for L3 Autonomous Driving in the Qijing GX7?
-
![]()
Can Huawei’s Four ‘Jie’ Brands Maintain AITO’s Momentum? Who Will Lead the Charge?
-
![]()
Can Yi Jing and Qi Jing Replicate Aito's Triumph and Achieve Blockbuster Status with Major Automakers and Huawei?
-
![]()
Sunway Communication Doubles Down on High-End MLCC Amid Net Profit Decline, Despite Target's Losses and Domestic Breakthrough Challenges