Global Constellations, Terrestrial Business
 10/13 2026
 371
In India, Musk is gearing up to take on Ambani, despite having inked a Starlink distribution deal with him just last year.
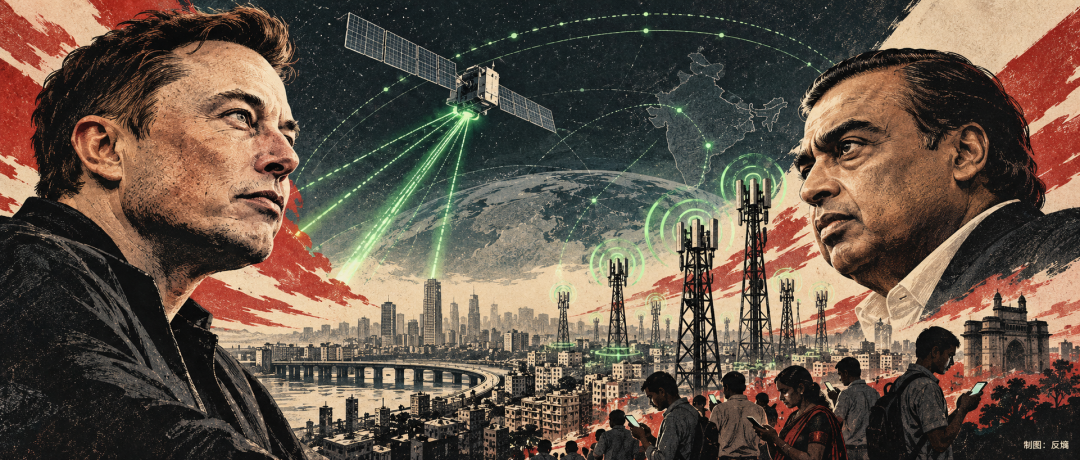
On October 11, Reuters reported that Musk emphasized the need for Starlink's pricing in India to be consumer-friendly. With local mobile data costs hovering around $0.08 per GB and Ambani's Jio boasting a customer base exceeding 500 million, and its parent company, Jio Platforms, gearing up for a significant IPO, Starlink has yet to unveil its pricing strategy. Moreover, its entry into the Indian market hinges on final security reviews and spectrum allocation processes.
While communication technologies continually surmount distance barriers, they remain tethered to costs and market demand. Following decades of extensive infrastructure development, terrestrial communication has driven data prices to unprecedented lows. Although satellite internet expands network reach, it must also grapple with the entrenched cost and pricing advantages of terrestrial operators.
India has thrust this competition into the spotlight. For Chinese companies ramping up their network deployments, China's well-established communication networks, manufacturing prowess, and diverse industry demands offer fertile ground for growth.
01 The Story Behind the Eight Cents
In 2016, Jio made waves in the Indian market with its free voice services and aggressive data promotions, subsequently expanding its terrestrial network. Data from India's Telecom Regulatory Authority (TRAI) reveals that in the first quarter of 2026, mobile data users consumed an average of 26.7 GB per month, with operators generating an average revenue of 7.51 rupees per GB. The $0.08 per GB figure cited by Reuters serves as a benchmark for mobile data pricing in the market; while statistical methodologies may vary, both underscore the exceptionally low local data pricing.
These low prices are underpinned by robust infrastructure. In densely populated regions, a single base station can cater to a vast user base, with new customers continuously diluting equipment and site costs. While satellites can circumvent geographical obstacles like mountains and oceans without the need for laying fiber, they incur significant costs for manufacturing, launching, network replenishment, and ground facilities, while households must invest in dedicated terminals.
Beyond costs, satellite internet grapples with network capacity limitations.
In May 2025, TRAI Chair Rahoti cited Delhi as a case in point: the city had approximately 5 million broadband connection demands, but a single satellite constellation could only accommodate about 10,000 to 20,000 connections at that time. While telecom operators contest these capacity estimates, the disparity has become a focal point in discussions on the competition between satellite communications and terrestrial networks in India.
Although satellites offer extensive coverage, the number of clients they can simultaneously serve in densely populated urban areas is relatively constrained.
In sparsely connected rural regions, user affordability poses a significant hurdle. Rural India has about 48 internet subscribers per 100 people, compared to approximately 127 in urban areas. Deploying satellite broadband for communal facilities like schools, medical centers, or community centers may prove more cost-effective than selling terminals to individual households. These scenarios also echo in the 2025 cooperation pact between Airtel and SpaceX.
TRAI has unequivocally positioned satellite communications as a complement to terrestrial networks. For Starlink, regions where terrestrial network construction costs are prohibitively high are more likely to represent economically viable markets.
02 China Market: Satellite Communications' Launching Pad
China's terrestrial communication networks are highly advanced. By the end of August, the country boasted 5.195 million 5G base stations and 1.23 billion fiber-optic access ports. This mature communication infrastructure has significantly slashed public internet costs and laid the groundwork for integrating satellite and terrestrial networks.
In China, satellite communications cater to clear national strategic imperatives. China StarNet spearheads national satellite internet infrastructure construction, with long-term public value in national communication security, autonomy, and spectrum resource allocation. Meanwhile, commercial satellite enterprises are extending communication capabilities to real-world industrial scenarios.
The domestic market provides a conducive environment for developing satellite communications.
China boasts a vast shipping fleet, automotive industry, and energy infrastructure, coupled with burgeoning demands for aviation communications and emergency rescue. Ocean-going vessels require uninterrupted connectivity, remote mining and energy facilities necessitate equipment remote management, and vehicles can transmit emergency information via satellite when terrestrial networks fail. These demands are bolstered by relatively mature procurement systems and application environments.
Network capabilities required vary across different scenarios.
As of September 16, the Qianfan constellation had deployed 256 satellites, primarily for broadband communication and internet access. As the constellation expands, its broadband capabilities will cater to maritime, aviation, and remote areas' high-speed connectivity needs. For such services, stable network capacity, efficient terminal deployment, and long-term service contracts will collectively influence operational efficiency.
Geely's Time and Space Dao Yu (Timespace Daoyu) has completed Phase I of its 64-satellite constellation and secured commercial trial permits for satellite IoT services in August. Leveraging Geely's automotive supply chain, the company is advancing in-vehicle satellite communications and conducting engineering machinery application validation with Zoomlion. Cars and industrial equipment typically only need to transmit location, status, or emergency messages, making low-data, low-power connectivity suitable for large-scale terminal deployment.
From Qianfan's broadband communications to Timespace Daoyu's satellite IoT, Chinese companies are tailoring service capabilities to diverse industrial demands. As technology matures and terminal costs decline, satellite communications have the potential to penetrate broader markets through automobiles, vessels, and industrial equipment.
Policies are also fostering conditions for industrial applications. In 2025, the Ministry of Industry and Information Technology explicitly proposed supporting commercial trials for low-Earth orbit (LEO) satellite internet, promoting direct smartphone-to-satellite connectivity and integrated terrestrial-space networks, and encouraging operators to collaborate with satellite enterprises on shared infrastructure.
China's satellite communications development benefits from another critical edge: its massive automotive manufacturing, industrial equipment, and communications industries have forged mature terminal supply chains, customer channels, and service networks. Satellite connectivity can seamlessly integrate into markets alongside vehicles, industrial equipment, or industry solutions, continuously optimizing terminal costs and operational efficiency through large-scale applications. These capabilities honed through domestic industrial practice will also serve as a cornerstone for Chinese satellite companies' international forays.
03 From Domestic Applications to Global Markets
LEO satellites continuously orbit, enabling overseas markets to further extend network service coverage and enhance capacity utilization efficiency in specific regions and time slots. As constellation scale grows, global operational capabilities will increasingly shape overall network efficiency. For Chinese companies, expanding international operations while nurturing domestic applications and refining service systems holds significant industrial and commercial promise.
India offers a pragmatic reference point. While satellites can traverse different countries, spectrum coordination, landing licenses, ground gateways, and data management are all subject to local regulatory constraints.
India has witnessed intense debates over whether satellite spectrum should be auctioned or administratively assigned. The 2023 Telecommunications Act established administrative assignment for satellite communications, after which controversies shifted to fee standards. In 2025, TRAI recommended imposing a 4% spectrum usage fee on adjusted gross revenue, with an additional 500 rupees per urban user annually. In September 2026, India's Digital Communications Commission raised the rate to 5%, with reductions to 4% for eligible remote areas. As of October 12, the final plan awaited cabinet approval.
Spectrum fees impact satellite companies' operating costs and involve competitive interests with traditional telecom operators. In March 2025, Jio and Airtel signed distribution agreements with Starlink; while they share a cooperative foundation, they may still harbor disagreements over spectrum rules and market pricing.
Chinese companies venturing into overseas markets must also forge local partnerships.
In February 2026, Brazil's regulator Anatel approved Qianfan's application to operate up to 324 satellites locally, with authorization until 2031. Qianfan had previously collaborated with Brazil's state-owned telecom operator Telebras and inked a cooperation framework agreement with Thailand's national telecom company to expand markets around local broadband connectivity needs. Timespace Daoyu's collaboration with Oman's Azyan Telecom is also progressing, having completed local satellite IoT commercial deployment tests with a 99.15% communication success rate, and plans to extend services to local fishing vessels. Chinese companies are leveraging domestically accumulated satellite communication capabilities to penetrate overseas markets through specific industry demands.
Collaborating with local operators enables leveraging existing channels for terminal deployment and customer service; targeting shipping, automotive, energy, and other industry clients facilitates utilizing established industrial partnerships to gradually expand service scope. Overseas operations must still adhere to national regulatory requirements and build long-term operational and after-sales capabilities.
From industrial applications in the domestic market to sustained expansion in overseas markets, China's satellite internet is charting its development trajectory.
From transoceanic cables to mobile communications, the history of human communication technology has been marked by a relentless pursuit of reducing the cost of long-distance connectivity and expanding communication access. LEO satellite internet is extending this process to oceans, deserts, and regions traditionally challenging to reach with conventional networks. India's eight-cent dilemma serves as a reminder to Musk that he must respect the pricing patterns of mature telecom markets, while also prompting Chinese companies to recognize earlier that technological breakthroughs still necessitate lengthy industrial accumulation before achieving widespread commercial adoption.
China boasts a comprehensive communications industry system and a sufficiently diverse application market. As LEO constellations continue to evolve, these advantages are poised to gradually translate into global product and service capabilities. Ultimately, the extent to which satellite internet can transform lives hinges on its ability to convert formerly expensive, fragile, or unattainable connections into everyday services that ordinary people and businesses can afford over the long haul.
-
![]()
Downward Adjustment of Export Tax Rebate Rate for New Energy Vehicles: Not a Bid to Reap 'Profits' from Overseas Expansion
-
![]()
Who is the Apple in the Era of Embodied AI?
-
![]()
Laughing No More! Brake Pedal Snaps—Is Lei Jun Actually the Biggest Winner? Netizens Say: Genius Move!
-
![]()
Huawei’s ‘Cullinan’ Rival Makes Its Debut: China’s First SUV with a Vertical Emblem—Is It More Prestigious Than Aito or Zunchi?
-
![]()
Blockbuster Move: Geely's Li Shufu Secures Approval to Acquire Stake in Century-Old Ford Motor's Spanish Unit
-
![]()
LiDAR Battle: RoboSense Sells 590,000 Units but Still in the Red, While Hesai Earns 70 Million—What's the Difference?
-
![]()
Vivo's Misstep: The Fallout from Widespread Flash Memory Controversy
-
![]()
Why Did Vivo Stumble Amidst the Flash Memory Mixing Fiasco?